

Fidelity National Information Services Spinoff Notes
July 9, 2023 Update
On July 6, Fidelity National Information Services (FIS) announced that is would sell a 55% stake in Worldpay to GTCR, a private equity firm, at a $17.5BN enterprise value. Fidelity National had previously planned on spinning off the Worldpay division in a tax-free transaction in Q1 2024, but several private equity firms were interested in buying the division, and the offer was too good to ignore.
Key details:
Fidelity National will retain a 45% stake in the business.
It will receive $11.7BN of net proceeds and will use the majority to de-lever the balance sheet from 3.5x leverage to 2.5x leverage.
Fidelity National will have $2.5BN of additional capacity which it plans to use to maximize shareholder value primarily through a share repurchase program.
The transaction will close in Q1 2024.
Although I love spin-offs and, in some ways, would have preferred a spin-off, I have to admit this is a really interesting transaction because it provides almost $12BN of capital for Fidelity National to de-lever and buy back stock. It retains 45% in Worldpay and is now a pure-play software company focused on banking and financial services. RemainCo is facing some issues given the turmoil in the financial sector, but the company looks relatively cheap at 9.9x pro forma EBITDA and 17x pro forma free cash flow.
May 26, 2023 Update
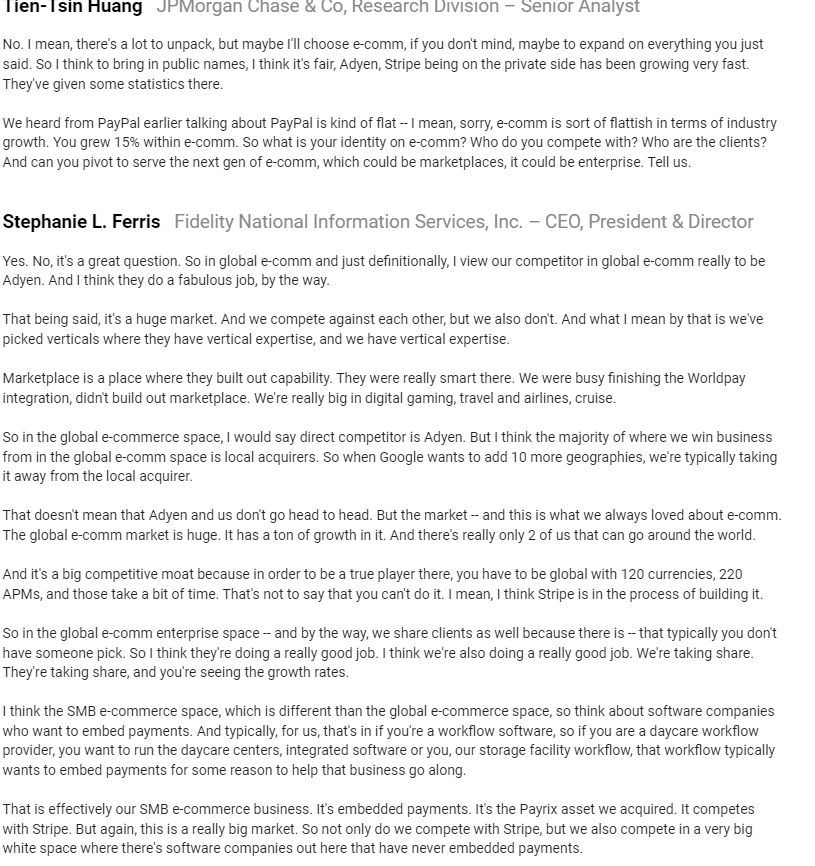
Some comments from the JP Morgan conference this month:


April 7, 2023 Update
Good article from Seeking Alpha: Fidelity National Paying the Price for Worldpay
- The acquisition will be reversed with the spin-off.
February 28, 2023 Update
Fidelity National Information Services (FIS) announced on February 13 that it will spin off its merchant-solutions business in a tax free transaction within 12 months. The merchant solutions business helps nearly 1 million global accept payment and processes more than 100 million transactions per day.
The spin-off unwinds FIS’ 2019 $36BN acquisition of Worldpay. The spin-off is an acknowledgement that the acquisition failed to generate the expected cost and revenue synergies. In 2022, the Worldpay division generated $9.5BN or revenue and $4.2BN of EBITDA. It has lost market share to traditional rivals and upstart challengers in recent years. Guidance is for a 2% to 4% organic revenue decline in 2023.
The RemainCo generates revenue by providing banking and capital-markets technology to financial institutions. In 2022, it generated $9.5BN in revenue and $4.2BN in EBITDA. It has its own challenges and is guiding to organic revenue growth of just 1% to 3%. The revenue growth outlook is challenged as financial institutions hesitate to make purchases in an uncertain market environment.
On a consolidated basis, the company looks relatively cheap at 9.5x forward EBITDA. Over the past 10 years, the stock has traded at a median EV/ mean EBITDA multiple of 12.7x. Nonetheless, I’m not in a rush to buy the stock today given revenue challenges in both the spin-off and the RemainCo.
Leave A Comment