

4 Spin-offs with Insider Buying
One factor that I closely follow in the spin-off universe is insider buying.
Here’s what Peter Lynch wrote about insiders and spin-offs in One Up on Wall Street:
[Spin-offs] are a fertile area for amateur investors…….A month or two after the spinoff is completed, you can check to see if there is heavy insider buying among the new officers and directors. This will confirm that they, too, believe in the company’s prospects.
There are four names in my universe that have interesting insider activity.
Let’s go in alphabetical order….
Amentum (AMTM)
On September 27th, Jacobs spun off its Critical Mission Solutions and Cyber & Intelligence businesses. The spun off divisions merged with PE backed Amentum, and the new company kept the Amentum name.
Amentum performed well in initial trading, but has since traded down on concerns related to the Department of Government Efficiency (DOGE).

The Department of Government Efficiency (DOGE) is a temporary organization established by President Donald Trump on January 20, 2025, through Executive Order 14158. Its primary mission is to modernize federal technology and software to maximize governmental efficiency and productivity.
DOGE operates within the Executive Office of the President and is scheduled to conclude its activities by July 4, 2026. The organization is led by Amy Gleason as the acting administrator, with Elon Musk serving as a senior advisor to the President and acting as the de facto leader of DOGE.
The department has initiated several measures aimed at reducing government spending and enhancing efficiency, including:
- Workforce Reductions: Implementing significant layoffs across various federal agencies.
- Contract and Lease Cancellations: Terminating or renegotiating existing contracts and leases to cut costs.
- Access to Agency Systems: Seeking access to sensitive information and systems within federal agencies, which has led to legal challenges and concerns over data privacy.
How will DOGE impact Amentum?
On its recent earnings call, management said it’s too early to tell:
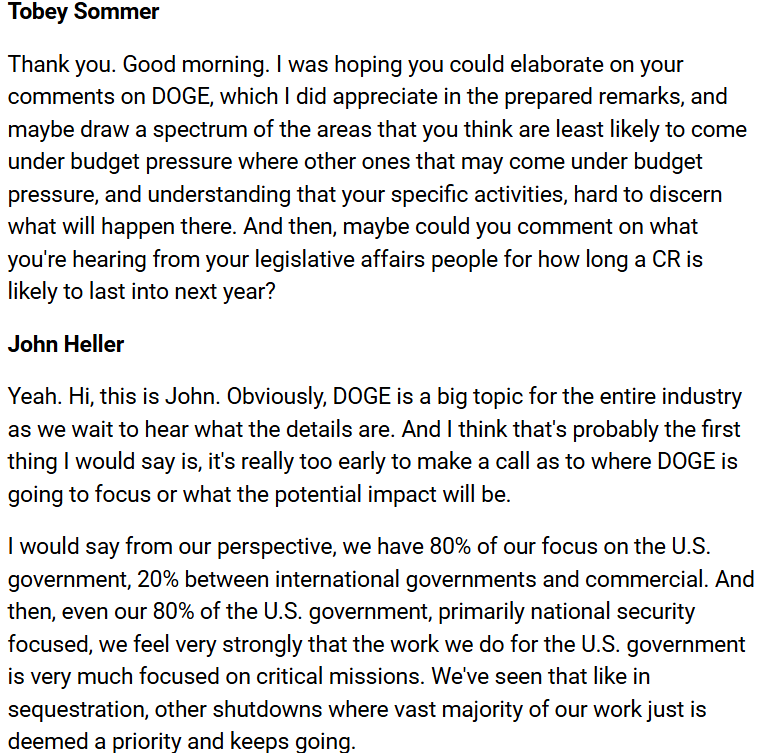
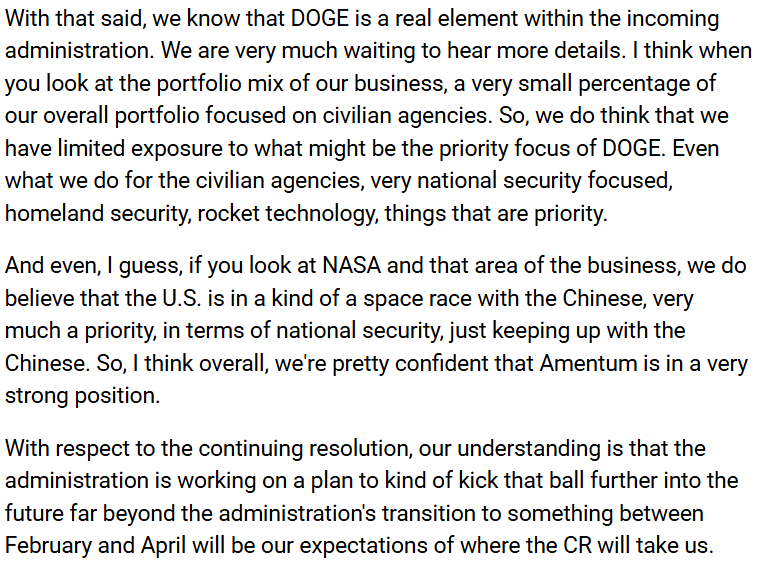
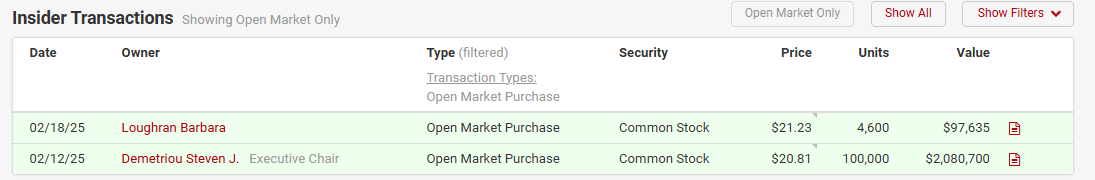
But insiders are buying which signals they think the risk is manageable.
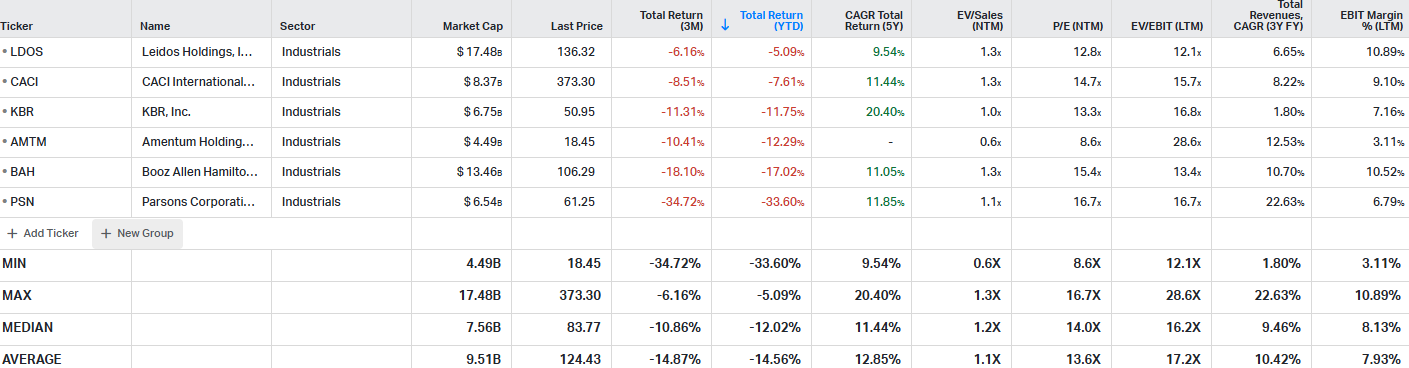
Amentum looks cheap vs its peers and on an absolute basis.
I don’t own this one yet, but it’s tempting.
Everus Construction Group (ECG)
On October 31, 2024, MDU Resources (MDU) spun off its construction services business, Everus Construction Group (ECG).
Everus ranks as the 10th largest specialty contractor in the United States, serving approximately 3,700 customers across more than 40,000 projects in 2023.
Everus offers specialty contracting services to a diverse set of end markets across the United States
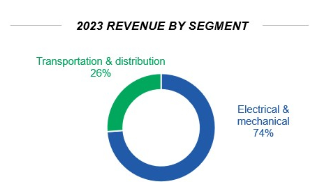
About ¾ of revenue comes from the electrical & mechanical segment while the balance comes from transportation & distribution.
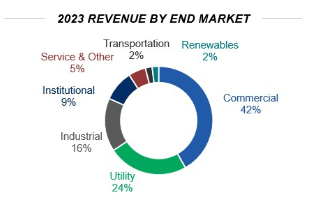
One thing that management touted during the analyst day was that the business is very diversified by end market.
This graphic shows that nicely.
ECG performed well out of the gates (like Amentnum) but has faded recently.
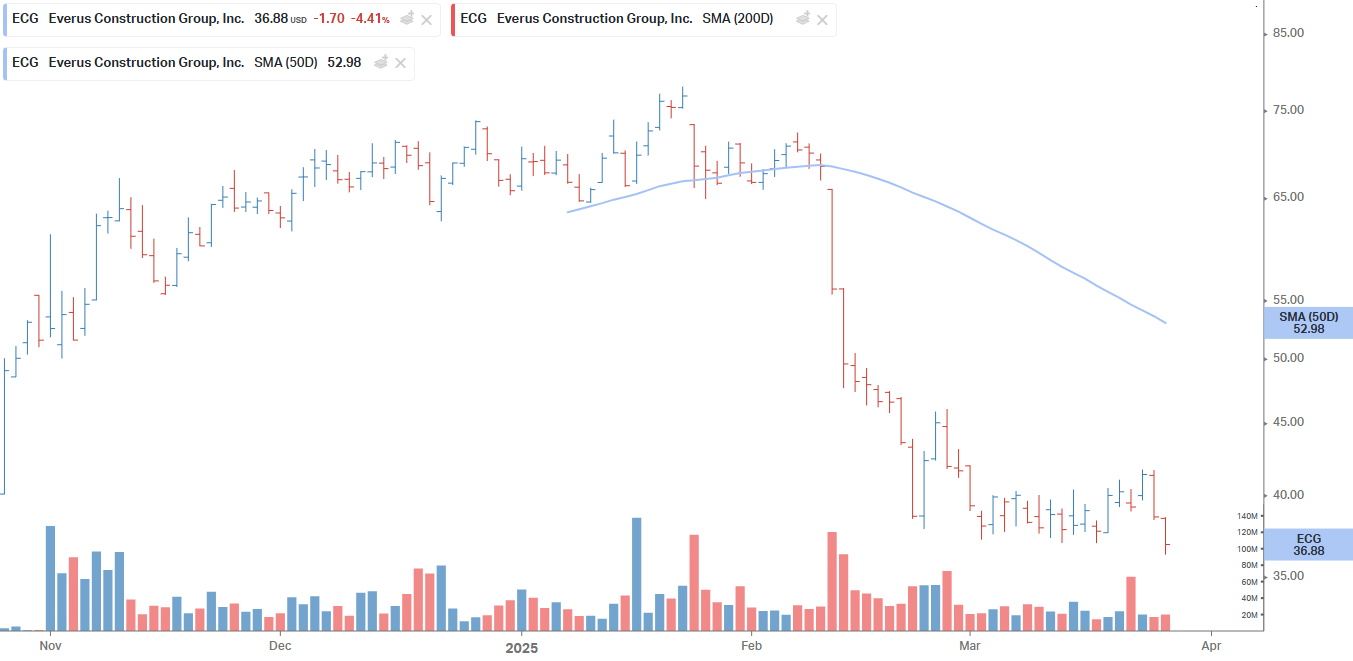
As far as I can tell, the weakness has been driven by slightly higher than estimated expenses next year and less excitement about AI driven electricity demand (which ECG will benefit from).
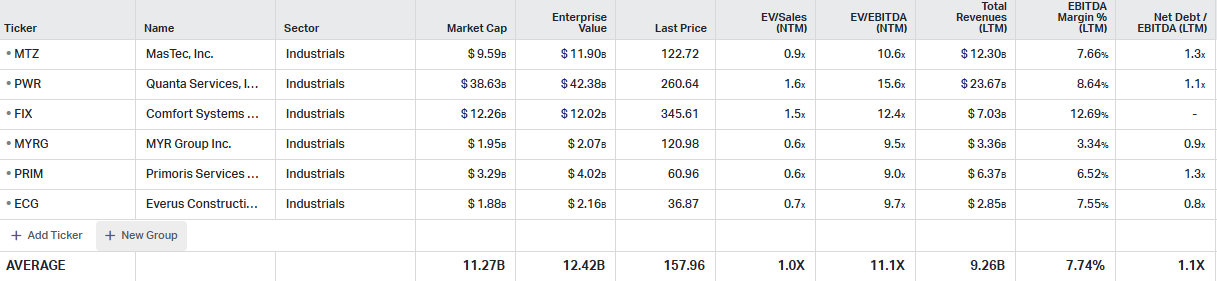
The stock looks fairly cheap.
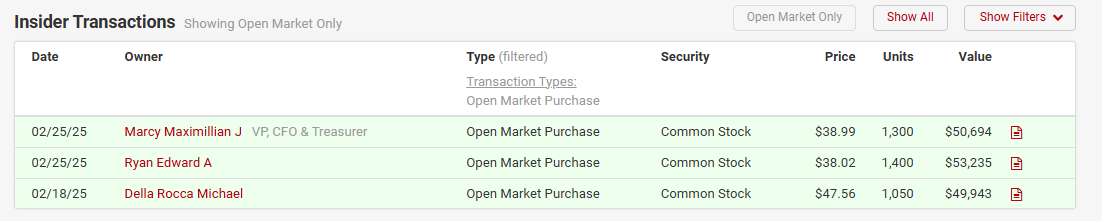
And insiders are buying.
Magnera (MAGN)
On November 4, 2024, Berry spun off its Health, Hygiene, and Specialties Global Nonwoven and Films (HHNF) business which immediately merged with Glatfelter Corporation (GLT).
The new company is called Magnera and trades under the ticker MAGN.
Berry stockholders received 90% of the outstanding shares of Magnera on a fully-diluted basis, and current Glatfelter shareholders retained 10% of the outstanding shares of Magnera on a fully-diluted basis.
Magnera has hung in there in a tough market.
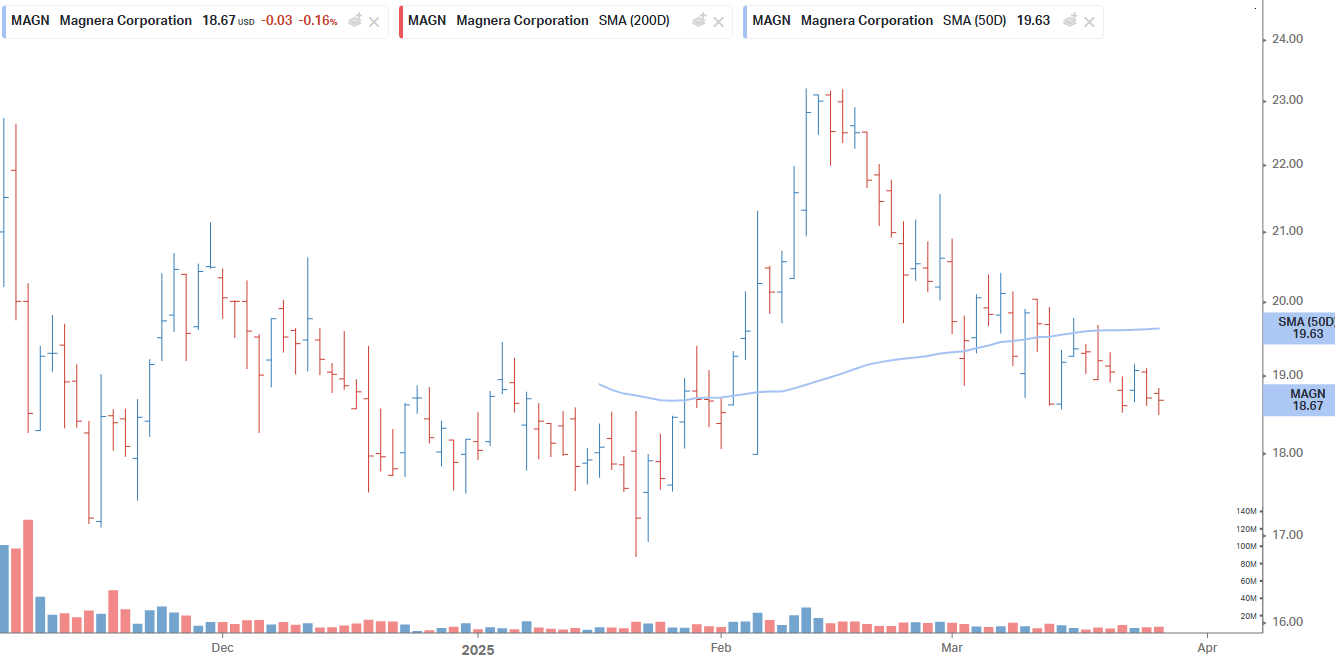
Since the spin-off, Magnera (MAGN) has reported its first quarter as a standalone company and both EBITDA and revenue grew. This suggests the non-woven industry has bottomed.
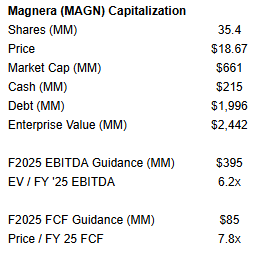
Magnera looks cheap trading at 6.2x EBITDA and 7.8x FCF.
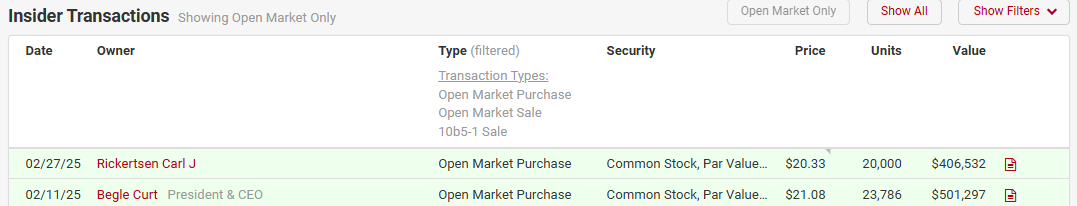
Insiders agree and recently bought in the open market.
Disclosure: I own MAGN
Millrose (MRP)
Lennar Corporation (LEN) spun off 80% of its subsidiary, Millrose Properties, Inc (MRP), on February 7, 2025.
Lennar contributed ~$5.5 billion in undeveloped, partially developed, and some fully developed land assets, along with up to $1 billion in cash, to Millrose. Millrose will operate as an independent entity, acquiring and developing land to deliver finished homesites under land option contracts. Initially, it will serve Lennar but plans to engage with other homebuilders as well.
This strategic move is part of Lennar’s ongoing shift toward an asset-light operating model, aiming to reduce financial risk and enhance returns by minimizing direct land ownership.
Millrose has a book value of $5.9BN and 135MM shares outstanding. It is trading at a dividend yield of 9.1% based on my estimates. MRP is trading at 59% of book value. On the surface this looks cheap, but I’m not too excited.
Millrose will pay out all of its income to shareholders and will not be able to raise equity given its trading at a discount to book value. As such, it will not be able to grow.
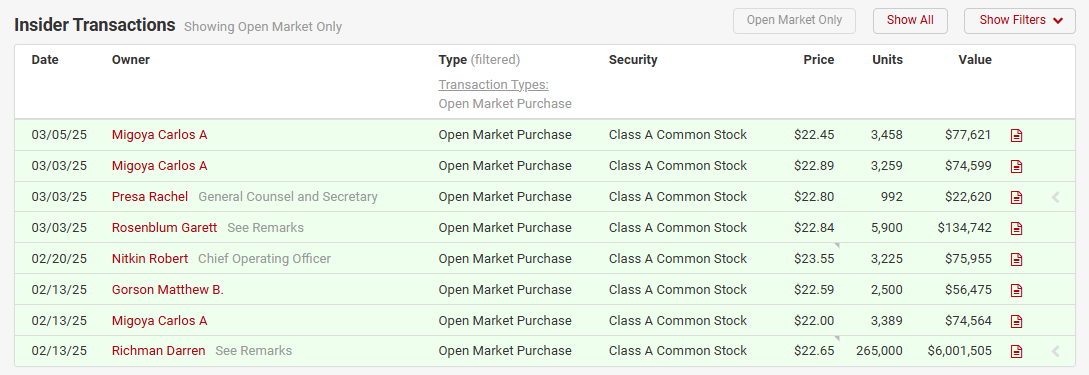
But insiders disagree and have been buying aggressively.

Hi Rich, I’d appreciate opinions/firsthand perspective of Millrose’s management team?
Do you know of any other forums/websites that discuss REITs (such as $MRP)? I looked at Seeking Alpha and Yahoo Finance’s Community…and no one has commented on this stock $MRP or its management quality. Thanks!