

Is There an Opportunity in LSXMA??
In December ‘23, Liberty finalized a plan to merge Liberty Sirius tracking stocks with Sirius XM Holdings (SIRI). The merger was announced to collapse a ~39% discount that existed at the time between the various stocks.
Under the terms of the agreement, Liberty Media’s Liberty SiriusXM tracking stock group (NASDAQ: LSXMA, LSXMB and LSXMK) (collectively “LSXM”) would be exchanged for 8.4 shares of New SiriusXM (NASDAQ: SIRI).
At the time of the announcement (December 12, 2024), LSXMA traded at $27.03 and SIRI traded at $5.23
As such, the arbitrage looked like this:
You could buy 1 share of LSXMK for $27.03 and expect that share to turn into 8.4 shares of SIRI which would be worth $43.93 (5.23 x 8.4).
The discount was 38.5%.
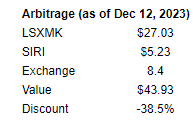
The trade was to short 8.4 shares of SIRI for every share of LSXMK/LSXMB/LSXMA that you owned.
How’d the trade work out?
Pretty well.
Today LSXMK trades for $21.37 and SIRI trades for $2.68 and the discount has collapsed to 4.9%.
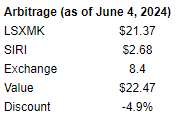
SIRI was relatively expensive to short and that expense would have eaten into your return, but it still worked out to be a nice trade.
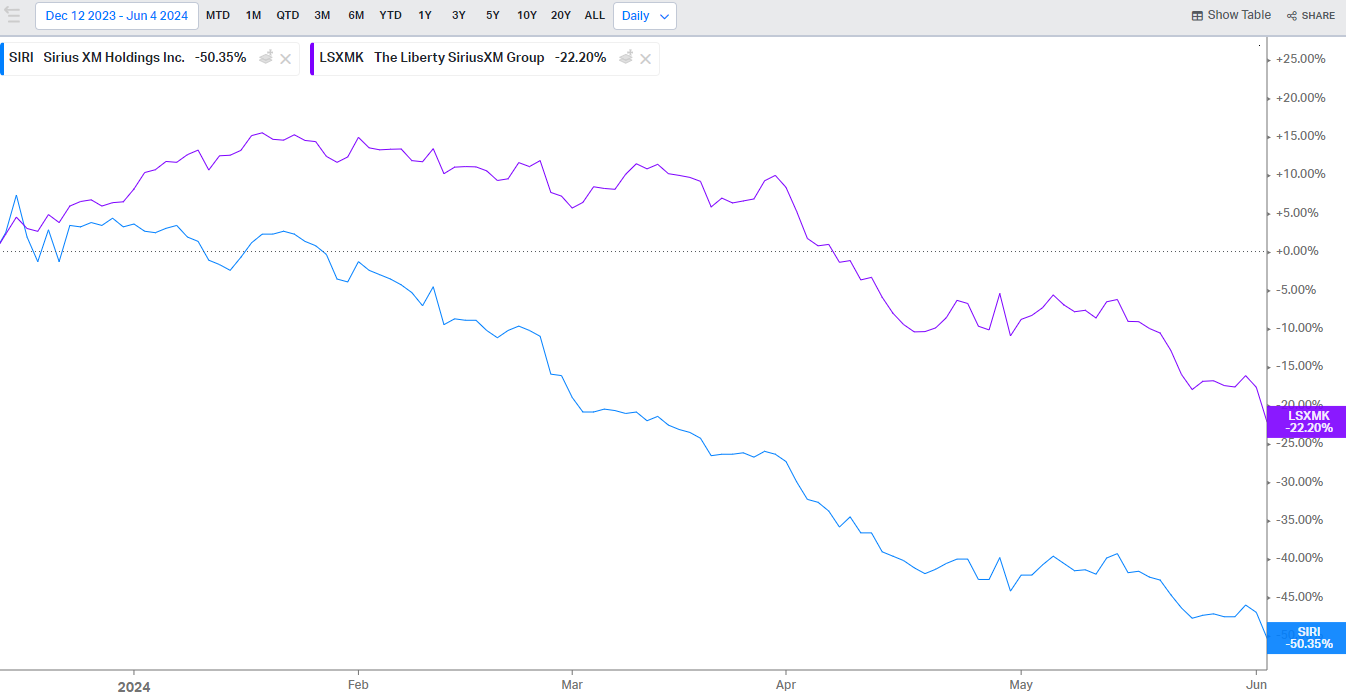
The trade worked not because SIRI appreciated but because LSXMK depreciated less than SIRI depreciated.
What is the Opportunity Today?
Today, the opportunity may be to just buy LSXMK.
Here’s the logic…
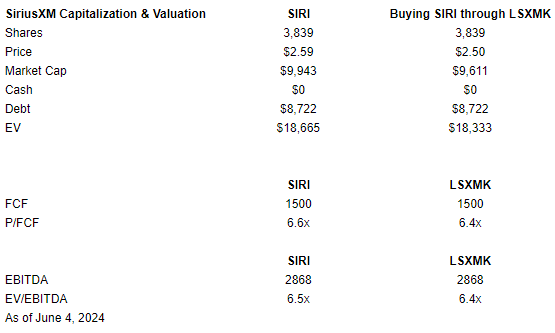
SIRI looks very cheap today, especially if you buy it through LSXMK.
Management published a proxy statement for the transaction which estimated 2025 EBITDA $2,868MM and 2025 FCF of $1.5BN.
On a pro forma basis, SIRI will have 3,687 shares outstanding.
As such, it is currently trading at 6.5x 2025 FCF and 6.4x 2025 EBITDA if you buy it through LSXMK.
How cheap does SIRI look relative to its last 10 years of trading:
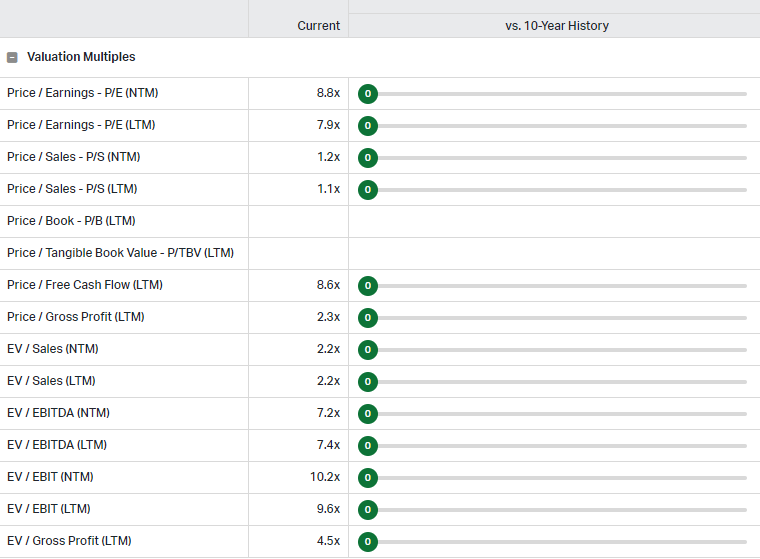
Basically, it’s the cheapest it’s ever been.
Why is the stock so cheap?
There is no reason today to buy SIRI stock. You can buy LSXMA, LSXMB or LSXMK and effectively buy SIRI at a discount so there really is no natural buyer for SIRI.
Furthermore, there is still an attractive arbitrage spread that can be achieved by buying LSXMK and shorting SIRI.
The current spread of 4.9% doesn’t sound like much, but this transaction is expected to close in early Q3. Assuming the transaction closes on July 31, 2024, the arbitrage still looks like it can generate a ~38% IRR.
What is the catalyst for SIRI to rebound?
If you are buying LSXMK (soon to become SIRI) unhedged, you need to believe there is a hard catalyst to stop the bleeding…
One catalyst might be SIRI index inclusion which drives passive flows.
Will SIRI be added to the S&P 400 Index?
To cut to the chase, I think SIRI has a decent chance to be added to the S&P 400, but I don’t think it’s a slam dunk.
SIRI has a market cap of $10.2BN.
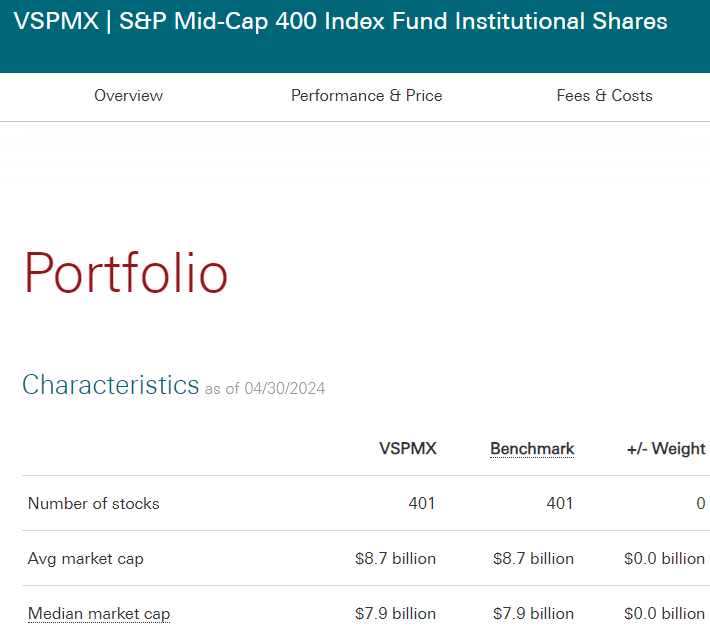
According to Vanguard, the average and median market cap of stocks included in the S&P 400 is $7.9BN and $8.7BN, respectively.
According to S&P criteria, the S&P 400 index includes stocks with market caps that range from $6.7BN to $18BN.
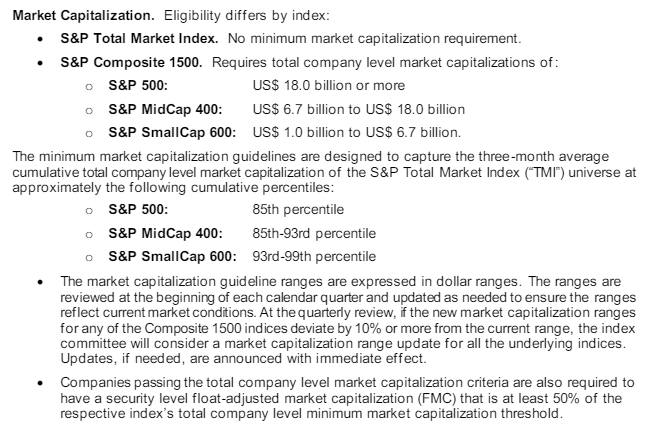
So from a market cap perspective, SIRI has a good chance of being added to the S&P 400.
Its float will improve considerably as well.
Prior to the closing of the Liberty transaction, Liberty SiriusXM Group owned 84% of SIRI. This limited SIRI’s inclusion in various indexes.
To understand SIRI’s chances of being added to the S&P 400, I looked at other communications stocks with similar market caps.
I looked at 5 communications stocks with similar market caps to SIRI. I found that one is in the S&P 400 and one is in the S&P 500, but three were not in either index.
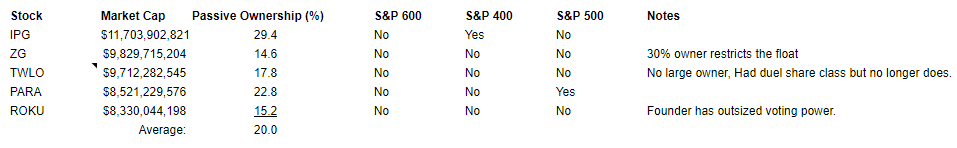
As such, I don’t think it’s a slam dunk that SIRI will be included in the S&P 400.
Regardless of a potential inclusion in the S&P 400, I do think that SIRI’s passive ownership will increase.
By my estimate, the big three passive players (Vanguard, State Street, and Blackrock) own 12.4% of SIRI stock on a look-through basis (assuming Liberty shares turn into 8.4 shares of SIRI).
While passive ownership will probably increase from this level, I don’t have high conviction that it’s going to move the needle.
Conclusion
While I was initially excited about the opportunity to buy SIRI and benefit from passive flows following the Liberty merger, I’m going to remain on the sidelines for now.
What Would Change My Mind?
(1) Buy backs.
Sirius has guided that it will deemphasize buybacks until it reaches its leverage target of mid to low 3x TTM EBITDA. Management expects this to occur in the second half of the year.
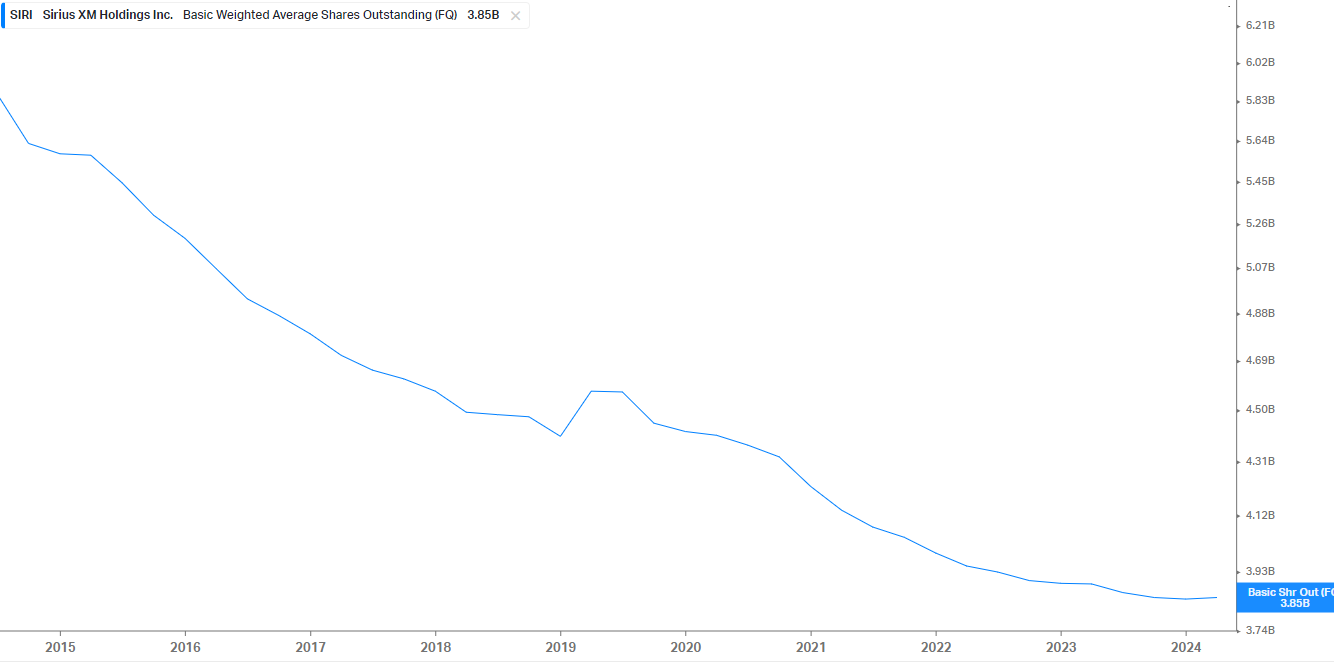
Once buybacks begin, they will move the needle. SIRI is trading at a P/FCF multiple of 6.4x. If the stock stays were it is, management could theoretically retire 16% of its market cap each year!
And historically, SIRI has been aggressive about buying back its own stock…
(2) Indiscriminate selling pressure.
While I was initially expecting index buying pressure after the merger is complete due to increased index inclusion, there is the potential that LSXMA, LSXMB and LSXMK shareholders sell once the transaction is complete.
If we see selling pressure, I think it would represent an attractive opportunity.

Leave A Comment