

Medexus FQ4 2024 Results + Notes from Call with Management
June 28, 2024
Price: $1.27
Summary
Medexus reported a solid quarter on June 25th. Revenue rebounded on a sequential basis from $25.2MM to $26.0MM while EBITDA also rebounded to $4.4MM from $3.2MM. For the full year, Medexus generated revenue of $113.1MM and adjusted EBITDA of $19.5MM. During the year, the company generated $15.2MM of free cash flow. The one negative in the quarter was the news that CFO, Marcel Konrad, has decided to leave the company to pursue another opportunity in the Bay area. Upon speaking with Marcel, my sense is his decision to leave was driven by the attractiveness of the opportunity, not anything having to do with Medexus. Medexus looks compelling today. I expect revenue of ~$105MM, adjusted EBITDA of ~$20MM, and free cash flow of ~$15MM this year. As such, the company is trading at 1x revenue, 5.1x EBITDA, and 2.1x free cash flow. Even better, an FDA decision for Treosulfan is due by October 30, 2024. If Treosulfan is approved, Medexus has the potential to double its revenue and quadruple EBITDA/free cash flow. In Q1 2025, Medexus will learn whether Topical Terbinafine, a nail fungus product, is approved in Canada. This has the potential to generate $20MM to $30MM in annual sales.
Additional Details
Medexus reported fiscal 4th quarter earnings on June 25th.
There were positives and negatives.
Positives
(1) Revenue and EBITDA rebound from last quarter.
- Revenue was $26MM this quarter, up from $25.2MM last quarter.
- Adjusted EBITDA was $4.4MM this quarter, up from $3.2MM last quarter.
Commentary from management suggested that revenue and EBITDA would rebound, but it was good to see.
(2) Free cash flow was strong last fiscal year.
The company generated ~$15MM of free cash flow last year which is impressive for a company with a $31MM market cap.
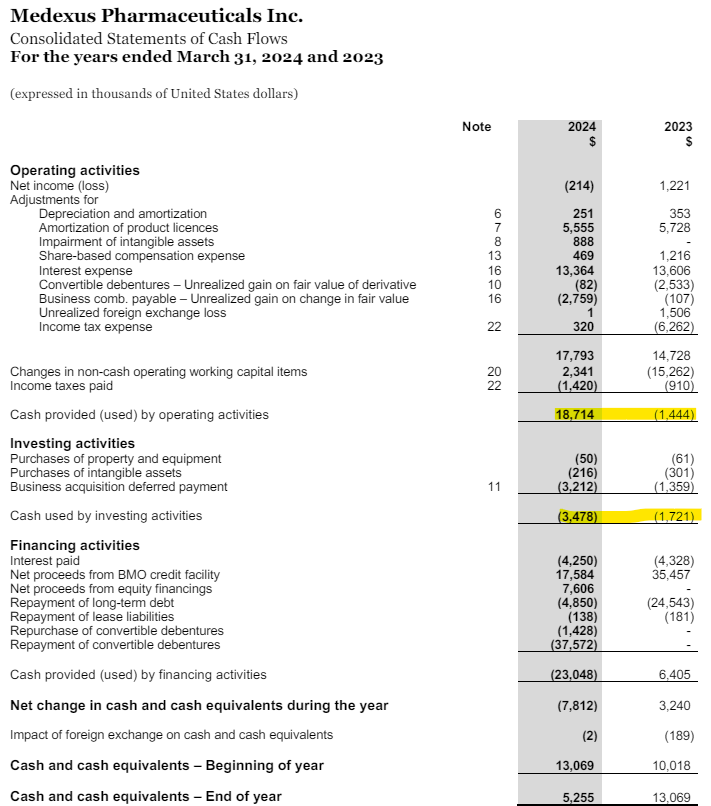
On the call, the company shared that it anticipates paying down $3.3MM of debt per quarterly. This implies at least $13.2MM of free cash flow generation throughout the year. On top of the principal repayment, Medexus will have to pay cash interest ($51MM of debt x 8.2%) of ~$4.2MM.
This is quite impressive for a company with a $31MM market cap.
The other positive is that the company’s debt burden is now quite reasonable. At year end, debt will be $38MM. Relatively reasonable for a ~$20MM EBITDA company.
Now the negatives:
(1) The CFO (Marcel Konrad) is leaving to pursue other opportunities. I view this as a negative given that he is a straight shooter and has been helpful to talk with periodically. I like Ken (the CEO) but Ken is a bit more promotional and so I liked to talk to Marcel. Also, the former CFO left in 2021, although I think he was kind of pushed out to upgrade the position. But it’s not great to see heavy turnover in the CFO position. Also, would the CFO leave if he thought Treosulfan was going to be improved imminently?
Since my initial thoughts, I’ve gotten more comfortable with Marcel leaving. I had a chance to talk with him, and it sounds like he got offered a very attractive opportunity in the Bay area. He can’t share the name of the company that he’s going to (because it hasn’t been announced publicly), but the way he talked about it, it seemed like a very attractive opportunity. It doesn’t seem like he’s leaving because of anything at Medexus but rather because he has a very attractive opportunity. Also, he probably made his decision prior to the FDA accepting the Treo resubmission. Finally, he seems to last 4 or 5 years at each company (he was at his last company, CareDx, for 4 years; he was at his previous company, Santen, for 5 years).
(2) Revenue growth will be nonexistent until (if) we see Treo approved and Topical Terbinafine (Canada).
Honestly, this really isn’t too much of a negative because we knew this was the case last quarter.
IXINITY is facing pressure due to macroeconomic issues and competitive products (extended half life products). Rasuvo is facing competitive pressure from one drug (Otrexa) and is cutting its price to maintain its 80% market share.
Final Thoughts
All in all, the stock remains incredibly cheap at 1x annualized revenue and 5.1x annualized EBITDA. It’s trading at 2x free cash flow. The stock is especially cheap considering there are two sizable catalysts ahead: 1) Treosulfan approval. This would be transformational as it has the potential to more than double the company’s revenue and quadruple its EBITDA (October 30, 2024 FDA decision date). 2) Topical Terbinafine approval (Q1 2025 approval). This would be a large opportunity ($20MM to $30MM annually starting in 2025). What could the stock be worth assuming Treo is approved? We would have line of sight to $200MM+ of revenue and $60MM+ of EBITDA. Assuming the valuation stays the same (5x EBITDA), the stock could potentially be worth an enterprise value of $300MM, market cap of $227MM and share price of $9.30. Arguably, 5x EV/EBITDA multiple would be too cheap. If we assume a 2x revenue multiple inline with specialty pharma peers, and the numbers get silly. What happens if Treo is not approved? It would be disappointing and I’m sure the stock would trade down, but the stock is already pretty darn cheap at 5.1x EBITDA and 2x FCF. Plus we would still have the potential catalyst of Topical Terbinafine approval (Q1 2025).
Notes from Conversation with Medexus CEO and CFO
On 6/28/2024, I had a conversation with Ken d’Entremont (CEO) and Marcel Konrad (CFO). See my notes below.
Q&A
Marcel, why are you leaving Medexus?
It has nothing to do with the opportunity at Medexus but more to do with the opportunity that I was offered. It’s going to be in the Bay area in the tech field, and it’s an opportunity that I couldn’t turn down. I can’t share where I’m going because the company hasn’t made it public. I pride myself on developing a deep bench and believe that Brendon Buschman (who joined in 2019 and worked closely with Marcel) will do a great job leading the organization as the CFO.
I was a little surprised that the FDA accepted the Treosulfan resubmission just given how long the product was delayed. Were you surprised? What is your confidence level that the Treo will be approved?
Ken: I was not surprised. The FDA wants the drug approved. There is an extended access program whereby doctors can request to use a drug that hasn’t been approved yet. To request the drug, a doctor has to fill out a report on why the drug is appropriate. And then it takes FDA resources to evaluate the request. So far, there have been 38 requests by doctors to use Treo in the US and they have all been approved. That leads me to believe that the FDA will approve the drug.
I was expecting the stock to be in the $2 to $3 range post FDA acceptance. I’m surprised the stock hasn’t moved much. Any idea why the stock hasn’t reacted more favorably?
Ken: There is a $3BN fund that has held the stock for a while and they were selling. We believe they are out of the stock right now.
Revenue of $26MM in the last quarter. EBITDA of ~$4.4MM. Do you expect revenue/EBITDA to be stable at those levels until either Treo and/or Topical Terbinafine are approved?
Ken: Yes. Revenue should be fairly stable. There may be a modest improvement. The cost structure is very predictable. So if there is revenue upside, it will flow through to the bottom line. May add a little spend in anticipation of Treo approval but nothing major. From a revenue perspective, Gleolan has some potential, Rasuvo is struggling a bit, but Rupall will probably benefit from a big allergy season in Canada.
Marcel: The business is quite stable/predictable right now. Unless something unexpected happens, have very good visibility into EBITDA and cash flows. Expect to pay down $3.3MM of debt each quarter. The bank (BMO) has seen our forecasts and is comfortable with them/our performance.
Still expect $100MM+ potential from Treo?
Ken: Yes, Treo will have much higher gross margins and will bring up company EBITDA margins. Have a ton more information from selling it in Canada. Don’t believe the label that the FDA gives will be terribly important. It’s clear that doctors want to use the drug.
Are you in negotiations with medac about a potential milestone payment for Treo approval?
Ken: Yes. The old agreement would have called for a $15MM to $45MM payment to medac. It would have had to be paid within 6 months of approval. The payment (Whether closer to $15MM of $45MM would depend on the label). We believe that the label that Treo is approved with would have corresponded to closer to a $15MM payment. We don’t think the label will be terribly important. We think doctors are going to want to use it if it’s approved.
Topical Terbinafine potential approval?
Ken: Expecting approval in Q1 2025 and believe the product could have $20MM to $30MM potential. Believe the product will be nicely differentiated from the current standard of care, Jublia (once a week vs. every day).
Should I expect IXINITY to decline at 6% per year going forward?
Ken: That is the recent experience and you could assume that but it might be conservative. With the pediatric approval, that could help the drug grow again.
What should I expect with Rasuvo?
Ken: A competitive drug has come in and priced at a 20% discount to Rasuvo’s price. Formularies have then come to Medexus and asked to match the price which Medexus has done. That has driven the weakness. But Medexus has the lowest price manufacturer and is in a good position. Just don’t want to give the competitor a foothold. Price could come back up a bit over time. Pricing seems to have troughed. Expect to be able to keep it at least flat.
Has the increased capital gains tax created selling pressure in Canada?
Ken: I don’t know but a lot of people are upset about it. I’ve started 2 businesses in Canada and I wouldn’t start a 3rd here. A lot of people are talking about moving.
Disclosure:
Rich Howe owns shares of MEDXF. All expressions of opinion are subject to change without notice. All published emails/articles/correspondence is provided for informational purposes. We do not warrant the completeness or accuracy of this content. Please do your own due diligence and consult with an investment adviser before buying or selling any stock mentioned on www.stockspinoffinvesting.com.
Leave A Comment