3 Spin-offs with Insider Buying
One factor that I closely follow in the spin-off universe is insider buying.
Here’s what Peter Lynch wrote about insiders and spin-offs in One Up on Wall Street:
[Spin-offs] are a fertile area for amateur investors…….A month or two after the spinoff is completed, you can check to see if there is heavy insider buying among the new officers and directors. This will confirm that they, too, believe in the company’s prospects.
There are three names in my universe that have interesting insider activity.
Let’s go in alphabetical order….
Enhabit (EHAB)
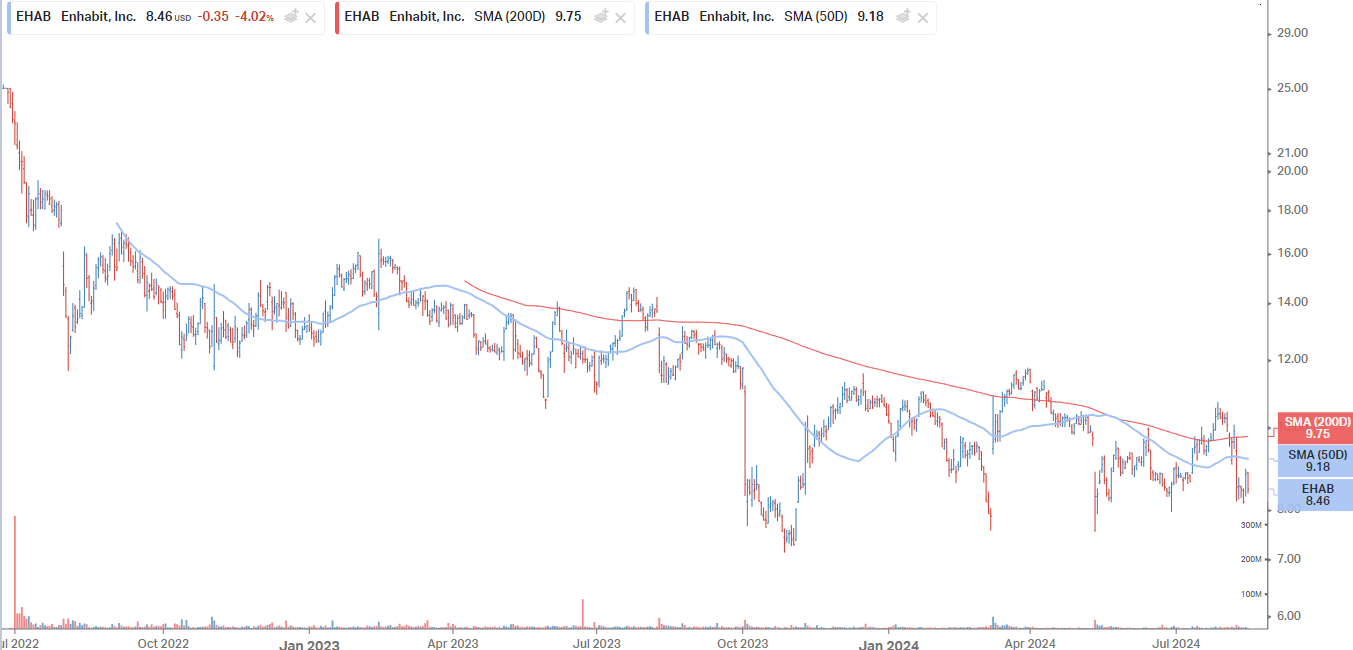
Enhabit has been on my watch list for a long time (ever since its spin-off in July 2024).
And insiders have been buying for a long time.
But the stock has been a disaster.
What does Enhabit do?
It’s a home health and hospice company which was spun out of Encompass Health (EHC).
Clark Street Value did a nice job writing the stock up recently.
To quote Clark Street, “home health and hospice care has some strong tailwinds with an aging population, a push towards cheaper healthcare settings and a highly fragmented market (even the larger players like Enhabit only have single digit market shares) in need of consolidation (clinic/route density is an important driver of operational leverage).”
The thing that was always interesting about Enhabit was the takeout potential.
The home health market is very fragmented and most of the other home health players have been acquired.
LHC Group (LHCG) was acquired for 21x EBITDA. Amedicis is in the process of getting acquired by UNH and currently trades at 13.4x EBITDA.
EHAB is currently trading at 10x EBITDA.
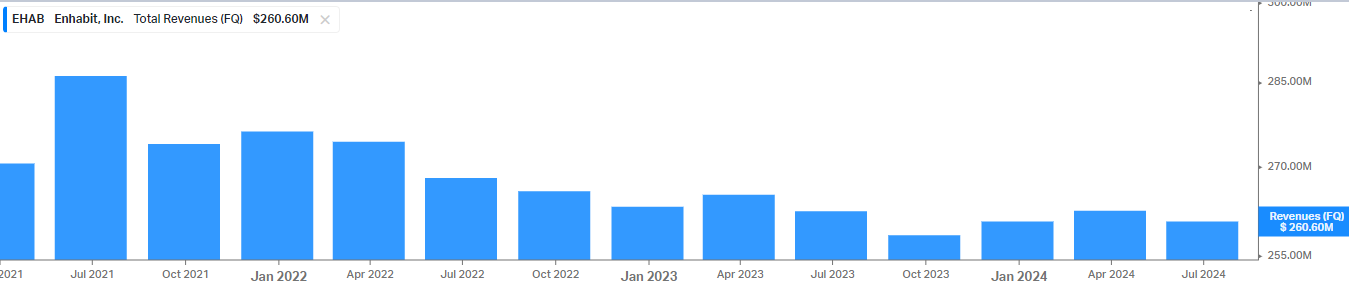
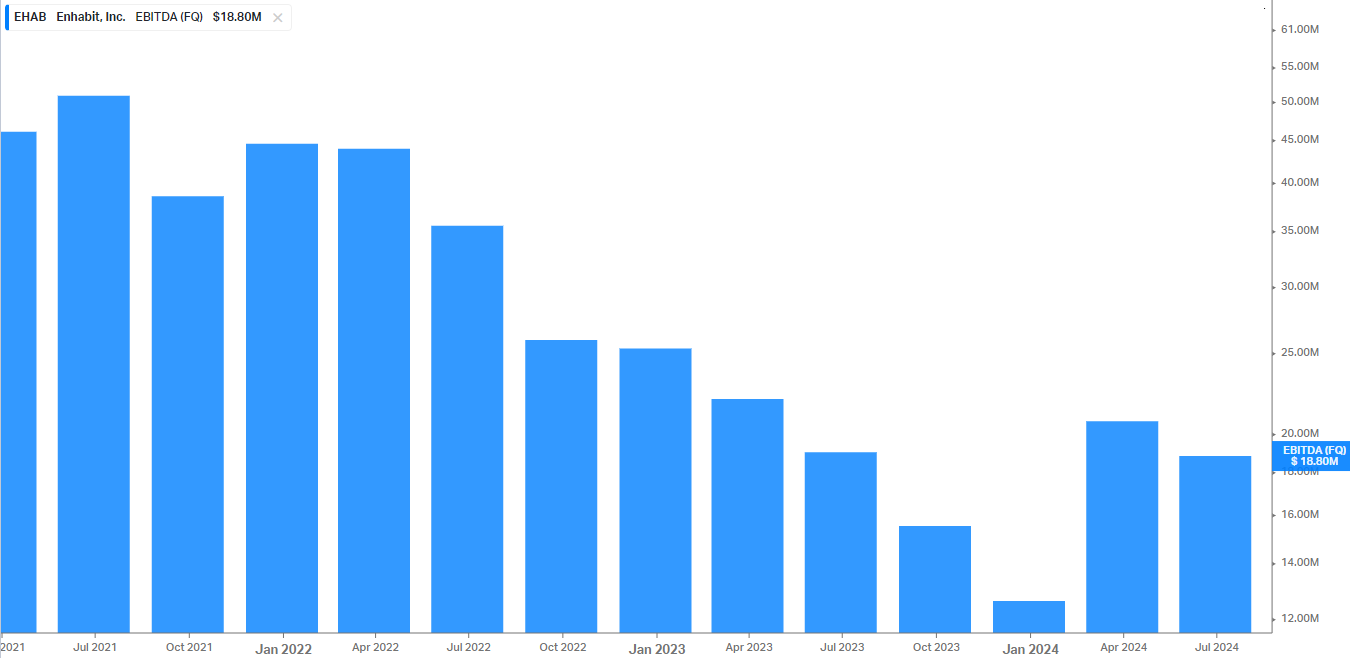
My problem with EHAB was the fundamentals looked bad and were getting worse. Both revenue and EBITDA were shrinking. This isn’t a good combination when you have 5x leverage.
But the good news is that the business appears to have troughed or is close to troughing.
What is driving the turn around?
As far as I can understand it (still digging into this to fully understand it), at the time of the spin-off, EHAB had a large exposure to medicare and the shift from traditional medicare to medicare advantage (less profitable) had a disproportionate impact on EHAB’s top and bottom line.
But the company has been working to re-price contracts to improve profitability. See the EBITDA chart above which appears to show a bottom.
I’m going to continue to dig deeper to gain higher conviction that EHAB is turning around but insiders continue to buy…
Howard Hughes (HHH)
Howard Hughes (HHH) is a name that I like a lot.
It recently spun-off Seaport Entertainment (SEG) and is now a pure play Master Planned Community (MPC) company. It has a massive land bank and sells the residential land to home builders and keeps the commercial land to develop retail, residential, and office properties.
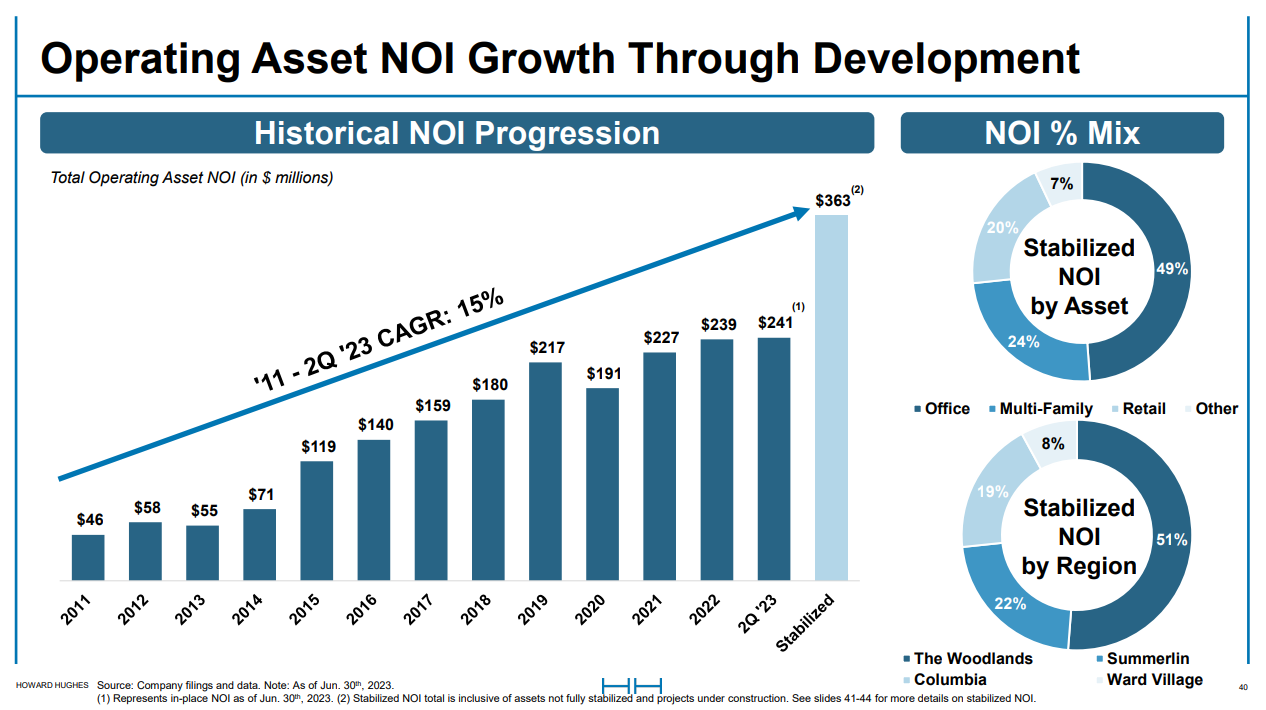
It is self funded and has grown NOI nicely over time.
Seaport Entertainment (the spin-off) has valuable assets but was a cash burner….
Here’s a peek at SEG’s historical operating losses:
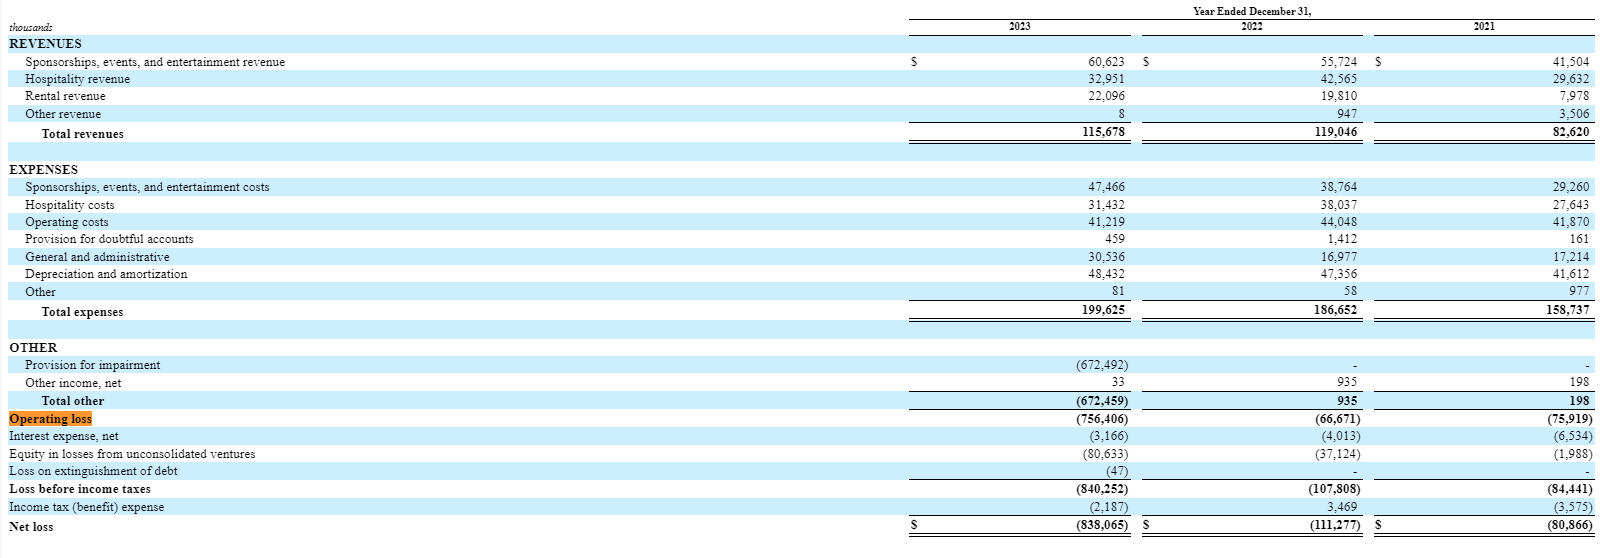
And the above ignores substantial capex requirements.
With the Seaport Entertainment spin-off complete, Howard Hughes RemainCo will see a nice increase in profitability.
RemainCo (excluding Seaport) NAV is probably ~$109.
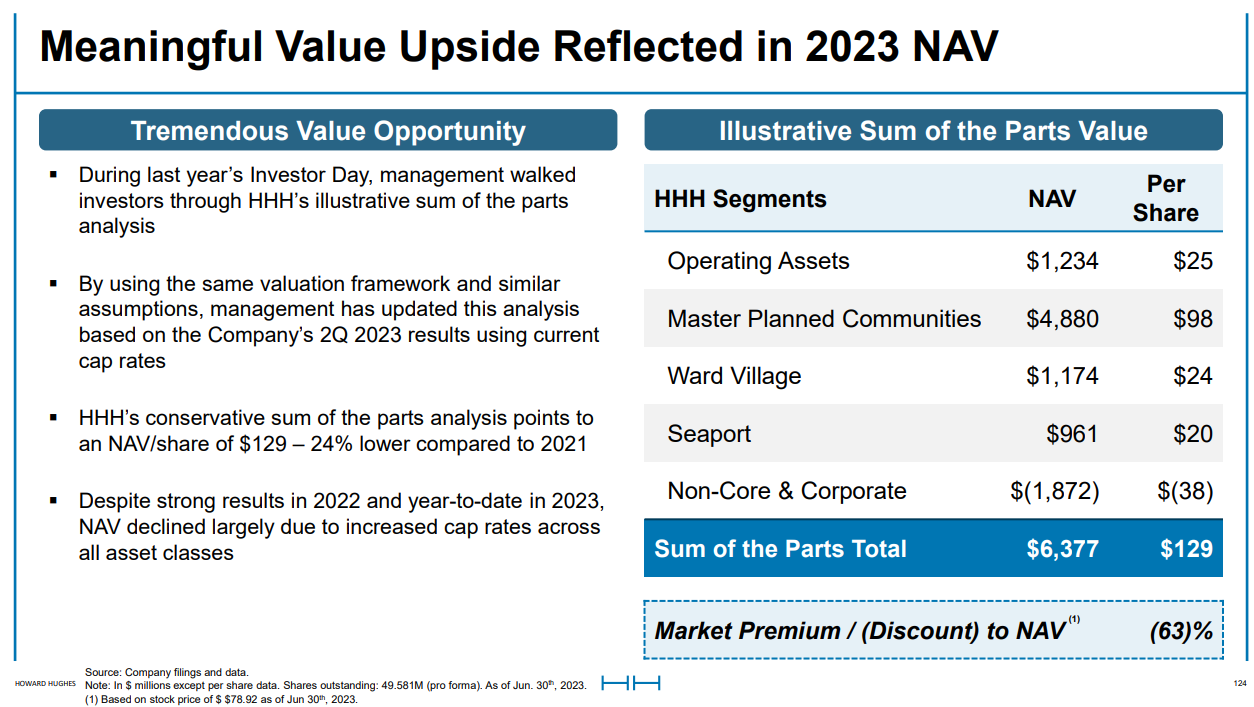
The stock currently trades at $71.
Better yet, insiders are buying…
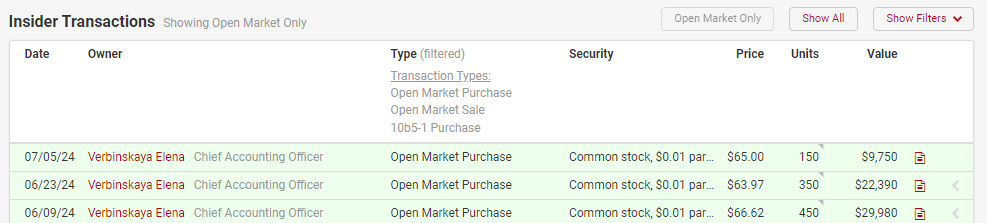
And Bill Ackman’s Pershing Square Capital is evaluating taking Howard Hughes private (it already owns 37.5% of the company).
The good news with Howard Hughes is that its core business is humming (fundamentals look terrific). A takeout would be a nice positive surprise, but we don’t need it for the stock to work.
Howard Hughes will host an analyst day this fall which could be a nice catalyst.
Lions Gate Entertainment (LGFA/LION)
Lions Gate Entertainment is a fascinating situation.
Lions Gate Entertainment (LGFA) recently merged its studio business with a SPAC (Screaming Eagle Acquisition Corp).
The merger has been completed and the new company is now named Lionsgate Studio. It trades under the ticker LION.
Lions Gate Entertainment (LGFA) owns the Starz business as well as 87% of Lionsgate Studio (LION).
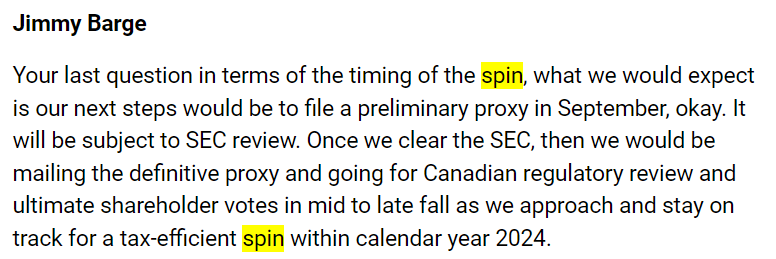
The plan is to spin off the stake in LION by the end of calendar 2024:
LGFA’s market cap is currently $2.5BN and its 87% stake in LION is worth $1.8BN.
What does LION’s valuation look like on a standalone basis?
By my math (I treat film obligations as debt), LION has an enterprise value of $5.4BN. As such, it’s trading at 13.2x 2026 EBITDA.
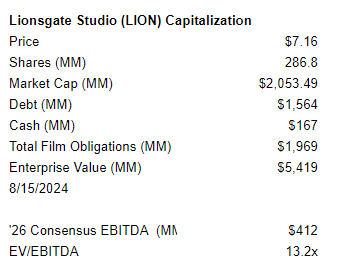
13.2x 2026 EBITDA doesn’t look dirt cheap, but it does look relatively cheap for a studio business.
Historically, studios have been acquired for 16x EBITDA or higher:
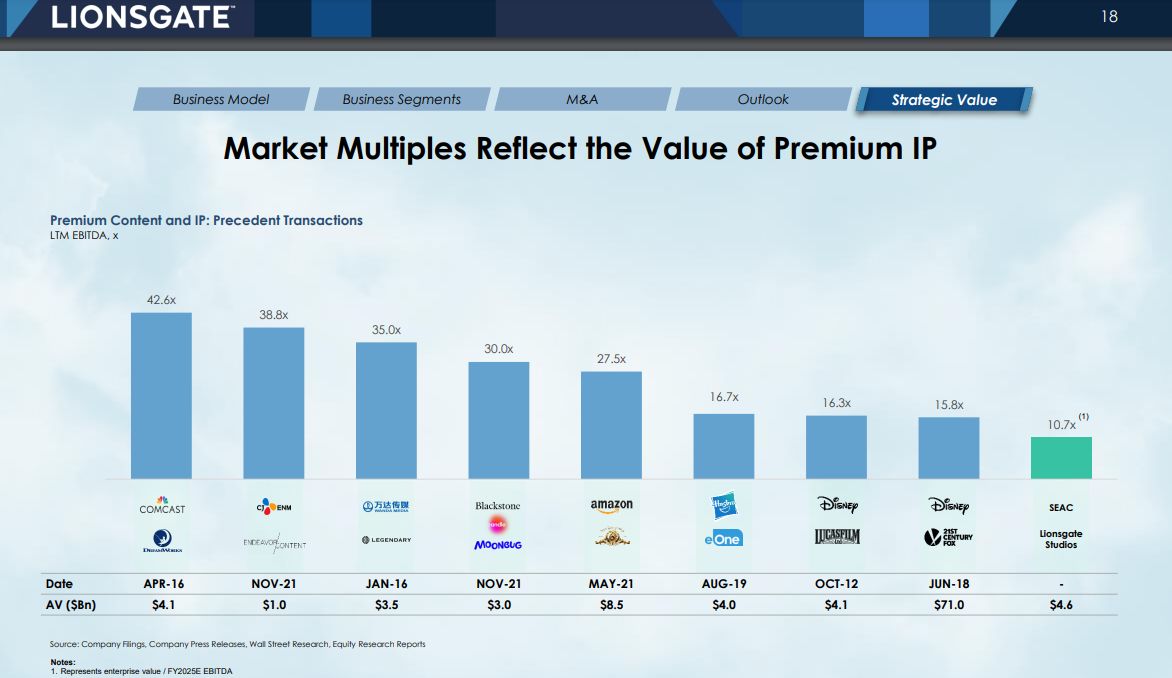
(note the 10.7x multiple for Lionsgate doesn’t include film obligations in Enterprise Value)
Assuming LION is worth 16x, the stock should trade for $11.30.
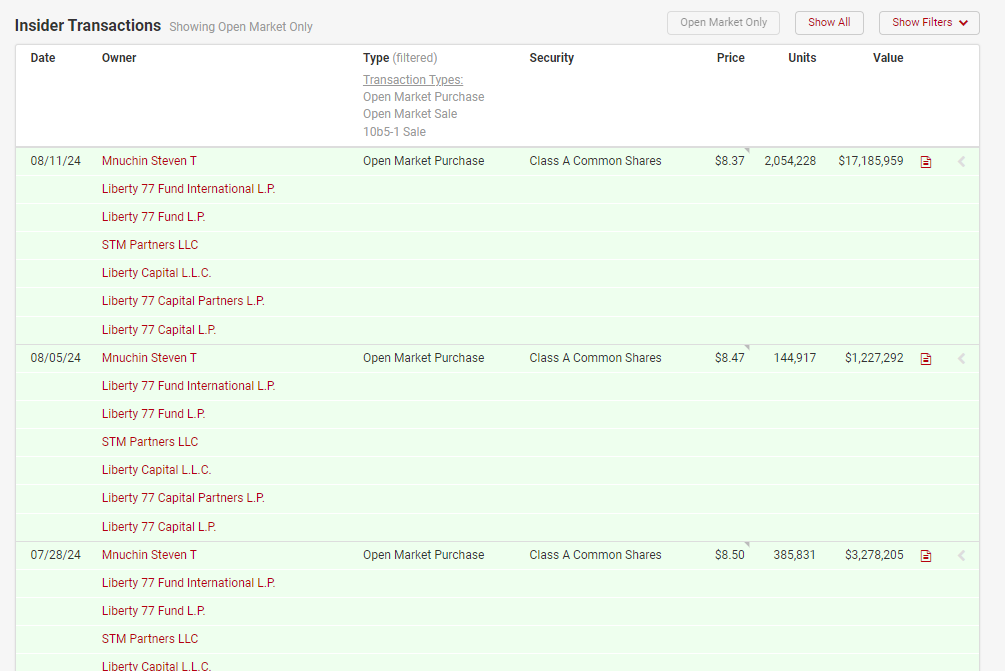
And insiders have been gobbling up shares.
I’m intrigued but not quite ready to pull the trigger on LION or LGFA….

Leave A Comment