

Derek Pilecki of Gator Capital Discusses His Approach to Investing in Financial Spin-offs
I loved having the opportunity to talk to Derek Pilecki of Gator Capital about his approach to investing in spin-offs.
Derek’s hedge fund has compounded at 20.99% since inception on July 1, 2008.
You can request to receive his quarterly letters here (highly recommend).
Derek’s results speak for themselves; he’s an excellent investor. His “common sense” approach reminds me a lot of the approach that Peter Lynch espouses in his book One Up on Wall Street.
My key takeaways from the interview are:
(1) Financials spin-offs are a great place for alpha because many generalist investors have scars from the GFC and would prefer to avoid the entire sector
(2) Don’t rule out spin-offs that are distributed through IPO (I usually only focus on pure spin-offs). While the IPO process is typically efficient, investors don’t typically get excited by financial IPOs and great bargains can be had even after the IPO. Here are some examples that we discussed:
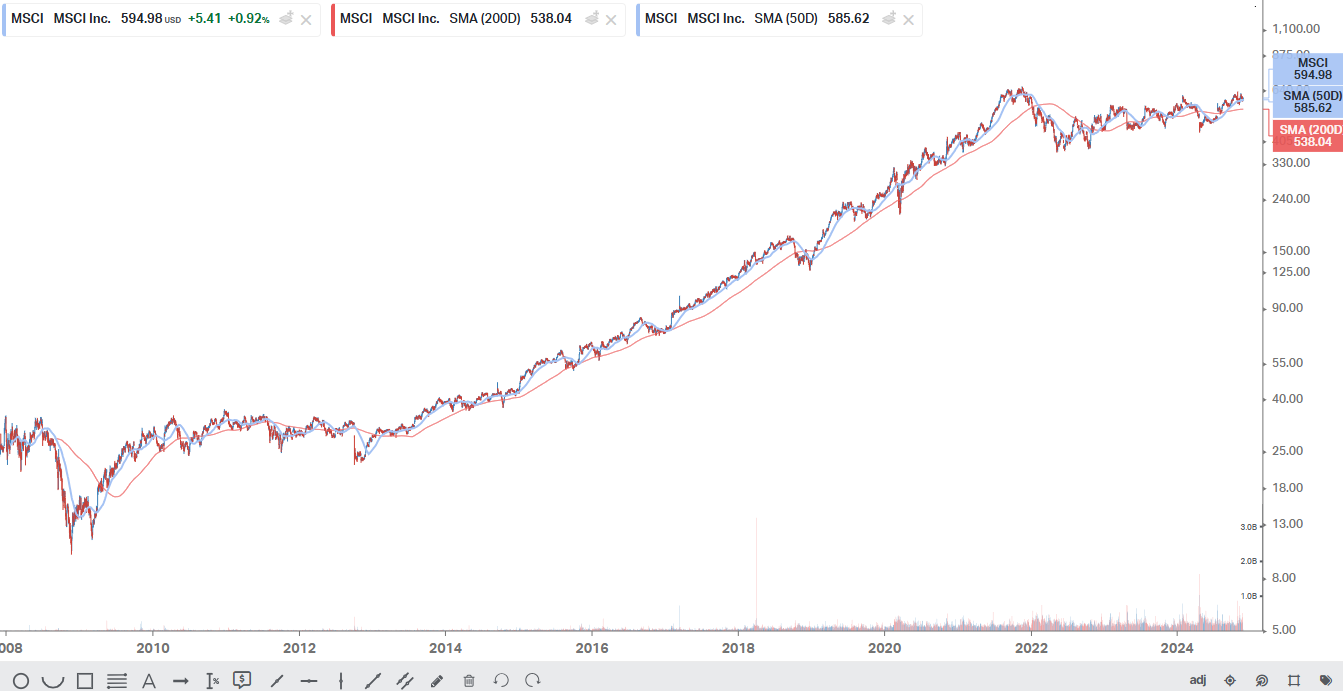


(3) Look for situations where the parent company is a “forced” seller or needs to IPO a subsidiary to raise cash (MSCI, VOYA, and PRI) as these often represent attractive setups.
You can watch my interview with Derek on YouTube here.
Or you can listen on Spotify here or on Apple here.
Here’s what we covered:
0:54 – How Derek founded Gator Capital
4:40 – Gator Capital current AUM
5:40 – What it was like to start a financials focused hedge fund right before the Great Financial Crisis
7:40 – If Derek had to start his hedge fund from scratch, he would do this differently
10:00 – How Derek Approaches investing in spin-offs
12:45 – Derek’s Jackson Financial (JXN) thesis
17:17 – Is Jackson Financial a “Black Box”?
19:38 – Spin-offs and paired trades
21:54 – Derek shares his BBX Capital investment thesis?
23:36 – Corporate governance at BBX Capital
24:36 – Why Derek is expecting a tender offer for BBXIA relatively soon
27:23 – How Derek uses barebones technical analysis.
31:25 – What was Derek’s thesis with Virtis Investment Partners (VRTS)?
36:16 – Derek shares his Voya Financial (VOYA) investment case?
38:46 – Why weren’t investors interested in the VOYA IPO?
40:18 – Why Derek view secondary share overhangs as nonevents
41:30 – Derek walks through the Primerica IPO from Citigroup and how it was an attractive setup

Leave A Comment