

Weekly Update (IDT, RHLD, SNRE, SNDK)
March 7, 2025
Good morning,
Our March webinar starts now. You can use this link to join:
https://us06web.zoom.us/j/85794312105
Agenda:
- Thoughts on Recent Spin-offs: SNDK and RHLD
- Thoughts on Imminent Spin-offs: LION
- Thoughts on Sunrise Communications on whether the “Dividend as a Catalyst” thesis is still valid.
- Updates on All Recommendations
- Answer Your Questions
Weekly Update
If you haven’t already, consider joining our discord channel (included with your paid subscription):
Join Discord Channel (you must create a free discord account to join)
It’s basically a chat room where we discuss what’s going on in the special situation market:
Here are a few things we discussed this week:
1. Discussion of weakness in Sunrise Communications
2. Discussion of Howard Hughes and the Pershing Square Capital Offering
3. Discussion of the WEX Odd Lot Tender Offer
New Spin-off Announcements
There were no new spin-off announcements this week.
The Middleby Corporation (MIDD) announced its plan to spin off its food processing business on February 25, 2025. This strategic move aims to allow Middleby to concentrate on its core commercial foodservice and residential kitchen equipment sectors, while enabling the new entity to focus exclusively on food processing operations.

The spin-off is expected to be executed as a tax-free transaction, with completion anticipated by early 2026. The newly formed company will specialize in equipment and technologies for industrial protein, bakery, and snack processors. Post-separation, Middleby will continue to focus on its commercial and residential kitchen equipment businesses, pursuing growth through mergers and acquisitions.
The announcement was made after Ed Garden, founder of Garden Investments, established a 5% stake in the company and advocated for change.
MIDD trades at 12x forward EBITDA and 17x forward earnings. This transaction should unlock value as the spin-off, with higher margins and faster growth, should trade at a higher multiple. Analyst Mircea Dobre from Baird believes Middleby is worth $227 on a sum-of-the-parts (SOTP) basis.
Recent Spin-offs
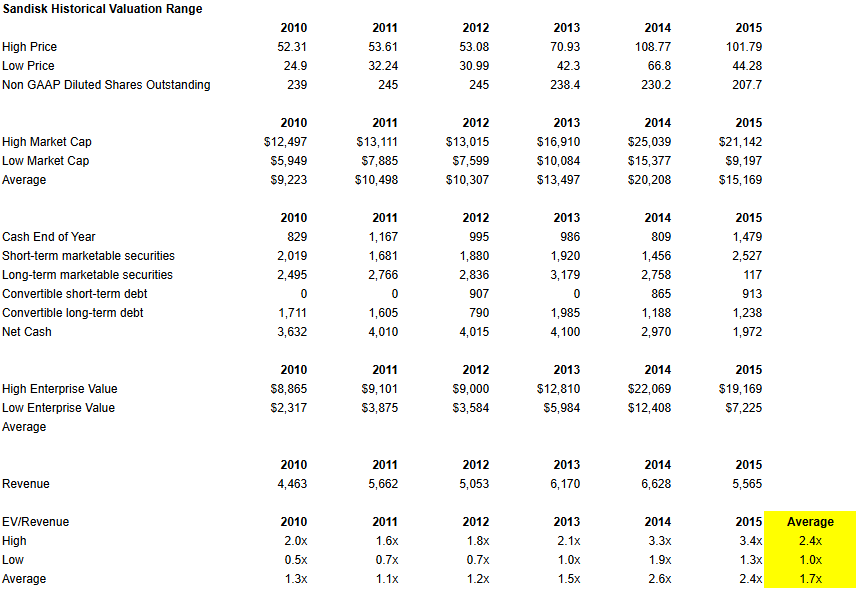
Western Digital (WDC) spun off is NAND flash business, Sandisk (SNDK), on February 24, 2024.Sandisk opened regular-way trading $52 and has since declined to $49. At Sandisk’s current price, it is trading at 1.0x revenue.
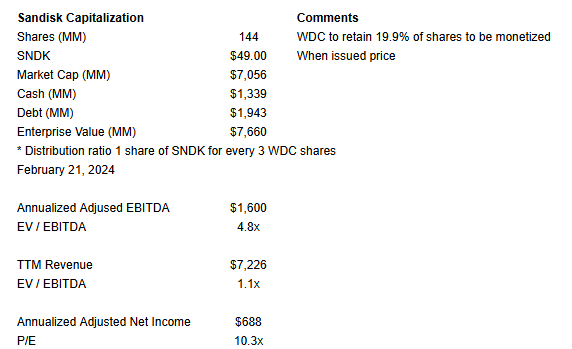
This valuation looks cheap relative to Xioxia (Sandisk’s JV partner) at 1.4x revenue and Sandisk’s historical valuation range (1x to 2.7x revenue) the last time it was a public company.
Western Digital RemainCo looks like a compelling story. It’s benefiting from secular tailwinds of increased data storage needs.
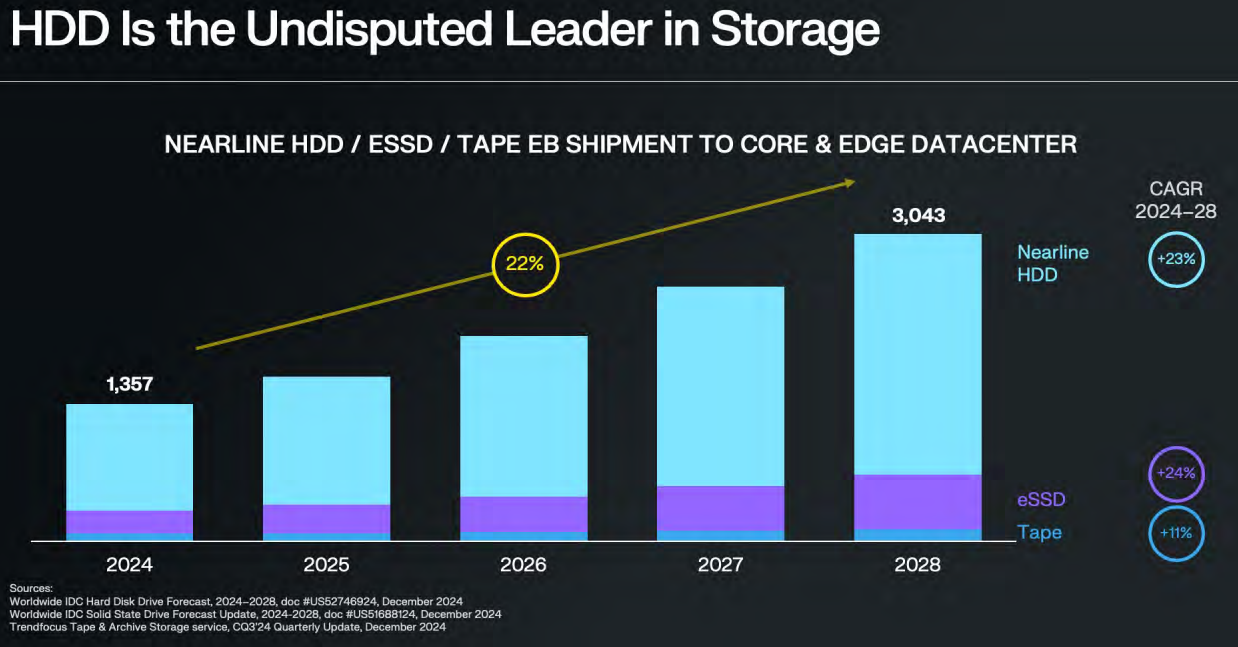
AI has not contributed much to growth but will in the next couple of years.
In the hard drive business, competition muted given its an oligopoly market with Seagate Technologies (STX).
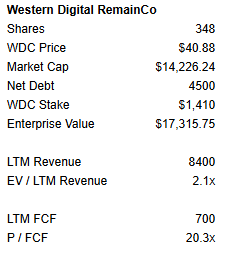
Seagate trades at 2.8x LTM revenue so Western Digital RemainCo has room for multiple expansion. The company is planning to return 100% of excess FCF to shareholders via dividends and share repurchases.
Assuming WDC RemainCo should trade inline with STX, it’s worth $58, representing 40% upside.
CompoSecure (CMPO) spun off Resolute Holdings (RHLD) on February 28, 2025.
Resolute Holdings will provide CompoSecure with services including oversight of capital allocation strategy, operational practices, and mergers and acquisitions (M&A) sourcing and execution.
Essentially, CompoSecure is spinning out a consulting team whose only customer is CompoSecure. The spin-off will be funded by a quarterly management fee funded by CompoSecure Holdings. The management fee is calculated as 2.5% of the trailing twelve month Adjusted EBITDA each quarter.
Resolute Holdings has been very volatile in when issued and regular way trading.
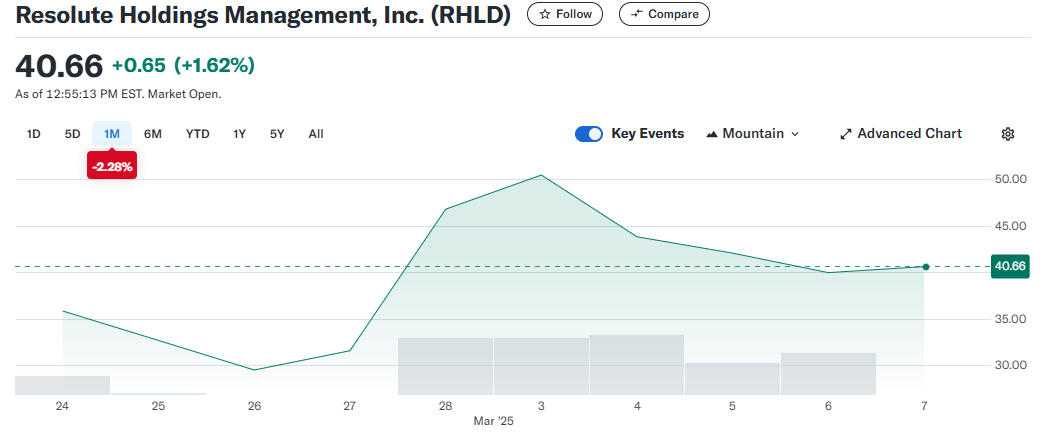
Resolute Holdings is currently trading at a market cap of $344MM.
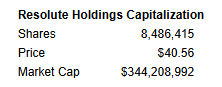
At this valuation, I’m not interested in buying the stock.
What’s the bull case?
David Cote has grand M&A ambitions for CMPO and Resolute Holdings will benefit directly from each acquisition. Resolute Holdings views itself more as an alternative asset manager. The alternative asset management industry trades as high as 30x earnings (BX), a significant premium to CMPO.
In talking to investor relations, I learned that CMPO has very significant M&A aspirations. The scope is “specialty manufacturing” which is quite broad. Looking out 5 years, I could see CMPO generating a billion in EBITDA in which case, Resolute Holdings would be generating ~$100MM in revenue and $88MM to $85MM in EBITDA (assuming expenses stay flat at $12MM to $15MM.
So assuming a 25x EBITDA multiple (because it’s basically an alternative asset manager), I could see a $2BN EV. So significant upside potential. But I don’t know if I would want to pay a $344MM market cap/EV today for it.
Imminent Spin-offs
On February 24, 2025, Lions Gate Entertainment (LGFA/LGFB) filed its latest proxy related to the spin-off its 87.5% stake in Lionsgate Studios (LION) in early Q2. You can read it here.
The spin-off is expected to take place by the end of April according to the last earnings call in February:
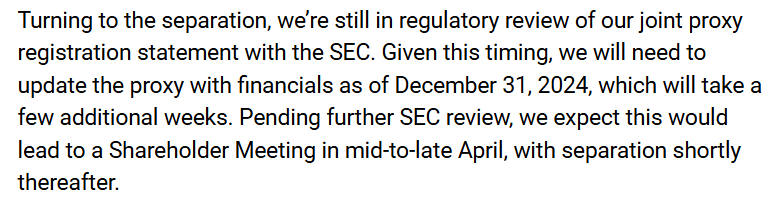
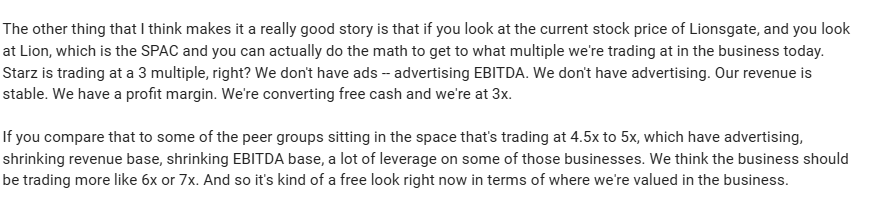
After the spin-off, LGF RemainCo will own Starz. LGF has a market cap of $2.2BN. Its 87% stake in LION is worth $2.1BN. Counting LION’s film obligation loans as debt, it is trading at 15.2x 2026 EBITDA. Historically, studio acquisitions have taken place at 16x (or higher) EBITDA. At 16x EBITDA, LION is worth $10.
The bull case for buying LGFA is you could buy the stock today for $9.97. By the end of April, you will receive 1.12 shares of LION (per share of LFG) which at 16x EBITDA are worth $10. You will also own the RemainCo (Starz). Assuming Starz is worth 5x EBITDA, RemainCo is worth ~$1.56 per share. So you pay $9.97 today and receive $12.06 in value ($10.50 in LION value [$10 * 1.05] and $1.56 in LFG RemainCo [Starz] value).
Here’s some good commentary on where Starz management thinks the business should trade:
Spin-off Links
VIC: Hoclim (must create free account to read)
- Good write up on upcoming spin-off
- My favorite ideas + 20 others from subscribers
Recommendations Updates
- IDT. IDT reported Q2 fiscal 2025 results on March 6th. It was another excellent quarter. Gross profit increased 16%. Income from operations increased 77%. GAAP net income increased 40% to $0.80. IDT increased its quarterly dividend by 20% to 6 cents per quarter. IDT repurchased 179,338 shares of Class B common stock in market transactions during 2Q25 for $8.5 million at an average share price of $47.59. All in all, a solid quarter and the investment case remains on track. The stock is only trading at 15x annualized earnings.
Spin-off Calendar
Upcoming Spin-off Calendar | Completed Spin-off Calendar
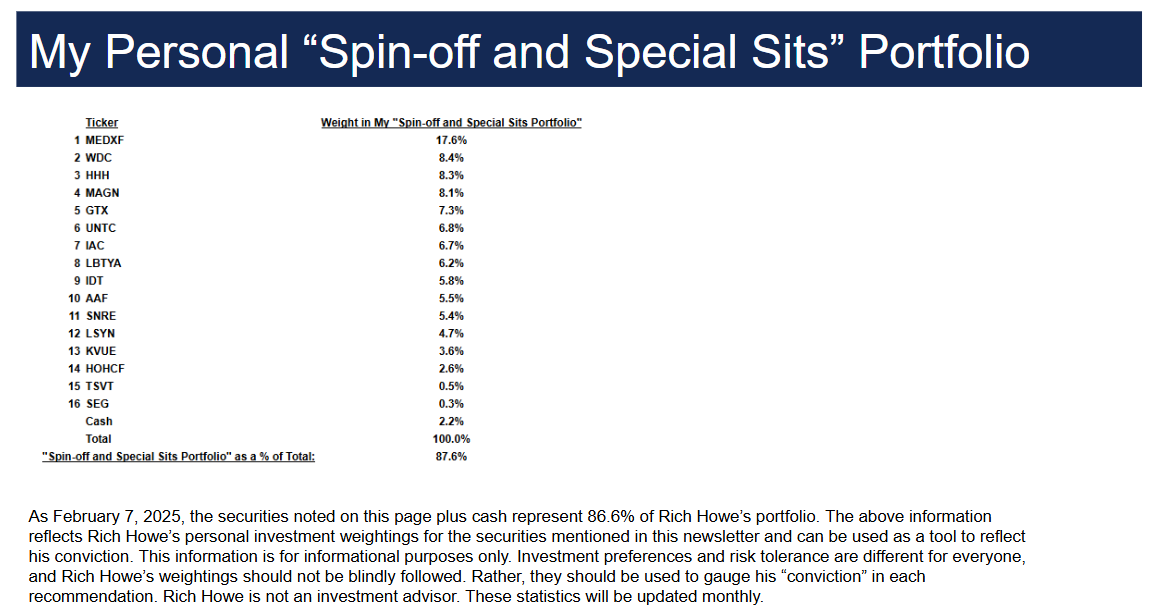
Current Positioning
(updated once a month)
Hope you had a great week!
Rich
Disclaimer:
Rich Howe, owner of Stock Spin-off Investing (“SSOI”), currently is long LSYN, IDT, MEDXF, GTX, AAF, IAC, UNTC, TSVT, KVUE, HGHAF, HHH, SEG, WDC, and MAGN. All expressions of opinion are subject to change without notice. This email is provided for informational purposes. Please do your own due diligence and consult with an investment adviser before buying any stock mentioned on www.stockspinoffinvesting.com.’
Leave A Comment