

Spin-off Links – March 2025
So far in 2025, there have been 5 new US spin-off announcements. Meanwhile 3 new spin-offs have started trading.
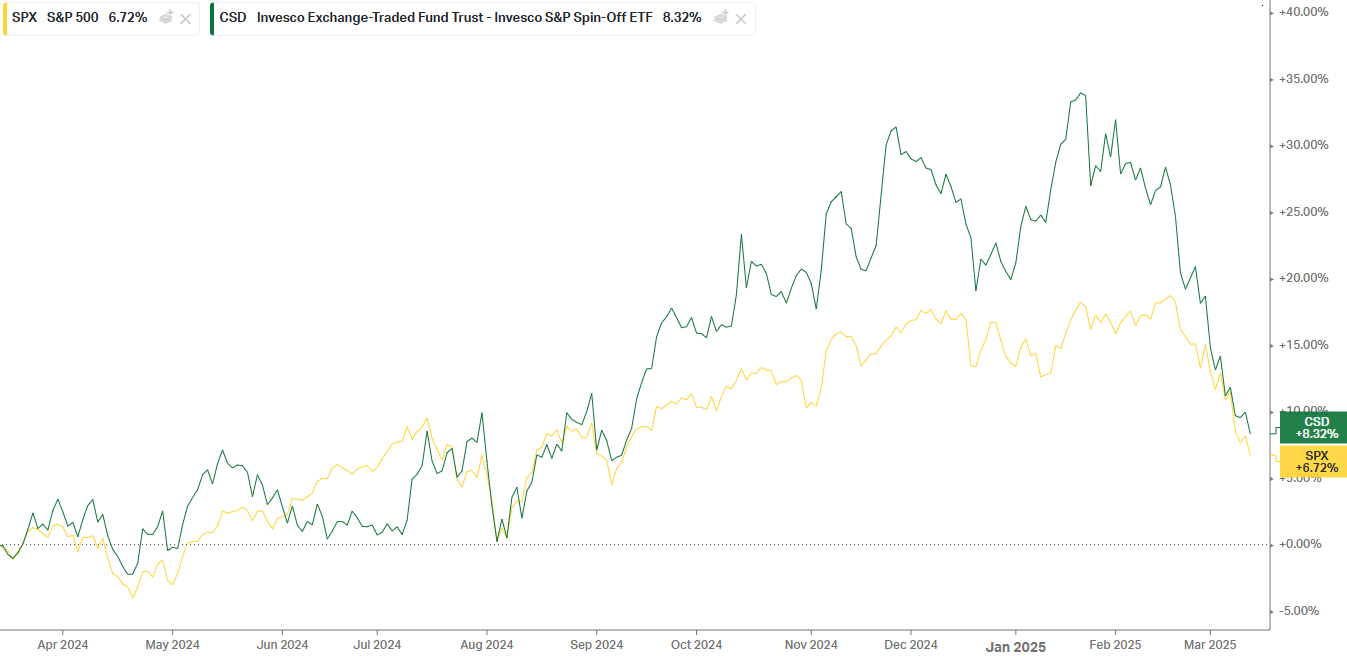
Spin-off stock performance was strong in 2024, but performance has turned over a bit in the last month.
Without further ado, let’s move on to the latest spin-off news….
New Spin-off Announcements
On February 6, 2025, Honeywell International (HON) announced its plans to separate into three independent public entities:
- Automation (49% of revenue): This segment will concentrate on developing advanced automation technologies.
- Aerospace (41% of revenue): Dedicated to aerospace technologies, this division will handle Honeywell’s existing aerospace operations.
- Advanced Materials (10% of revenue): This unit will specialize in advanced materials, continuing the company’s work in this area.
The spin-off of the Advanced Materials business is expected to be completed by late 2025 or early 2026, while the separations of the Automation and Aerospace businesses are projected for the second half of 2026.
The announcement follows pressure from Elliott Management. Here is the letter that Elliott published in November 2024.
Elliott Management believes HON is worth $330 to $383 per share.
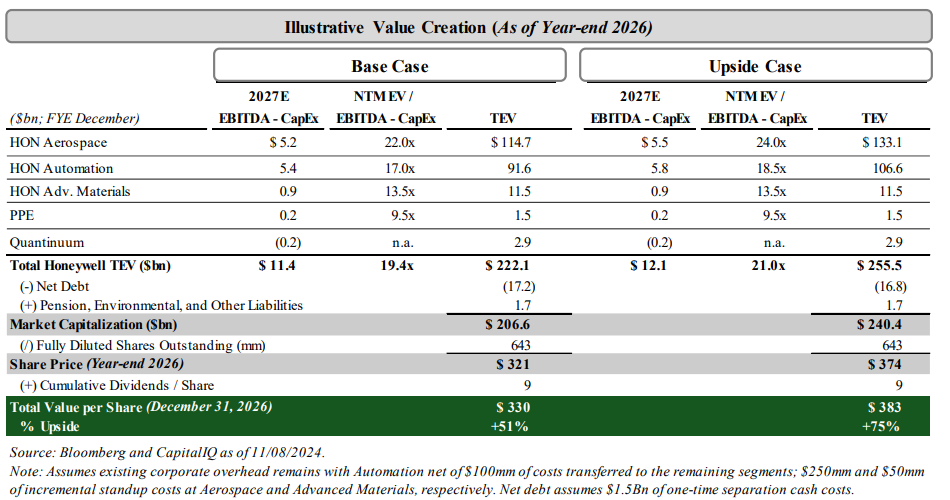
Barclays analysts have estimated a SOTP valuation of approximately $270 per share. Tony Bancroft, a portfolio manager at Gabelli Funds, suggested that the aerospace and automation businesses could be valued at $104 billion and $94 billion, respectively. However, he cautioned that it might take time for the market to recognize this value.
I think a breakup makes sense and will unlock value. However, this will take almost two years to play out and a lot could change during that time frame. The Advanced Materials spin-off will happen in 2025 but represents a relatively small portion of the value creation unlock.
The Middleby Corporation (MIDD) announced its plan to spin off its food processing business on February 25, 2025. This strategic move aims to allow Middleby to concentrate on its core commercial foodservice and residential kitchen equipment sectors, while enabling the new entity to focus exclusively on food processing operations.

The spin-off is expected to be executed as a tax-free transaction, with completion anticipated by early 2026. The newly formed company will specialize in equipment and technologies for industrial protein, bakery, and snack processors. Post-separation, Middleby will continue to focus on its commercial and residential kitchen equipment businesses, pursuing growth through mergers and acquisitions.
The announcement was made after Ed Garden, founder of Garden Investments, established a 5% stake in the company and advocated for change.
MIDD trades at 11x forward EBITDA and 15x forward earnings. This transaction should unlock value as the spin-off, with higher margins and faster growth, should trade at a higher multiple. Analyst Mircea Dobre from Baird believes Middleby is worth $227 on a sum-of-the-parts (SOTP) basis.
Recent Spin-offs
Western Digital (WDC) spun off is NAND flash business, Sandisk (SNDK), on February 24, 2024.Sandisk opened regular-way trading $52 and has since declined to $48.44. At Sandisk’s current price, it is trading at 1.0x revenue.
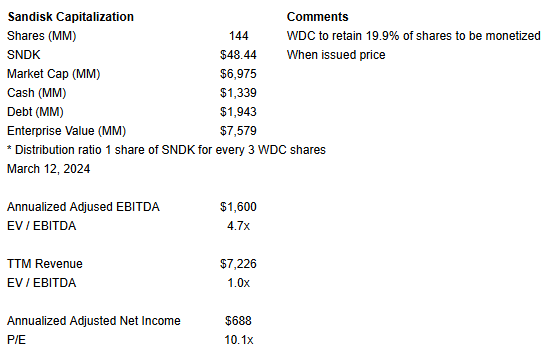
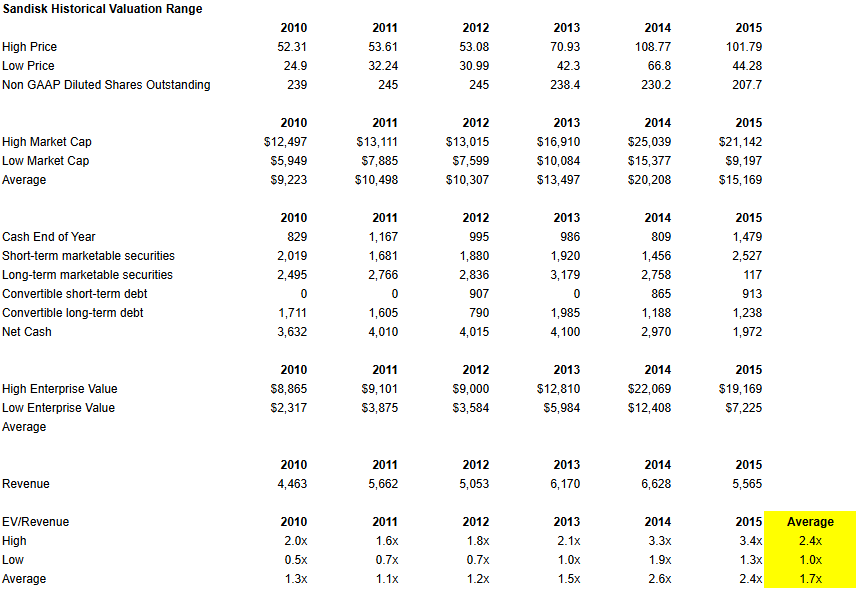
This valuation looks cheap relative to Kioxia (Sandisk’s JV partner) at 1.4x revenue and Sandisk’s historical valuation range (1x to 2.7x revenue) the last time it was a public company.
Western Digital RemainCo looks like a compelling story. It’s benefiting from secular tailwinds of increased data storage needs.

AI has not contributed much to growth but will in the next couple of years.
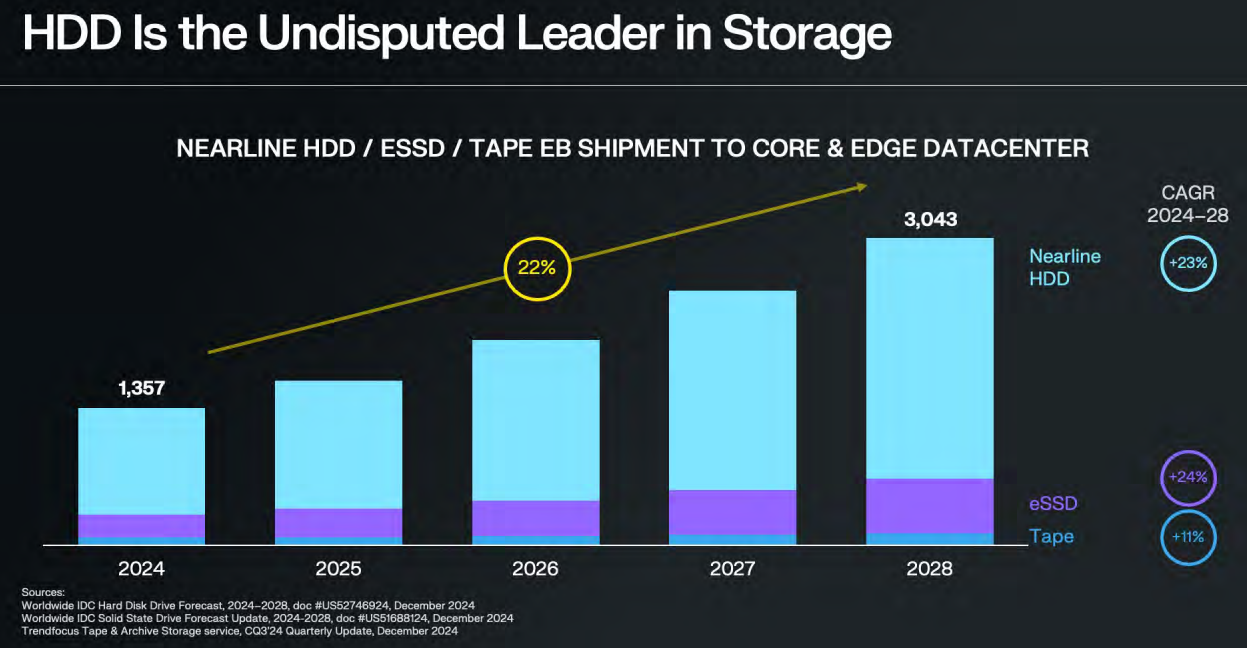
In the hard drive business, competition muted given its an oligopoly market with Seagate Technologies (STX).
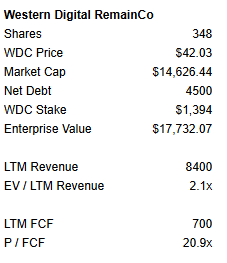
Seagate (STX) trades at 2.8x LTM revenue so Western Digital RemainCo has room for multiple expansion. The company is planning to return 100% of excess FCF to shareholders via dividends and share repurchases.
Assuming WDC RemainCo should trade inline with STX, it’s worth $58, representing 40% upside.
CompoSecure (CMPO) spun off Resolute Holdings (RHLD) on February 28, 2025.
Resolute Holdings will provide CompoSecure with services including oversight of capital allocation strategy, operational practices, and mergers and acquisitions (M&A) sourcing and execution.
Essentially, CompoSecure is spinning out a consulting team whose only customer is CompoSecure. The spin-off will be funded by a quarterly management fee funded by CompoSecure Holdings. The management fee is calculated as 2.5% of the trailing twelve month Adjusted EBITDA each quarter.
Resolute Holdings has been very volatile in when issued and regular way trading.
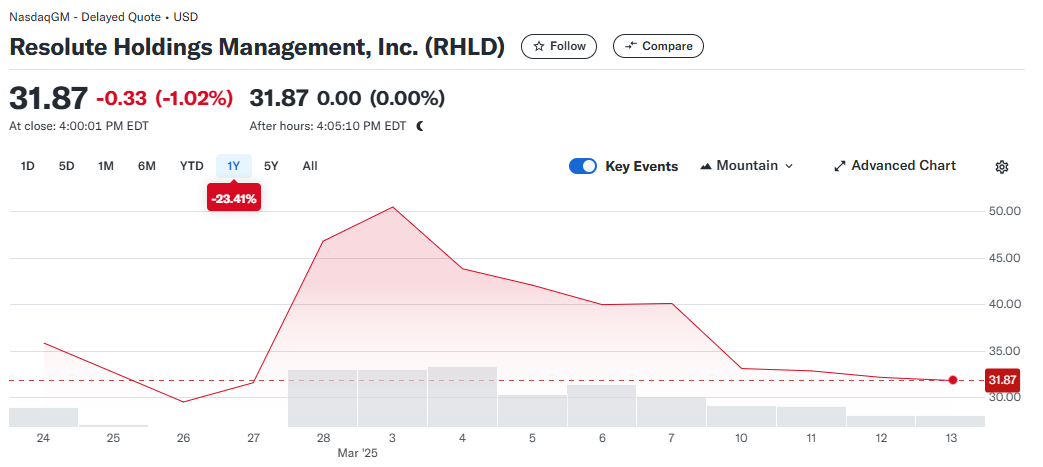
Resolute Holdings is currently trading at a market cap of $270MM.
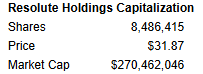
At this valuation, I’m not interested in buying the stock.
What’s the bull case?
David Cote has grand M&A ambitions for CMPO and Resolute Holdings will benefit directly from each acquisition. Resolute Holdings views itself more as an alternative asset manager. The alternative asset management industry trades as high as 30x earnings (BX), a significant premium to CMPO.
In talking to investor relations, I learned that CMPO has very significant M&A aspirations. The scope is “specialty manufacturing” which is quite broad. Looking out 5 years, I could see CMPO generating a billion in EBITDA in which case, Resolute Holdings would be generating ~$100MM in revenue and $88MM to $85MM in EBITDA (assuming expenses stay flat at $12MM to $15MM).
So assuming a 25x EBITDA multiple (because it’s basically an alternative asset manager), I could see a $2BN EV. So significant upside potential if you believe CompoSecure is going to grow massively through acquisitions.
Lennar Corporation (LEN) spun off 80% of its subsidiary, Millrose Properties, Inc (MRP), on February 7, 2025. Lennar shareholders received one share of Millrose Class A or Class B common stock for every two shares of Lennar Class A or Class B common stock
Lennar contributed ~$5.5 billion in undeveloped, partially developed, and some fully developed land assets, along with up to $1 billion in cash, to Millrose. Millrose will operate as an independent entity, acquiring and developing land to deliver finished homesites under land option contracts. Initially, it will serve Lennar but plans to engage with other homebuilders as well.
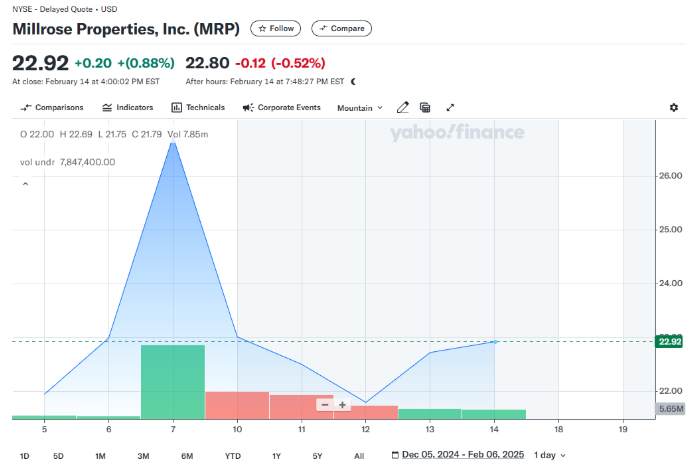
Millrose jumped right before it was added to the S&P 600 but has since sold off.
Lennar will pay Millrose option fees for the right to buy land on Millrose’s balance sheet.
This strategic move is part of Lennar’s ongoing shift toward an asset-light operating model, aiming to reduce financial risk and enhance returns by minimizing direct land ownership.
Millrose has a book value of $5.9BN and 135MM shares outstanding. It is trading at an expected dividend yield of 10.3% based on my estimates.
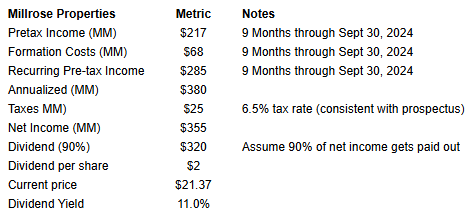
I think Millrose is appropriately valued. If it were to trade off into the mid-teens, I think it would be an attractive buy based on its dividend yield.
Imminent Spin-offs
On February 24, 2025, Lions Gate Entertainment (LGFA/LGFB) filed its latest proxy related to the spin-off its 87.5% stake in Lionsgate Studios (LION) in early Q2. You can read it here.
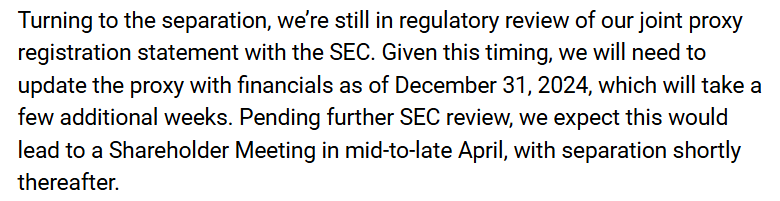
The spin-off is expected to take place by the end of April according to the last earnings call in February:
After the spin-off, LGF RemainCo will own Starz. LGF has a market cap of $2.0BN. Its 87% stake in LION is worth $1.9BN. Counting LION’s film obligation loans as debt, it is trading at 14.5x 2026 EBITDA. Historically, studio acquisitions have taken place at 16x (or higher) EBITDA. At 16x EBITDA, LION is worth $10.
The bull case for buying LGFA is you could buy the stock today for $9.15. By the end of April, you will receive 1.12 shares of LION (per share of LFG) which at 16x EBITDA are worth $10. You will also own the RemainCo (Starz). Assuming Starz is worth 5x EBITDA, RemainCo is worth ~$1.56 per share. So you pay $9.15 today and receive $12.76 in value ($11.20 in LION value [$10 * 1.12] and $1.56 in LFG RemainCo [Starz] value).
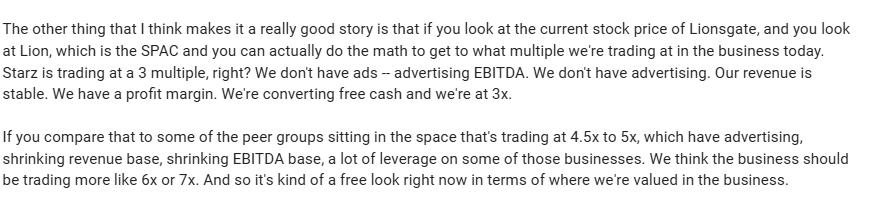
Here’s some good commentary on where Starz management thinks the business should trade:
Spin-off Links
Seeking Alpha: Magnera: An Unknown Company With Significant Upside Potential
- Articulates the investment thesis for Magnera well
Honeywell to break up in latest corporate split after pressure from activist investor
- Honeywell is hoping for the success that General Electric had with its breakup.
Podcast: Palm Harbor Capital on International Gaming Technology (IGT)
- Extremely thorough breakdown.
AI for Research: A Practical Guide for Analysts
– Good overview of AI tools that can help with investment research
Podcast: Paul Singer: Activist Investing, Market Risks and Avoiding Losses
– This was excellent.
Podcast: Bill Ackman on Investing, Politics, and Howard Hughes
– Don’t agree with Ackman’s HHH proposal. But I enjoyed the interview.
WSJ: Activist Elliott Ratchets Up Pressure on Phillips 66 With Over $2.5 Billion Stake
– Elliott is agitating for a break-up

Hello – thanks for your analysis here on the Lennar Corporation ($LEN) spin of its subsidiary Millrose Properties ($MRP). I would be interested in people’s opinion/firsthand perspective of $MRP’s management team. Do you know of any other forums/websites that discuss REITs (such as $MRP)? I looked at Seeking Alpha and Yahoo Finance’s Community…and no one has commented on this stock $MRP or its management quality. Thanks!