

Weekly Update (MCK, LBTYA, SNRE, AMRZ)
May 17, 2025
Before I dig into my regular update, I want to share one chart that caught my eye this week.
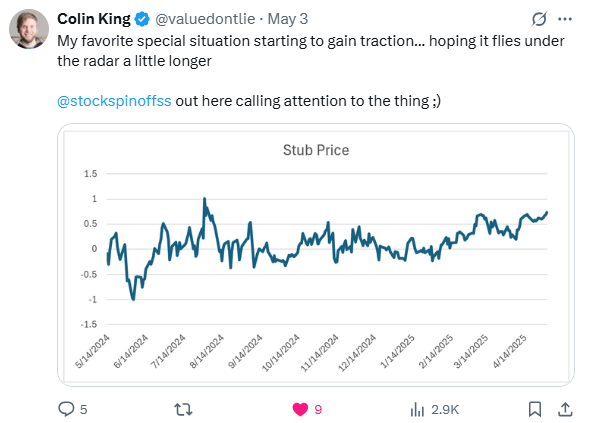
Colin King did a nice job modeling out Lionsgate RemainCo Stub / Starz valuation from last May to now. Interesting to see that at one point it was trading at a negative $1 price.
Weekly Update
If you haven’t already, consider joining our discord channel (included with your paid subscription):
Join Discord Channel (you must create a free discord account to join)
It’s basically a chat room where we discuss what’s going on in the special situation market:
Here are a few things we discussed this week:
1. More insider buying at Magnera
2. Liberty up on news that VO2M might be monetized
Recently Announced Spin-offs
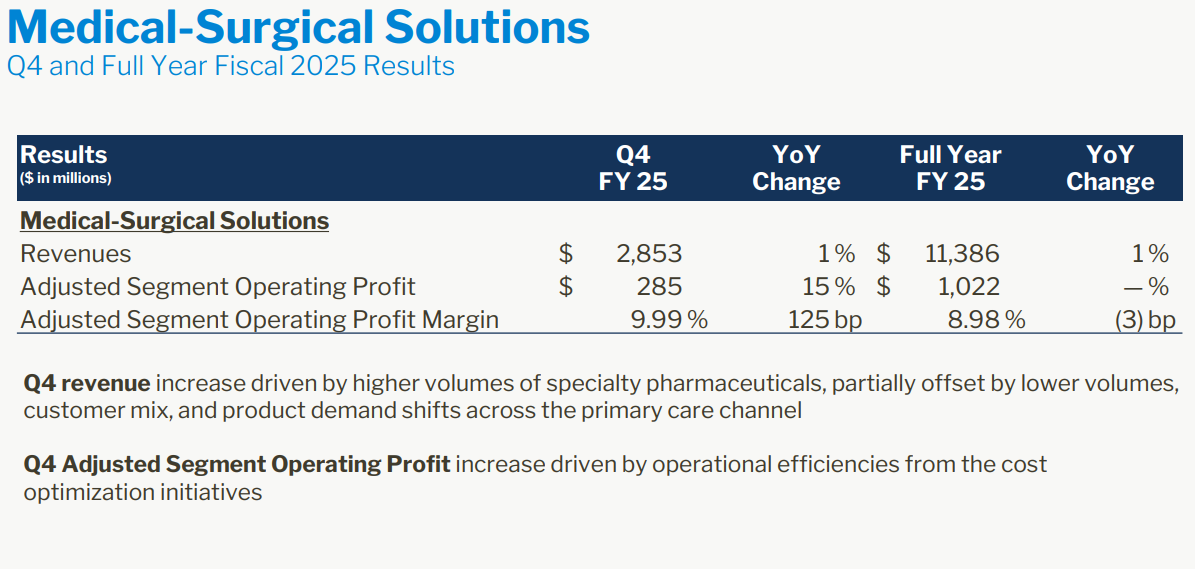
McKesson Corporation announced on May 8, 2025, its intention to spin off its Medical-Surgical Solutions segment into an independent company, referred to as “NewCo” for now.
The Medical Solutions business generates $11.4BN of revenue (3% of total) and $1BN of operating profit (18% of total).
The spin-off will allow McKesson to sharpen its strategic focus on higher-growth areas such as oncology and biopharma solutions.
The Medical-Surgical Solutions business generates high margins but has a slower growth outlook. It grew just 1% in the past year versus the entire company which grew 16%.
Given NewCo’s profile (high-single-digit adjusted operating margin, stable cash flows, and presumably mid-single-digit growth outlook), a reasonable valuation range might be around 0.8× – 1.0× sales or roughly 9× – 11× EBITDA. This is in line with medtech and distribution peers. This would imply an enterprise value of $10BN to $12BN, significantly below McKesson’s current EV of $92BN. Given the expected market cap and growth outlooks differences between the parent and the spin-off, we might see indiscriminate selling pressure once the spin-off takes place.
Timing of the transaction hasn’t been finalized, but I expect it to take at least a year.
Imminent Spin-off
Holcim is spinning off its North American construction materials and solutions business into a standalone company, to be named Amrize (AMRZ), with a planned listing on the NYSE and SIX by mid-2025
This week shareholders approved the spin-off which will take place in June 2025.
Amrize will become a pure-play “building solutions” leader in the US and Canada (cement, aggregates, ready-mix, roofing and insulation) with ~19,000 employees and over 1,000 sites.
In 2024 the NA business generated $11.7B revenue and $3.2B Adj. EBITDA (27% margin) – 13–16% CAGRs since 2021
Management targets robust mid-term growth (CAGR 5–8% sales, 8–11% EBITDA through 2028).
Holcim initially guided a $30 billion valuation for Amrize when the spin-off was announced though outside analysts suggest the equity could be worth substantially more (up to ~$45–50B or higher) under favorable assumptions
Amrize’s peers include US aggregates/concrete leaders (Martin Marietta, Vulcan, Eagle Materials), large global cement firms (CRH, LafargeHolcim pre-spin, Saint-Gobain, Buzzi Unicem), and building-products companies. Recent trading multiples for such peers generally lie in the 10–15× EV/EBITDA range.
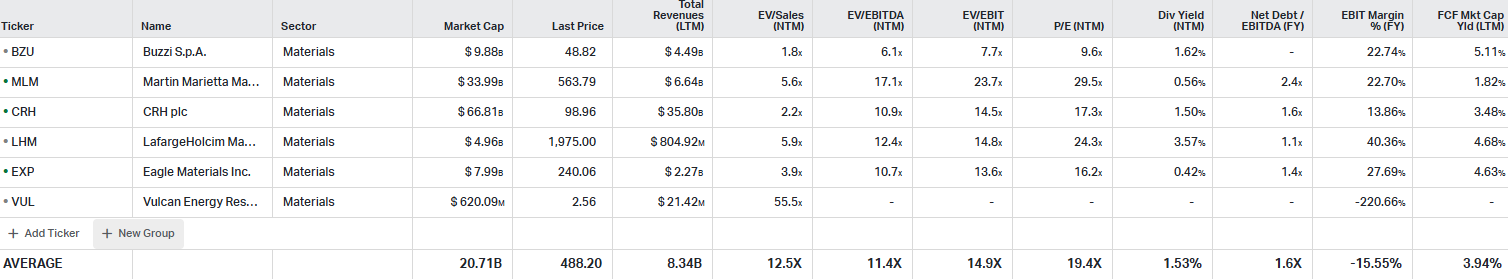
Applying these to Amrize’s scale: with mid-cycle EBITDA of roughly $3.5–4.5 B (FY2025-28 guidance), a 10–12× EV/EBITDA multiple implies an Enterprise Value of $35–54 B. For example, a 12× multiple on 2028E EBITDA ($4.6 B) gives EV ≈ $55 B. Subtracting net debt (~$8–9 B) yields equity value ~$46–47 B. Even at the lower end (10× on 8% growth scenario), Amrize EV would be ~$46 B (equity ≈$38 B). These comparisons suggest Amrize could trade at a substantial premium to Holcim’s current 8× EBITDA multiple.
Spin-off Links
McKesson: Spin-Off Of Medical-Surgical Solutions Is A Positive, Strong Buy
- Positive coverage of MCK’s most recent spin-off news.
Variety: Lionsgate and Starz Are Officially Now Two Separate Companies
- Describes the motivations for the separation.
ABB evaluating sale of robotics unit as alternative to spin – Bloomberg
- A sale would be disappointing to me as this looks like an attractive business
Telefonica Is Said to Draw Up Plans for Liberty’s VMO2 Stake
- This would be a positive for Liberty and would unlock value.
Holcim shareholders approve spinoff, grumble over chairman’s pay
- Spin-off would be completed by the end of June
Recommendations Updates
(1) Sunrise Communications
Sunrise went ex for its dividend on May 16, 2026. I’m still waiting for the confirmation of the dividend amount, but my estimate is $3.96. The stock adjusted down by $4.34 and is now trading at ~$49.56. At that price, the stock is trading at a dividend yield of 8%. My plan was to sell the stock if it ran into the high $50 range / low $60 range, but I’m likely going to hang on. The business is stable, and I’m happy to wait around and collect an 8% dividend.
2) Liberty Global
This week, Bloomberg reported that Telefonica is interested in buying Liberty’s VMO2 stake.
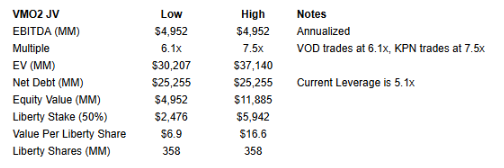
Liberty responded very well to the news. And given the potential value of VMO2 (my estimate is $6.90 per Liberty share on the low end), the share price reaction makes sense.
Telefonica is heavily indebted, and so I don’t know how the deal would work, but Liberty clearly seems to be open to making deals to unlock shareholder value. Whether this deal proceeds or not, I’m confident Liberty will be able to monetize its assets to unlock shareholder value.
Spin-off Calendar
Upcoming Spin-off Calendar | Completed Spin-off Calendar
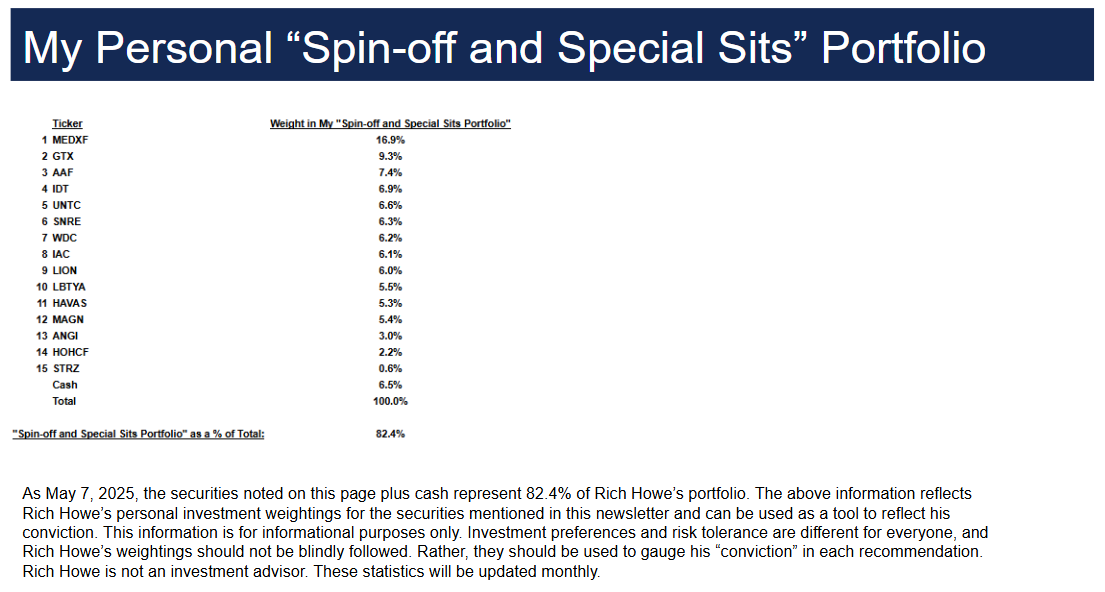
Current Positioning
(updated once a month)
Hope you had a great week!
Rich
Disclaimer:
Rich Howe, owner of Stock Spin-off Investing (“SSOI”), currently is long IDT, MEDXF, GTX, AAF, IAC, UNTC, HGHAF, WDC, MAGN, HAVAS, and LION, and STRZ. All expressions of opinion are subject to change without notice. This email is provided for informational purposes. Please do your own due diligence and consult with an investment adviser before buying any stock mentioned on www.stockspinoffinvesting.com.’
Leave A Comment