

Weekly Update (WBD, STRZ, MODG)
June 14, 2025
Before I get into my regular update, I want to flag one post on X that caught my eye:
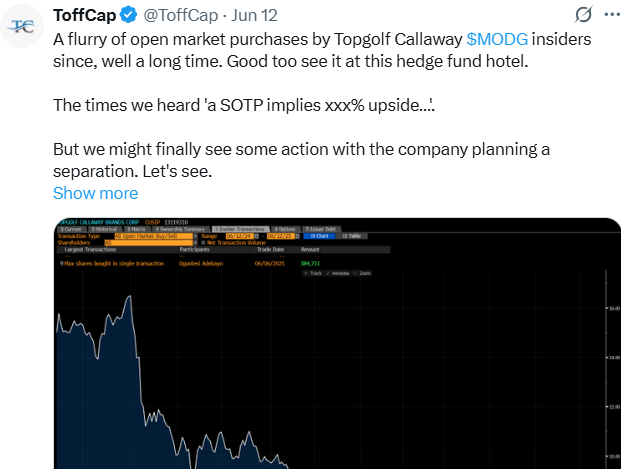
My initial take was that this transaction would not unlock much value.
But MODG’s stock has come down since the time of the announcement.
I think it looks more promising today.
MODG‘s best peer, Acushnet (GOLF) trades at 2.1x LTM revenue. Assuming Callaway trades at the same revenue multiple, it will be worth an enterprise value of $5.25BN. MODG‘s current EV according to Koyfin is $5.55BN, implying that Topgolf is worth ~$300MM. This looks attractive given TopGolf was acquired for $2.66BN and generates $1.8BN of revenue.
Topgolf has struggled of late, but the situation looks interesting.
The spin-off is expected to take place by the end of 2025.
Weekly Update
If you haven’t already, consider joining our discord channel (included with your paid subscription):
Join Discord Channel (you must create a free discord account to join)
It’s basically a chat room where we discuss what’s going on in the special situation market:
Here are a few things we discussed this week:
2. Discussion of Tetragon Financial Group
Recently Announced Spin-offs
Warner Bros. Discovery (WBD) announced on June 9, 2025, its plan to split into two independent, publicly traded companies by mid-2026.
Global Networks will be the entity that is spun-off. It will consist of legacy cable TV and digital networks, such as:
- CNN, TBS, TNT (including TNT Sports)
- Discovery Channel, TLC, HGTV, and other Discovery cable channels
- Discovery+
- Bleacher Report and free‑to‑air networks in Europe
CFO Gunnar Wiedenfels will become CEO of this spun‑off entity.

The RemainCo will be WBD Streaming and Studios.
This division will encompass WBD’s premium content and streaming assets, including:
- HBO and HBO Max
- Warner Bros. Television and Motion Picture Group
- DC Studios
- Warner Bros. Games and related experiences
David Zaslav, the current CEO of WBD, will lead this entity, focusing on expanding its global streaming footprint and leveraging its rich content library.
Will this transaction unlock value?
I think so.
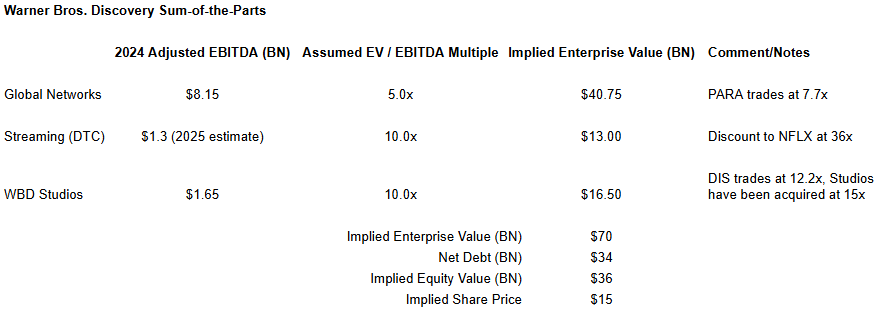
My preliminary SOTP suggests the stock is worth $15, ~50% above where the stock currently trades.
The transaction is expected to be completed be the middle of 2026.
Imminent Spin-offs
Holcim (HOLM) will spin off its North American construction materials and solutions business into a standalone company, to be named Amrize (AMRZ), on June 23.
Amrize will become a pure-play “building solutions” leader in the US and Canada (cement, aggregates, ready-mix, roofing and insulation) with ~19,000 employees and over 1,000 sites.
In 2024 the NA business generated $11.7B revenue and $3.2B Adj. EBITDA (27% margin) – 13–16% CAGRs since 2021
Management targets robust mid-term growth (CAGR 5–8% sales, 8–11% EBITDA through 2028).
Holcim initially guided a $30 billion valuation for Amrize when the spin-off was announced though outside analysts suggest the equity could be worth substantially more (up to ~$45–50B or higher) under favorable assumptions
Amrize’s peers include US aggregates/concrete leaders (Martin Marietta, Vulcan, Eagle Materials), large global cement firms (CRH, LafargeHolcim pre-spin, Saint-Gobain, Buzzi Unicem), and building-products companies. Recent trading multiples for such peers generally lie in the 10–15× EV/EBITDA range.
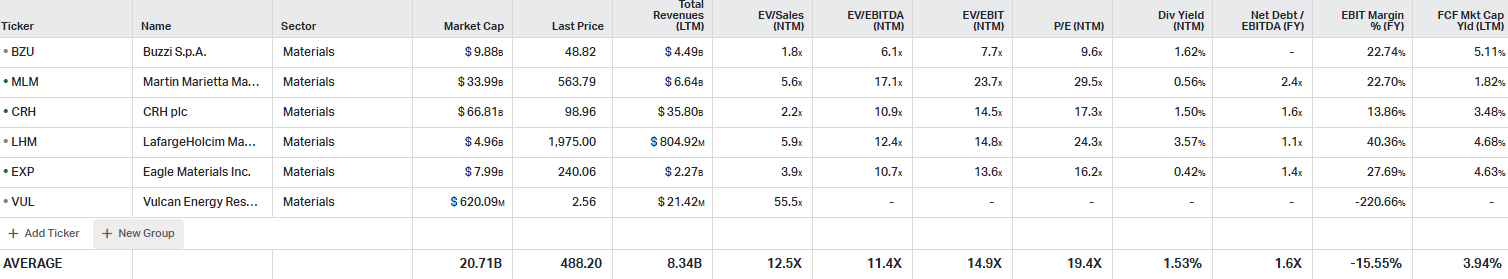
Applying these to Amrize’s scale: with mid-cycle EBITDA of roughly $3.5–4.5 B (FY2025-28 guidance), a 10–12× EV/EBITDA multiple implies an Enterprise Value of $35–54 B. For example, a 12× multiple on 2028E EBITDA ($4.6 B) gives EV ≈ $55 B. Subtracting net debt (~$8–9 B) yields equity value ~$46–47 B. Even at the lower end (10× on 8% growth scenario), Amrize EV would be ~$46 B (equity ≈$38 B). These comparisons suggest Amrize could trade at a substantial premium to Holcim’s current 8× EBITDA multiple.
Fortive (FTV) will spin off 100% of Ralliant on June 28, 2025. Shareholders will receive a share of RAL for 3 shares of FTV owned.
Ralliant will trade under the ticker RAL. When issued trading will begin on June 25th. Ralliant will host an investor day on June 10, 2025.
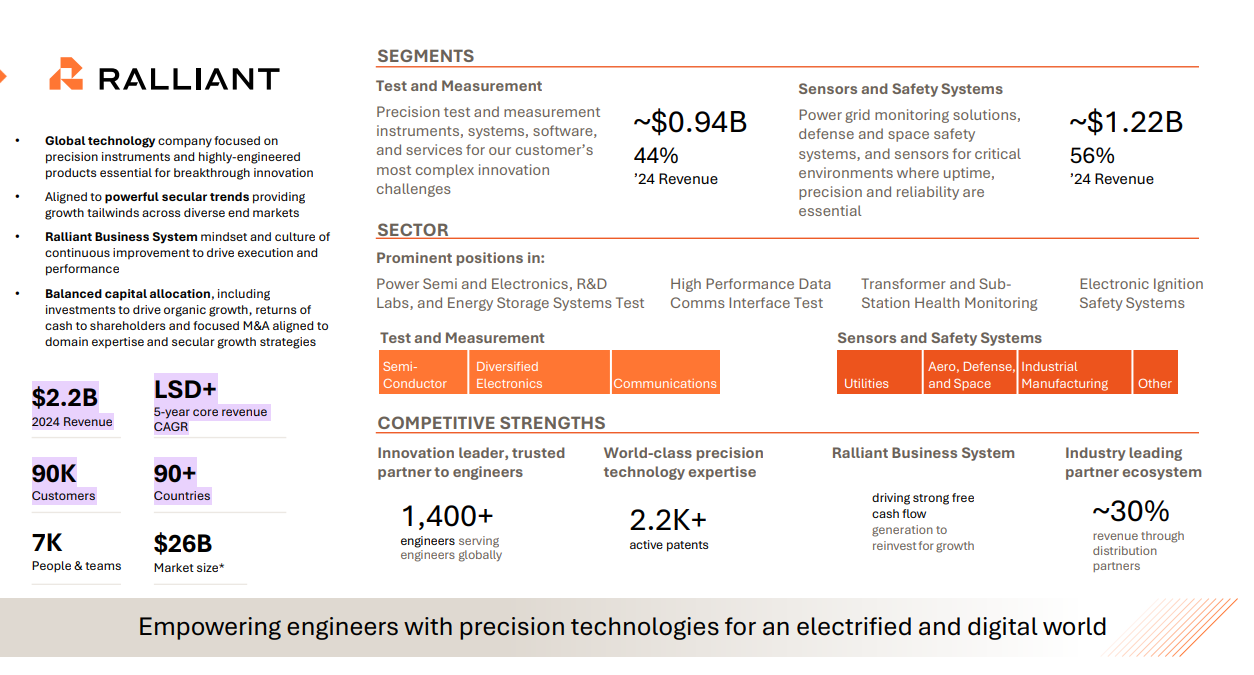
Ralliant (Precision Technologies) will be a $2.2B revenue company (2024) focused on Test & Measurement and Sensors & Safety Systems. Key segments: 56% of sales in Sensors & Safety (power‑grid monitors, defense, critical-environment sensors) and 44% in Test & Measurement (electronic instrumentation, systems, software). Ralliant’s 5‑year core revenue CAGR is “LSD+” and management highlights strong free cash conversion.
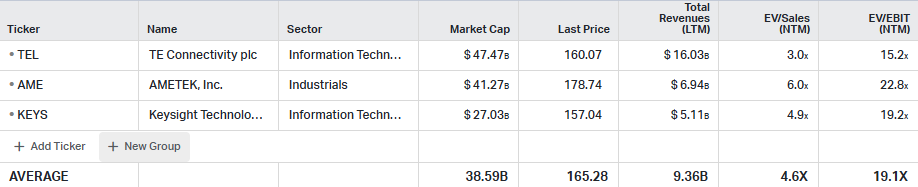
Ralliant comps trade at 4.6x revenue and 19.1x on an EV/EBIT.
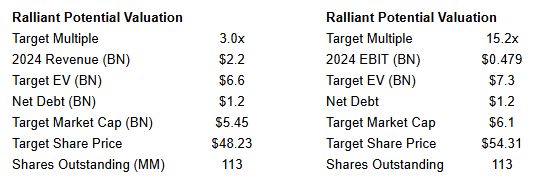
Assuming Ralliant should trade at the low end of its peer group given it’s a spin-off with limited public company history, it should trade at 3.0x revenue and 15.2x EBIT.
Assuming multiples, Ralliant should trade around $50 per share (or $17 per FTV/share as the spin-off ratio is 1 share of RAL for every 3 owned of FTV).
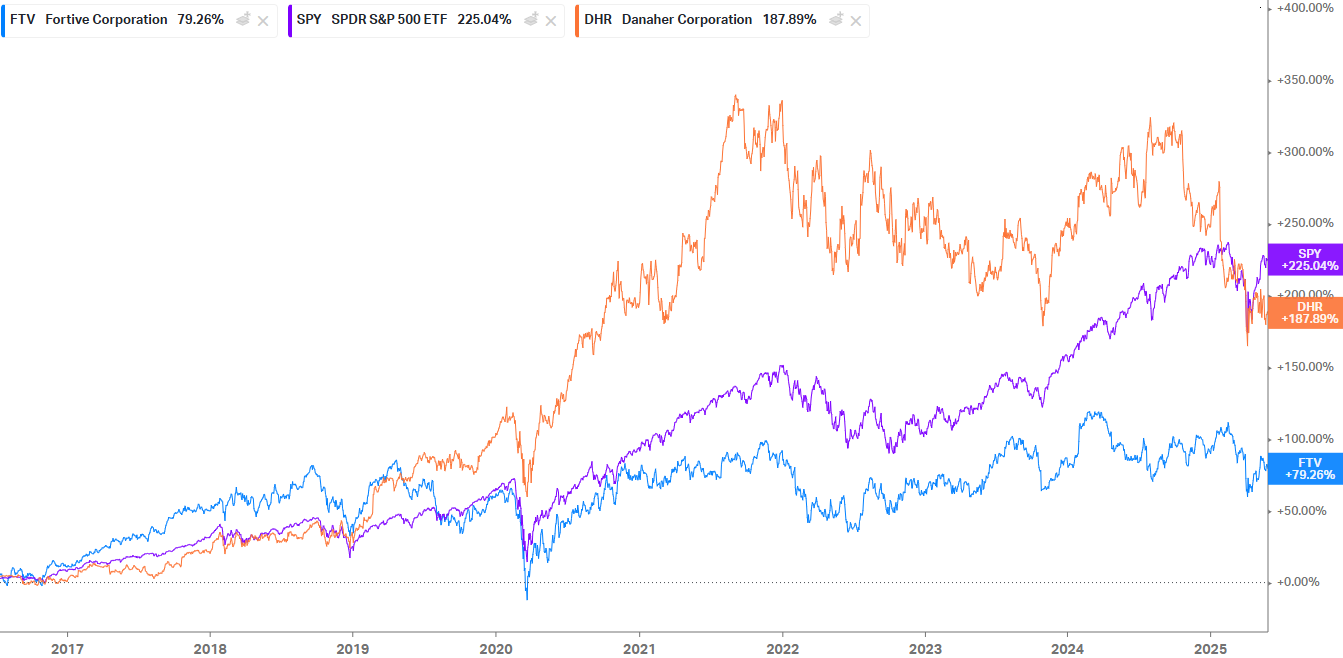
Fortive was itself a spin-off from Danaher (DHR) in 2016. Since the spin-off, Fortive has not performed especially well.
After the spin‑off, Fortive RemainCo will comprise the IOS and AHS segments (roughly 4.0–4.1B in 2024 revenue).
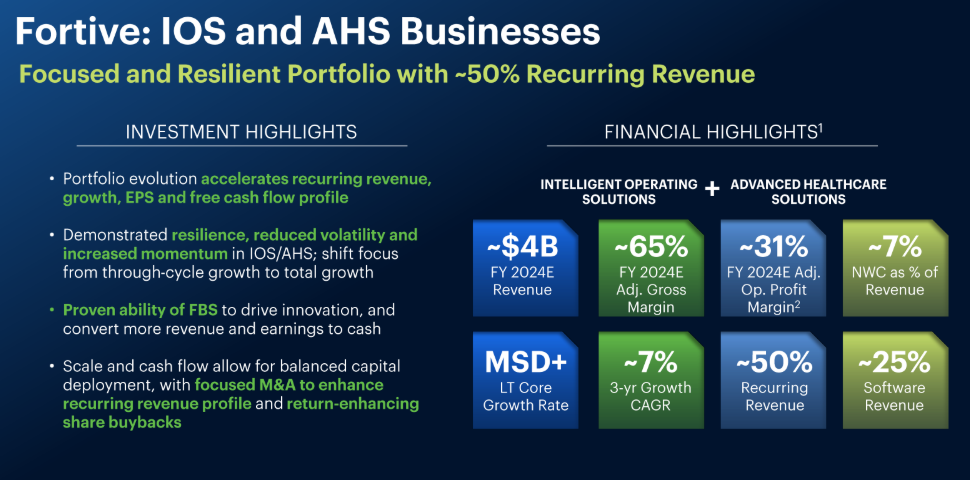
Potential comps include industrial automation and healthcare instruments (e.g. Rockwell Automation, Emerson, Honeywell, Agilent, Danaher).
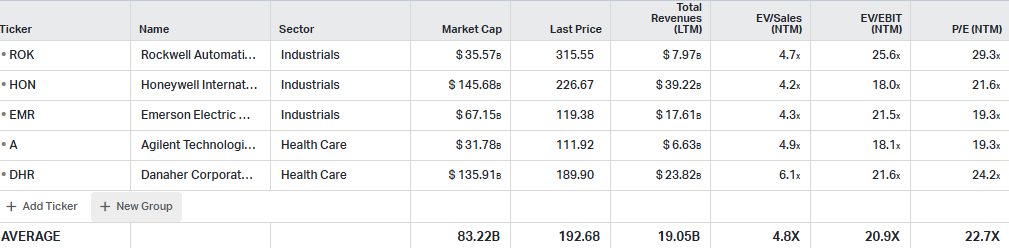
Assume Fortive RemainCo trades inline with peers (4.8x EV/Revenue), it should trade at ~$48/share.
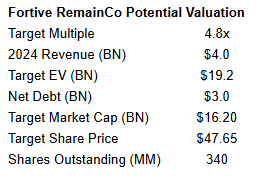
Adding the RemainCo to my spin-off valuation, and I get fair value of ~$65/share (below FTV’s current share price) suggesting this transaction does not create an obvious opportunity.
Spin-off Links
WBD Spin-Off: Quick Take on the Announcement
- A skeptical take on the WBD spin-off (I’m more optimistic).
VIC: News Corp (must create free account to access)
- Interesting SOTP angle with an underappreciated digital transformation.
Recommendations Updates
(1) Starz Entertainment
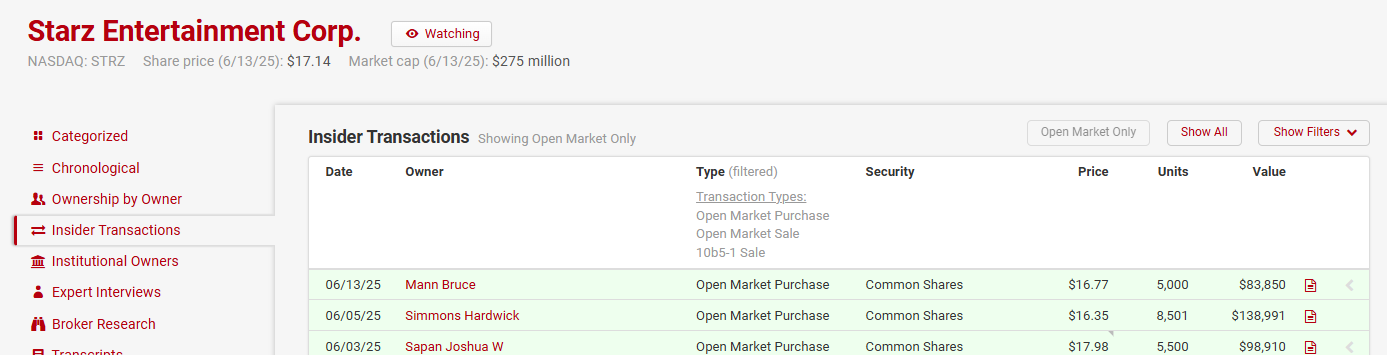
No big news, but we’ve seen some insider buying at STRZ over the past couple of weeks.
Spin-off Calendar
Upcoming Spin-off Calendar | Completed Spin-off Calendar
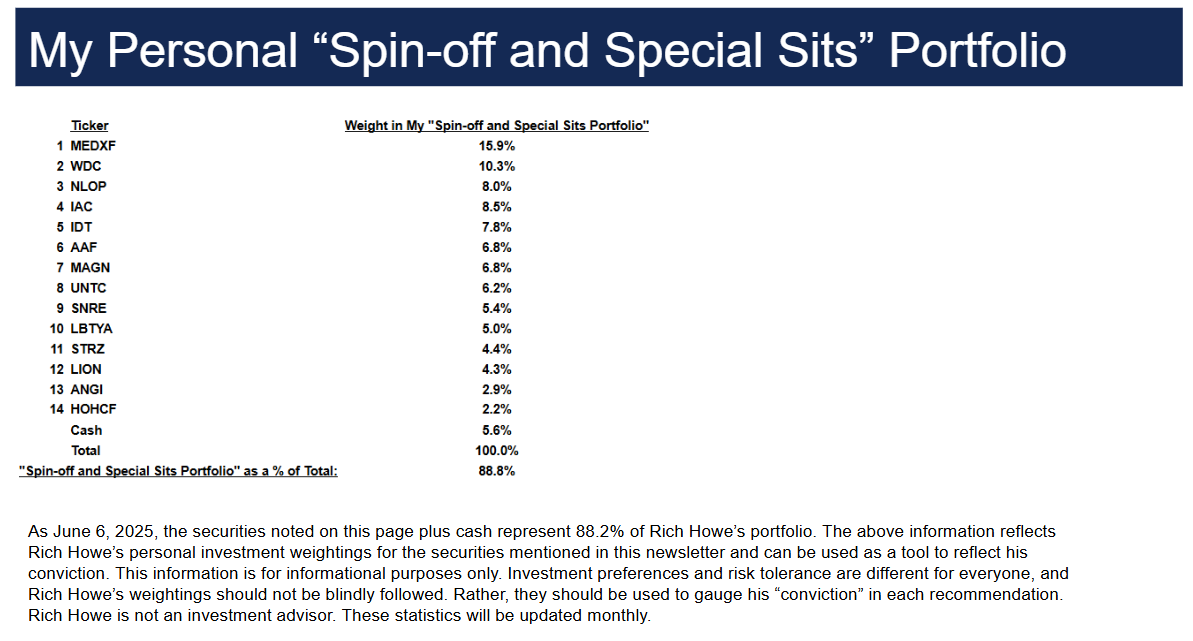
Current Positioning
(updated once a month)
Hope you had a great week!
Rich
Disclaimer:
Rich Howe, owner of Stock Spin-off Investing (“SSOI”), currently is long IDT, MEDXF, AAF, IAC, UNTC, HGHCF, WDC, MAGN, LION, STRZ, NLOP. All expressions of opinion are subject to change without notice. This email is provided for informational purposes. Please do your own due diligence and consult with an investment adviser before buying any stock mentioned on www.stockspinoffinvesting.com.’
Leave A Comment