

Weekly Update (3134, REZI, WDC, BRSL)
August 1, 2025
Our monthly call starts now!
You can use this link to join.
https://us06web.zoom.us/j/84543418525
Here’s what I plan to cover:
- Overview of new idea: Hamee Corp (TSE: 3134)
- Recent spin-off announcement: Resideo (REZI)
- Additional thoughts on GCI Liberty (GLIBK)
- Review of Airtel Africa’s (AAF) recent results.
- Review of Western Digital’s (WDC) recent results.
- Update on Brightstar Lottery (BRSL)
- Recommendation overview
- Answer your questions.
Alright, now on to my regular update
Weekly Update
If you haven’t already, consider joining our discord channel (included with your paid subscription):
Join Discord Channel (you must create a free discord account to join)
It’s basically a chat room where we discuss what’s going on in the special situation market:
Here are a few things we discussed this week:
- Additional discussion on interesting odd lot
- Strong results from BRSL
- Q&A for Hamee Corp (TSE: 3134) Investment Case
Recently Announced Spin-offs
Resideo Technologies (REZI) announced on July 30, 2025, that it plans to spin off its ADI Global Distribution business as a separate publicly traded company by the second half of 2026. The spin-off is intended to be tax-free for shareholders, resulting in two independent companies: Resideo (RemainCo) retaining the Products & Solutions segment, and ADI as a standalone distribution company.
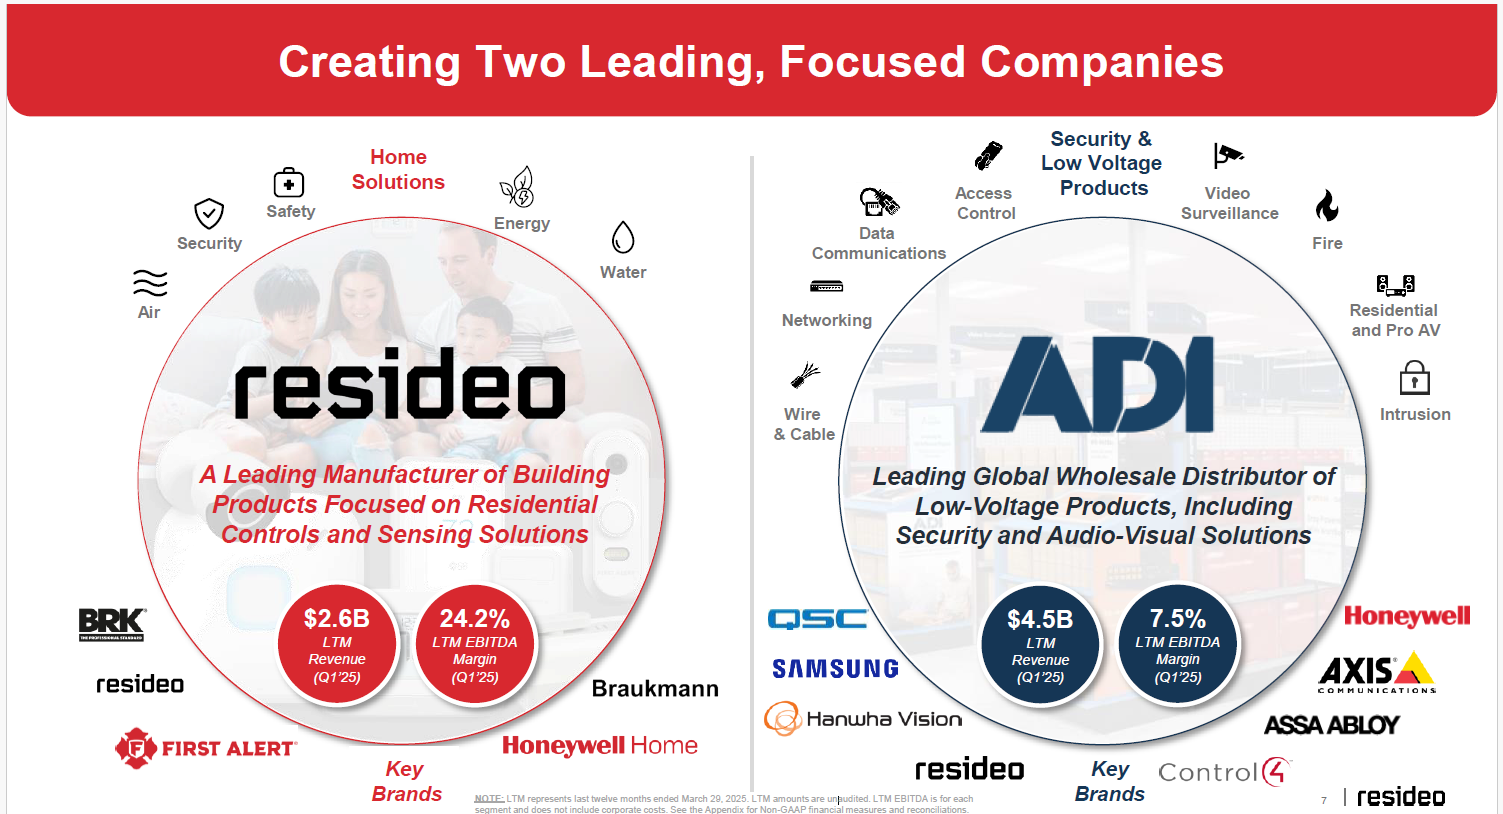
This strategic move, coupled with a one-time $1.59 billion payment to eliminate legacy Honeywell obligations, was greeted positively by the market – Resideo’s stock surged ~19% on the news.
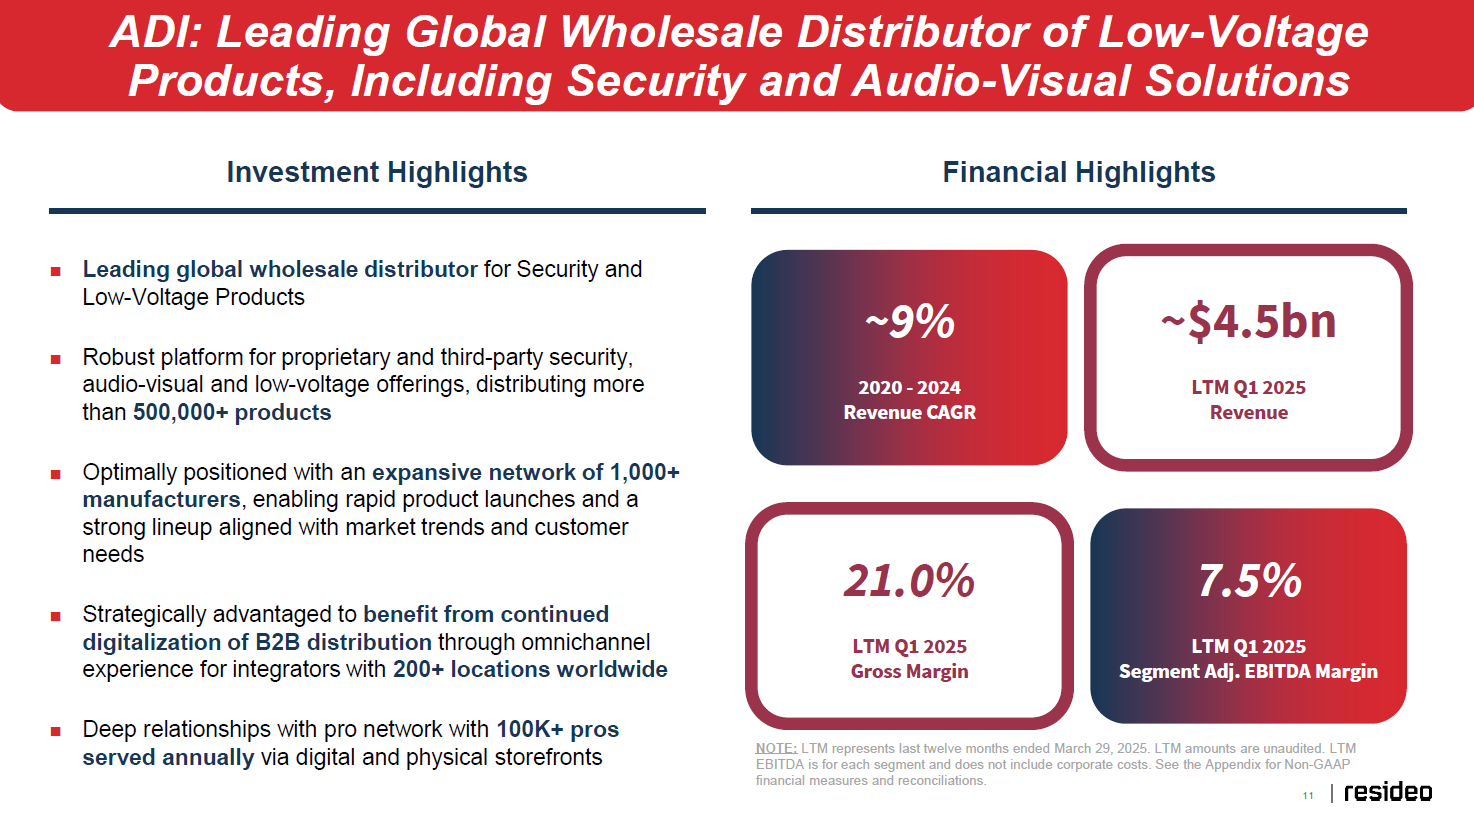
SpinCo – ADI Global Distribution: ADI is a leading wholesale distributor of low-voltage products (security, AV, smart home gear) with a global footprint. Over the 12 months ended Q1 2025, the ADI segment generated $4.5 B in revenue at a 7.5% adjusted EBITDA margin.
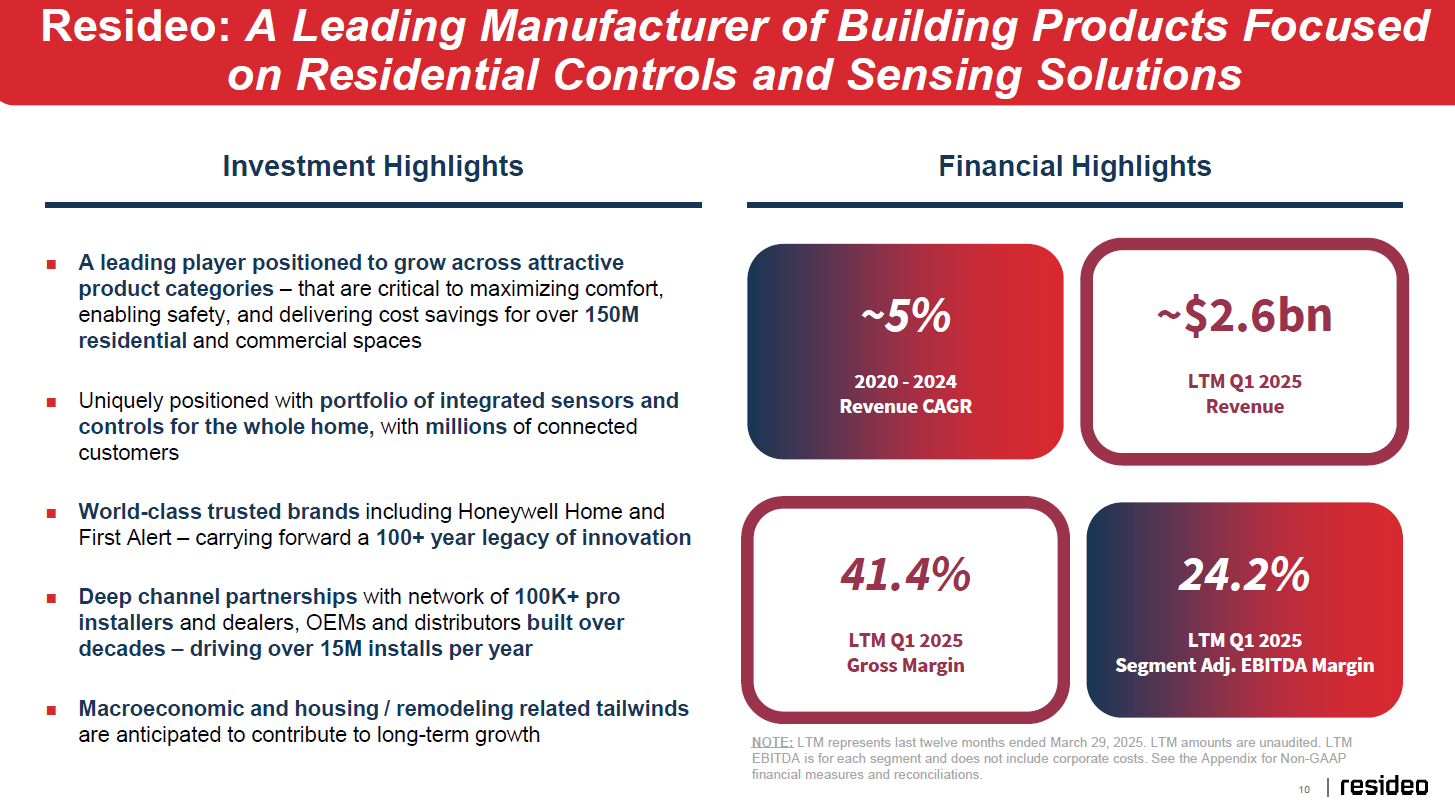
RemainCo – Products & Solutions (Resideo): This business will continue as “Resideo,” focused on residential comfort, security and automation devices (thermostats, safety detectors, water/energy controls, etc.). Key brands include Honeywell Home thermostats, First Alert/BRK alarms, and Braukmann water products. P&S had $2.6 B in TTM revenue with a 24.2% EBITDA margin.
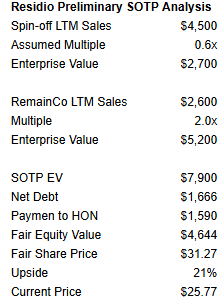
Peer distributors trade around 0.6–0.7x sales (for example, WESCO International’s EV/Revenue is ~0.7x). Assuming a 0.6x sales multiple, the spin-off would have an enterprise value of $3.2BN.
Industrial tech/building products peers trade at higher multiples (JCI-3.4x LTM Sales, ALLE-4.1 LTM sales, CARR-3.0x LTM sales). Assuming a 2.0x sales multiple, RemainCo would have an enterprise value of $5.2BN.
The SOTP math (using conservative multiples) suggests there is ~21% upside.
This situation looks interesting.
Spin-off Links
Resideo to Break up into Two Public Companies
- My initial take is this transaction will unlock value
- More work to do
Franklin Street Properties: Office Basket, Strategic Alternatives
- Good write up from Clark Street Value
- Looks very cheap.
Recommendations Updates
- Brightstar Lottery
Brightstar Lottery (BRSL) reported solid Q2 2025 results and is delivering on every aspect of the original thesis I laid out in June. The company has now begun executing on the largest capital return in its history: a $3.00 per share tax-free special dividend (paid July 29) and a $250MM accelerated share repurchase (ASR) — the first half of a $500MM buyback authorization.
Two key details from the earnings call are worth highlighting:
The $250MM ASR will reduce the float significantly, as De Agostini (43% owner) is not participating. This could remove ~14% of the public float.
All 2025 dividends — including the $3 special and the remaining regular $0.20 quarterly dividends — are expected to be tax-free return of capital for U.S. shareholders.
Brightstar also reiterated that it will maintain its $160MM annual dividend, so with fewer shares outstanding, the per-share dividend will increase, potentially rising to ~$0.22–$0.24 per quarter.
At a post-dividend share price of $14.95, BRSL trades at ~7.5× normalized free cash flow, with a 5.3%+ yield that is likely to rise. Management reaffirmed $1.1BN in 2025 Adjusted EBITDA and guided to stronger free cash flow in the back half of the year.
My original thesis — that Brightstar would return over $1BN to shareholders and rerate as a focused, high-margin, monopoly-like lottery business — is playing out. I continue to view $20 as a reasonable price target, based on a combination of dividend yield and FCF multiple.
2) Western Digital
Western Digital reported strong results this week.
Revenue of $2.61 B (+30% y/y) beat consensus ($2.46 B). Non-GAAP EPS came in at $1.66, topping Street expectations ($1.47) by ~13%. Both metrics exceeded the high end of guidance, driven by surging cloud demand.
Margins & cash flow: Gross margin expanded to ~41% (above guidance) on a richer mix of high-capacity drives. Free cash flow was $675 M in the quarter, enabling aggressive debt reduction (paid down $2.6 B debt in Q4) and bringing net leverage into the target 1.0–1.5× range.
Raised guidance: Management guided Q1 FY26 revenue of ~$2.7 B (midpoint, +22% y/y) and non-GAAP EPS ~$1.54– above consensus ($2.55 B and $1.40). Leadership cited “strong momentum” driven by Cloud (hyperscale) demand, the company’s largest market
WDC authorized a $2BN share repurchase program and intends to return all excess cash flow to shareholders.
WDC isn’t dirt cheap anymore but remains attractive given strong secular tailwinds. It continues to look attractive on a relative basis (12x NTM P/E vs. STX at 15x).
3) Hamee Corp (TSE: 3134)
This week, I recommended a new idea: Hamee Corp.
Some of my favorite situations are international spin-offs because they fly under the radar. Hamee has not been written up on VIC, Seeking Alpha or Twitter (I found one writeup on Substack). The company is 3 months away from breaking up into two separate companies which both look attractive. It is currently classified as a Specialty Retail company but will spin off a high growth, high margin, SaaS company in November that I estimate is worth more than the entire company’s market cap today. The stock looks compelling on an absolute basis (5.1x NTM EBITDA) and SOTP basis. I see 31% to 117% upside over the next 6 months as the breakup is completed.
Spin-off Calendar
Upcoming Spin-off Calendar | Completed Spin-off Calendar
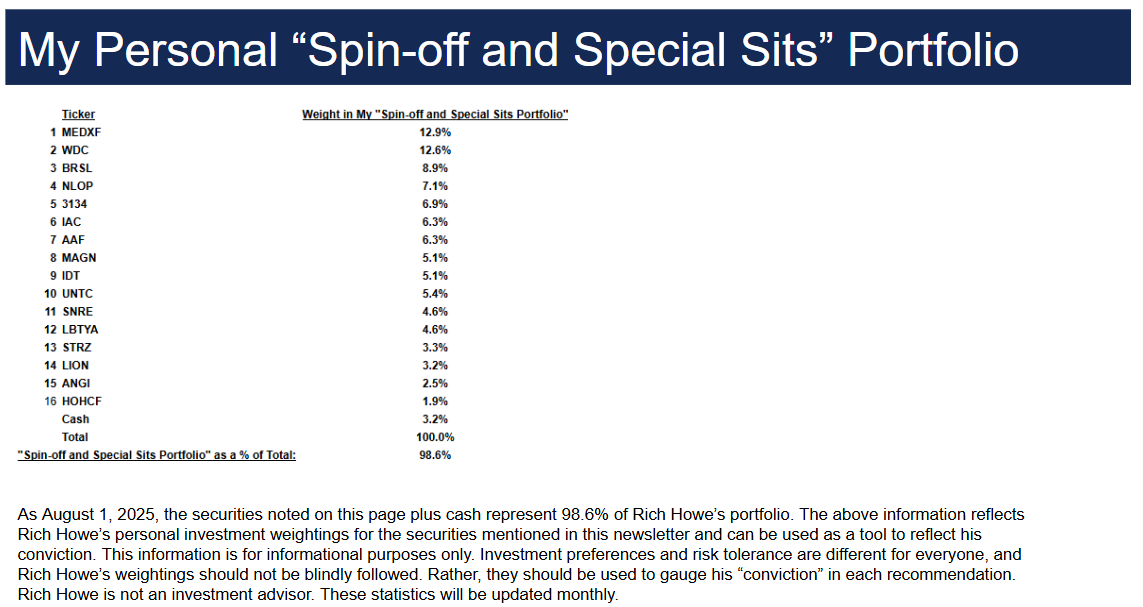
Current Positioning
(updated once a month)
Hope you had a great week!
Rich
Disclaimer:
Rich Howe, owner of Stock Spin-off Investing (“SSOI”), currently is long IDT, MEDXF, AAF, IAC, UNTC, HGHCF, WDC, MAGN, LION, STRZ, NLOP, BRSL and TSE: 3134. All expressions of opinion are subject to change without notice. This email is provided for informational purposes. Please do your own due diligence and consult with an investment adviser before buying any stock mentioned on www.stockspinoffinvesting.com.’
Leave A Comment