

Weekly Update (HON, SOLS, BRSL )
August 30, 2025
Next Friday, September 5 at 1pm ET, I will host my monthly call.
Here’s what I will cover:
- My favorite idea to put new money into
- The upcoming spin-off that I’m most excited about
- Continental’s upcoming break up
- Honeywell’s Valuation on a SOTP Basis
- Review all recommendations
- Answer questions
You can us this link to join.
This week, I published an update on Unit Corp (UNTC).
You can read it here.
Alright, now on to my regular update
Weekly Update
If you haven’t already, consider joining our discord channel (included with your paid subscription):
Join Discord Channel (you must create a free discord account to join)
It’s basically a chat room where we discuss what’s going on in the special situation market:
Here are a few things we discussed this week:
- Good Q&A on Hamee Corp
- Quick discussion on why I’m going to be increasing my WDC price target
- Aptiv looks pretty attractive on consolidated and SOTP basis
Upcoming Spin-offs
Honeywell’s spin-off of its Advanced Materials business, to be named Solstice Advanced Materials (SOLS), is scheduled for completion in Q4 2025.
Solstice recently filed its Form 10 Information Statement and confirmed Q4 timing. Here is the slide deck that was published at the time of the announcement last fall.
An investor day is planned for October 8, 2025, in New York City, where Honeywell will provide further details on Solstice’s business strategy and growth prospects.
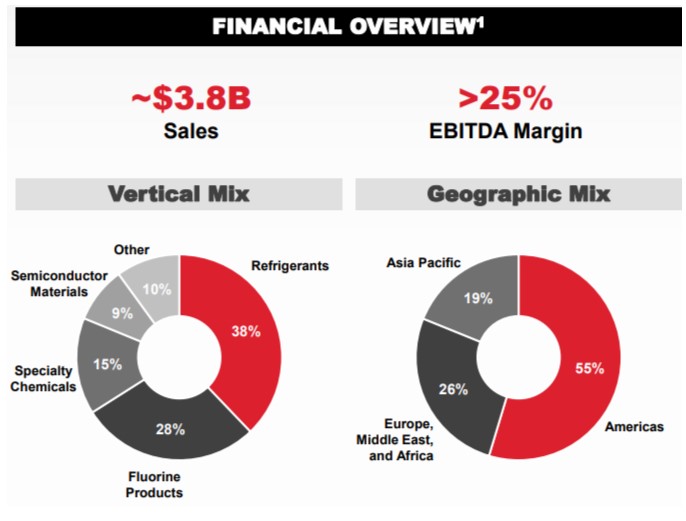
The Advanced Materials portfolio includes leading brands such as Solstice®, Spectra®, Hydranal® and Aclar®, among others. The spin-off will be a leading provider of sustainability-focused specialty chemicals and materials with approximately $3.8 billion of revenue (~10% of Honeywell total revenue) and a ~29% EBITDA margin in FY24.
Solstice consists of two different segments:
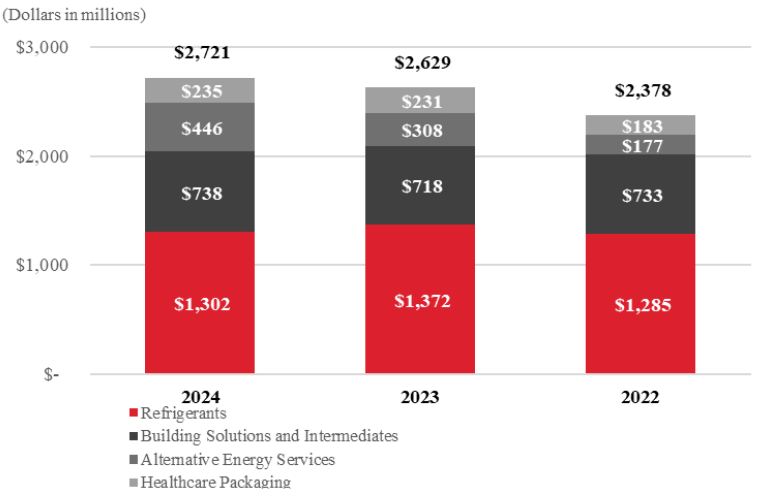
- Refrigerants & Applied Solutions (RAS)
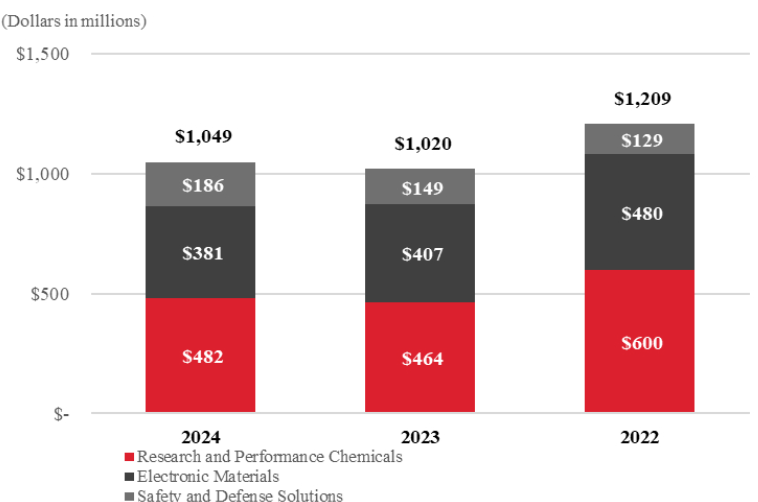
- Electronic & Specialty Materials (ESM)
RAS contributes the majority of revenue (72%) and has higher margins (~40%).
ESM contributes 28% of sales and has lower EBITDA margins (~20%)
Why is Honeywell spinning off this business?
Honeywell has been focused on three megatrends: automation, the future of aviation and energy transition. Solstice doesn’t fit any of these megatrends. In addition, the advanced materials business is more cyclical and capital intensive than Honeywell’s remaining business.
The Advanced Materials spin-off was announced on October 8, 2024. Shortly afterward, activist investor Elliott Management argued that this step alone was insufficient to unlock full shareholder value. In response, Honeywell expanded its strategy into a three-way breakup, planning separate, independent public companies for Advanced Materials, Automation, and Aerospace.
Once Solstice is spun off, Honeywell plans to separate its remaining Automation and Aerospace businesses in the second half of 2026.
Given their strong margin performance and aligned business profile, 3M and DuPont serve as the most appropriate public comparables for Solstice.
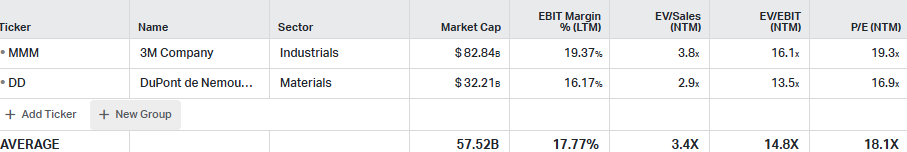
Assuming Solstice should trade at the low end of its comp range given spin-off dynamics and its lower scale, I estimate a fair equity value of ~$8BN to ~$9BN.
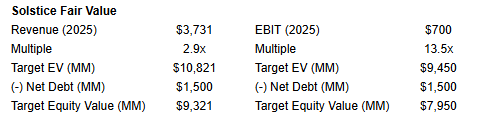
Honeywell’s market cap is $140BN so we could see some indiscriminate selling pressure.
Solstice could be an attractive stock at the right price.
On a sum-of-the-parts (SOTP) basis, I see about ~27% upside for Honeywell.
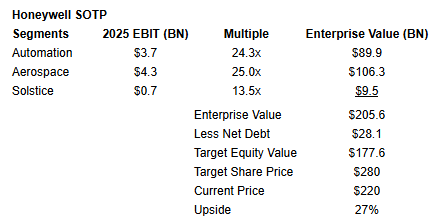
This could be conservative. Aerospace peers, GE and HEI, trade at 33x and 37x, respectively, but I feel a little uncomfortable assigning such a high multiple (but perhaps it’s appropriate). I will finetune my SOTP valuation heading into the Solstice spin-off.
Spin-off Links
DuPoint to Sell Kevlar Segment for $1.8BN
- Sale won’t impact electronics spin-off.
The Twilight Saga to Return to Theaters in October
- Interesting news from Lionsgate.
Inner workings of Keurig Dr Pepper’s $18 billion move for JDE Peet’s
- The market doesn’t like this deal, but it could be an interesting opportunity once the spin-off happens in 2026.
Recommendations Updates
(1) Brightstar Lottery (BRSL)
The Powerball jackpot has soared to $1 billion for the drawing on Saturday, August 30, marking the sixth-largest prize in the game’s history. Such high jackpots typically garner widespread media attention, attracting casual players and boosting ticket sales.
This is typically good for Brightstar Lottery. It will drive modest earnings upside and improve sentiment in the stock. The stock continues to look attractive given attractive its absolute and relative valuation, the ongoing accelerated share repurchase program and earnings upside from the Powerball.
Spin-off Calendar
Upcoming Spin-off Calendar | Completed Spin-off Calendar
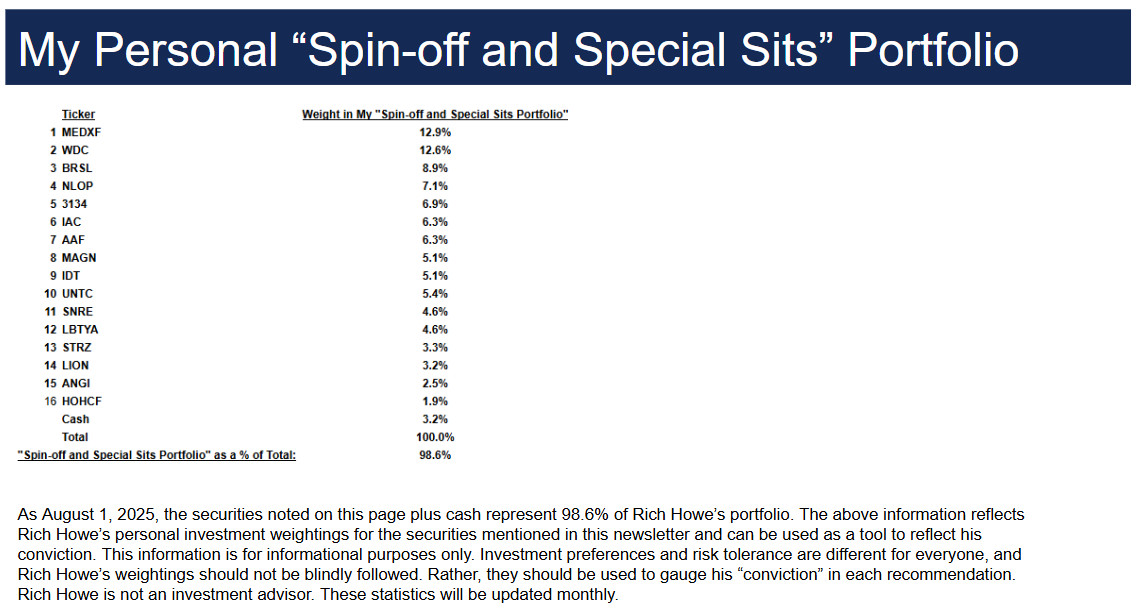
Current Positioning
(updated once a month)
Hope you had a great week!
Rich
Disclaimer:
Rich Howe, owner of Stock Spin-off Investing (“SSOI”), currently is long IDT, MEDXF, AAF, IAC, UNTC, HGHCF, WDC, MAGN, LION, STRZ, NLOP, BRSL and TSE: 3134. All expressions of opinion are subject to change without notice. This email is provided for informational purposes. Please do your own due diligence and consult with an investment adviser before buying any stock mentioned on www.stockspinoffinvesting.com.’
Leave A Comment