

Spin-off Links – November 2025
So far in 2025, there have been 11 new US spin-off announcements. Meanwhile 11 new spin-offs have started trading.
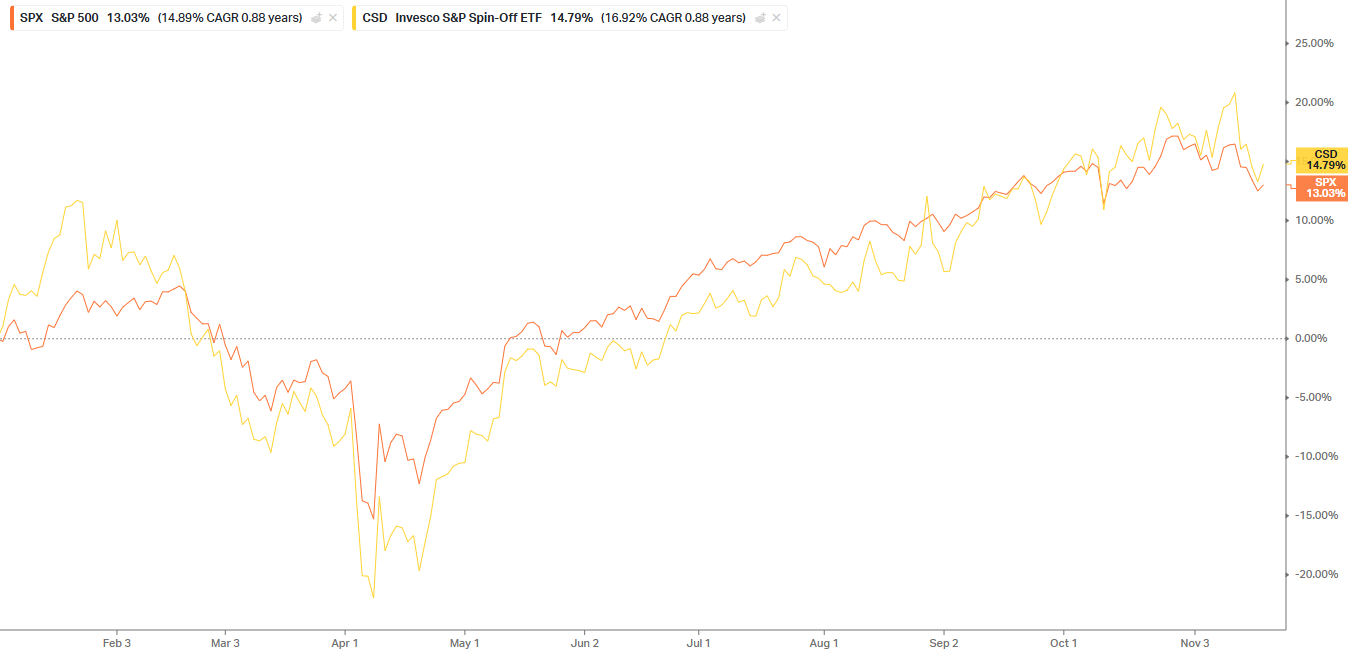
Spin-offs have performed well in 2025, beating the S&P 500 by almost 200bps.
Without further ado, let’s move on to the latest spin-off news….
Recent Spin-off Announcements
Johnson & Johnson (JNJ) announced on October 14, 2025, that it plans to spin off its orthopedics business into a standalone company, to be called DePuy Synthes.
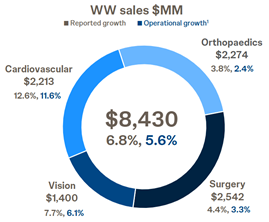
The orthopedics business generates almost ~$9BN of annual sales. It represents 27% of JNJ’s MedTech sales and ~9% of total JNJ sales. A snapshot of Q3 2025 revenue is shown below:
Rationale for the spin-off
(1) J&J sees greater growth potential in areas such as cardiovascular, robotics, oncology, neurology, vision, and surgical technologies, and wants to redeploy capital accordingly.
(2) Orthopaedics is relatively more capital intensive than J&J’s remaining businesses; shedding it allows the company to become more capital efficient.
The transaction is expected to take 18 to 24 months.
Whenever a spin-off is projected to take nearly two years to be completed, it usually suggests two things: (1) the company has not yet fully hammered out the detailed plans for separation, and (2) the parent is likely running a sale or divestiture process in parallel with the spin-off.
JNJ stated that it “intends to explore multiple paths to effect the planned separation.”
The best comps for the ortho business are probably Zimmer Biomet and Smith & Nephew.
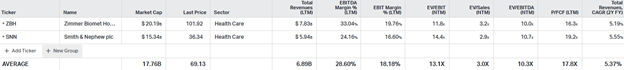
If the orthopedics spin-off were to command a 3x sales multiple, its implied enterprise value would be around $27 billion (given ~$9 billion in revenue). Meanwhile, J&J’s current enterprise value is in the ballpark of $490 billion. From my perspective, this is not an actionable opportunity today for two reasons: (1) it will take so long to execute, and (2) the size of the value being unlocked is de minimis relative to J&J’s scale.
This could be an interesting “indiscriminate selling” candidate.
Recent Spin-offs
Dupont (DD) spun off its electronics business, Qnity (Q), on November 3rd.
Qnity is one of the world’s largest pure-play electronic materials companies, with a portfolio spanning semiconductor fabrication materials and advanced electronics/interconnect solutions.
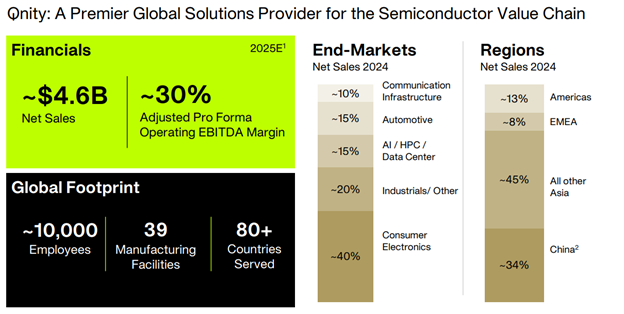
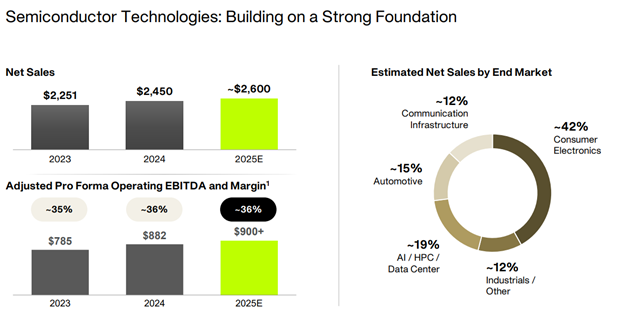
Qnity’s Semiconductor Technologies division creates consumable products that are used during semiconductor manufacturing.
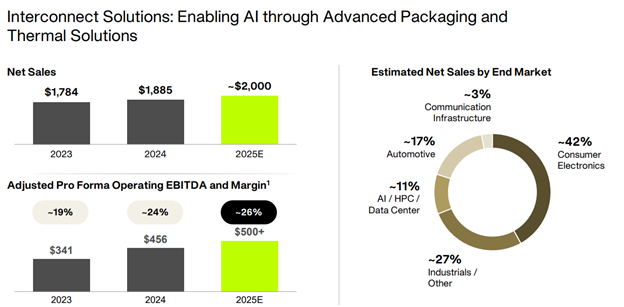
Qnity’s Interconnect Solutions (ICS) division produces a wide array of materials, films, laminates, and imaging products used in PCB fabrication, flexible circuits, and advanced packaging.
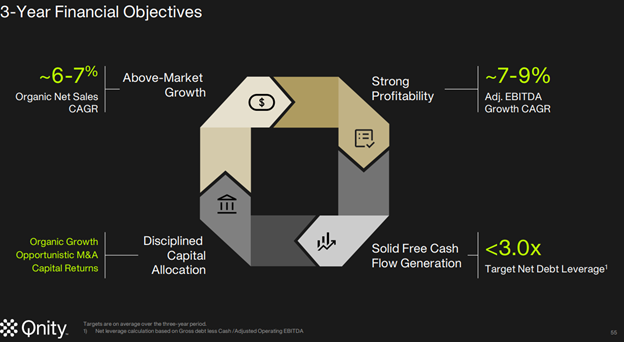
Management expects to grow the topline at a high single digit CAGR.
Qnity’s best comps are Entegris, Element Solutions, and MKS.
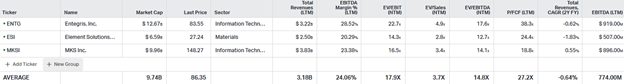
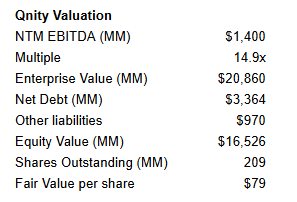
Assuming Qnity should trade inline with peers at 14.9x EBITDA, the stock is worth $79/share.
I published a deep dive on Qnity for premium members here.
Honeywell (HON) spun off 100% of its Advanced Materials business, Solstice (SOLS), on October 30, 2025.
Solstice is a leading global supplier of environmentally sustainable refrigerants, electronic materials, and specialty chemicals. The business has historically grown at roughly a 4% CAGR and is positioned to benefit from several long-term tailwinds — including semiconductor expansion, data center growth, industrial onshoring, and regulatory phase-downs of high-GWP refrigerants.
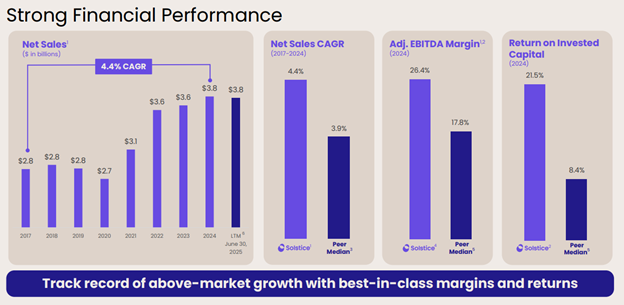
Solstice operates through two divisions: Refrigerants & Applied Solutions (RAS) and Electronic & Specialty Materials (ESM). These businesses are high-margin and innovation-driven, supported by strong regulatory and technology barriers.
While near-term growth is modest, the portfolio carries mid-20s EBITDA margins and limited cyclicality relative to peers, underpinned by strong after market demand. Solstice will begin life with a conservative balance sheet (~1.5x net leverage) and expects steady free cash flow generation.
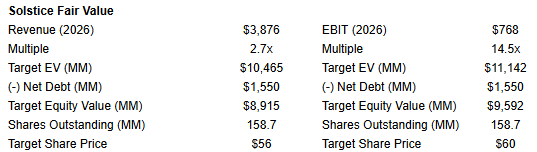
Solstice has given 2025 revenue guidance for $3.8BN (midpoint) and an adjusted EBITDA margin of 25%. Factoring synergy costs and TSA costs, the margin guidance looks relatively conservative to me.
I expect Solstice to grow the topline by ~2% in 2026 and expand margins modestly.
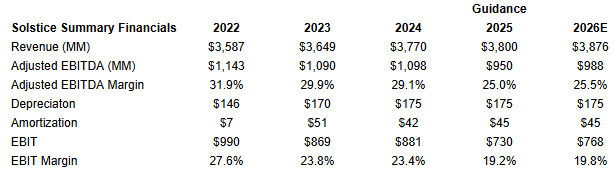
Solstice comps trade at 3.7x sales and 17.2x on an EV/EBIT basis.
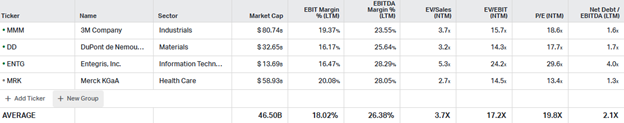
Assuming Solstice deserves to trade at the low end of its peer group given spin-off dynamics, it’s worth ~$58/share.
A key risk is the potential erosion of patent protection for its R-1234yf refrigerant portfolio, which could pressure margins in the Refrigerants segment if competitors gain share.
I published a deep dive on Solstice for premium members here.
On Monday, October 30, 2025, Thyssenkrupp AG (XTRA: TKA) spun off 49% of its stake in Thyssenkrupp Marine Systems (TKMS).
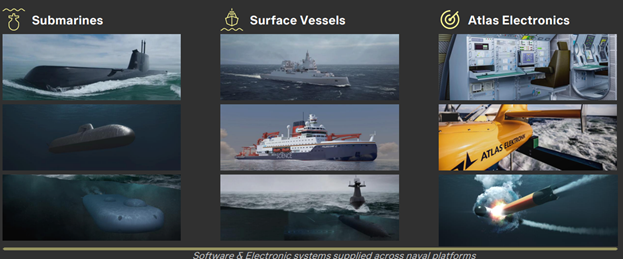
TKMS is the naval-/marine-defense systems business of Thyssenkrupp. It is Germany’s only full-systems provider for non-nuclear submarines, surface vessels and maritime electronics.
The ongoing Russia‑Ukraine War has sharply elevated defense spending in Europe and underscored the need for NATO allies to rebuild naval, submarine and ship-systems capabilities.
European capitals are responding with multi-year procurement plans and industrial expansion initiatives aimed at reducing strategic dependence on foreign supply, while the United States is pressing allies to accelerate investment, creating a strong demand tailwind for firms in the maritime/defense sector.
This has driven interest in TKA and the stock has performed exceptionally well over the past year.
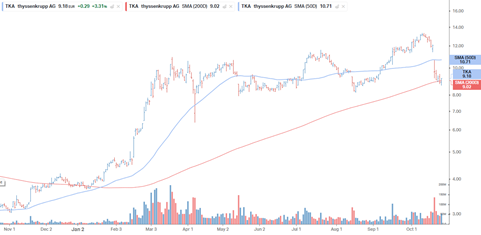
Given this backdrop, TKMS is extremely well positioned for the next 3-5 years.
TKMS is one of Europe’s only Europe’s only pure-play public military shipbuilding companies.
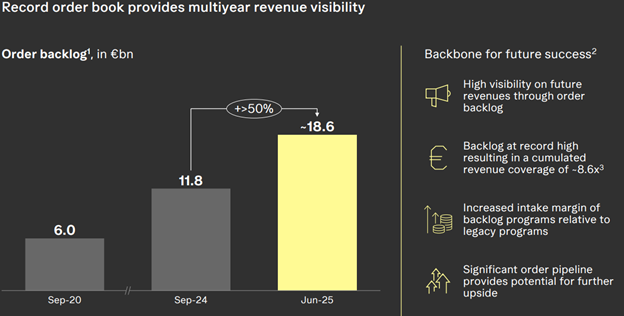
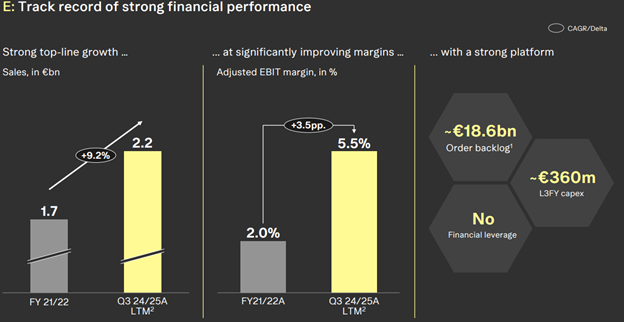
Its backlog is growing…
And revenue/earnings are following suit…
The only problem is valuation.
TKMS is currently trading at 37.5x EBIT.
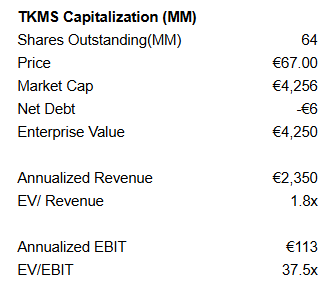
If you assume EBIT margins grow to 9% from 5.5% currently, it’s still expensive (27x EBIT).
Peers trade at 26x EBIT.
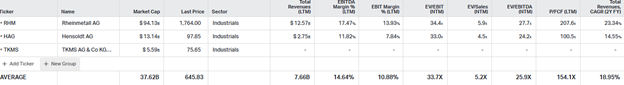
The bull case is that TKMS can increase margins into the teens but I’m not confident that is realistic.
For what it’s worth, sell side analysts have estimated fair value at €2BN to €4BN (€35 to €65 per share).
I think the RemainCo (TKA) looks more interesting and that’s where I will be focusing in the weeks ahead.
Imminent Spin-off
Unilever (UL) has stated that the spin-off is on track to complete by December 6, 2025, with trading of The Magnum Ice Cream Company (MICC) shares expected to begin on December 8, 2025. I’m not interested in owning Unilever, but would be interested in Magnum at the right price.
The decision to spin off the ice cream segment reflects management’s desire to separate a highly seasonal, more capital-intensive, lower-margin business from RemainCo.
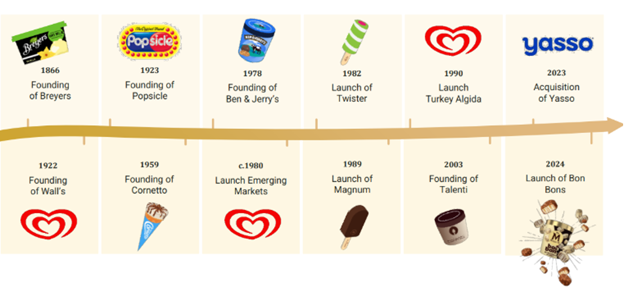
The company has been around for 160 years and has many notable brands.
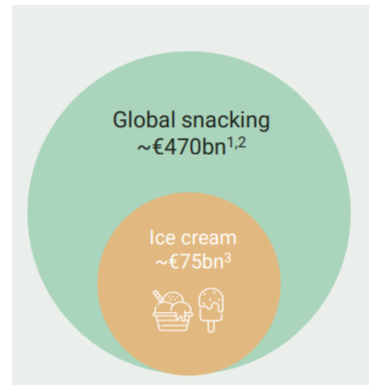
Ice cream is a large portion of the global snacking market.
It has historically grown at a rate of 3-4%…
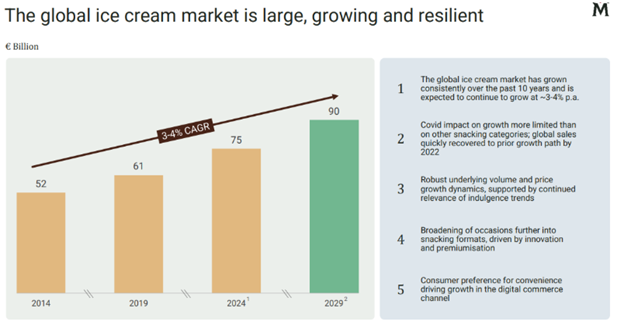
I was concerned that growth would be negatively impacted by the increased proliferation of GLP-1s, but it doesn’t seem to be having a big impact yet.
Magnum has historically grown at a 3% organic CAGR and expects to grow at 3% to 5% per year going forward.
Magnum’s business is split roughly 50/50 between At-Home and Away-from-Home.
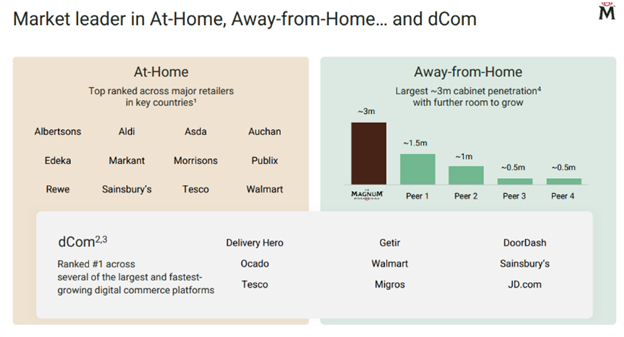
A cabinet is a commercial ice-cream freezer or display chest used to store and sell ice-cream products at retail and out-of-home locations (e.g., small shops, gas stations, beach kiosks).
These freezers are typically owned or leased by the manufacturer, not the retailer. Unilever installs and maintains them to ensure proper temperature control and prominent brand visibility (e.g., the red Wall’s logo or Magnum branding).
The company’s network of ~3 million cabinets worldwide means Magnum (and Unilever’s other brands like Cornetto and Ben & Jerry’s) have one of the largest direct-to-freezer retail footprints in the world.
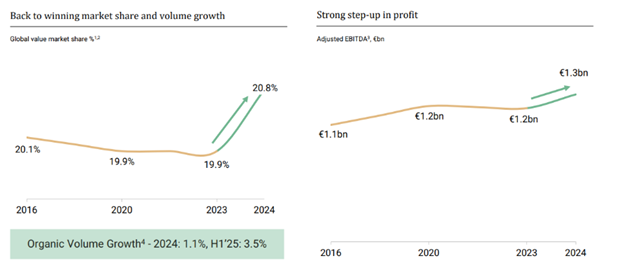
Management has been doing a good job of accelerating volume growth recently…
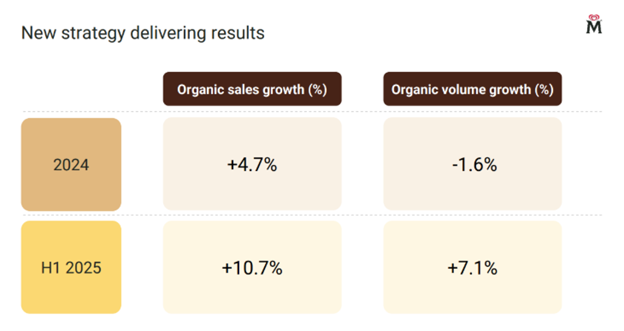
What has driven the volume acceleration?
During 2022–2023, inflation forced Unilever to push through high double-digit price increases (especially in Europe and Latin America). That depressed volumes.
In 2024, pricing stabilized (low single digits) while volumes turned positive again, meaning consumers came back to the category once sticker shock faded.
Magnum and Cornetto benefited most, with premium impulse SKUs (Magnum Double Gold Caramel, Cornetto Soft) outperforming lower-tier lines.
Management said at its analyst day that “balanced price and volume growth” was the main driver of the recent +7 % underlying sales growth.
Margins have been increasing inline with volumes.
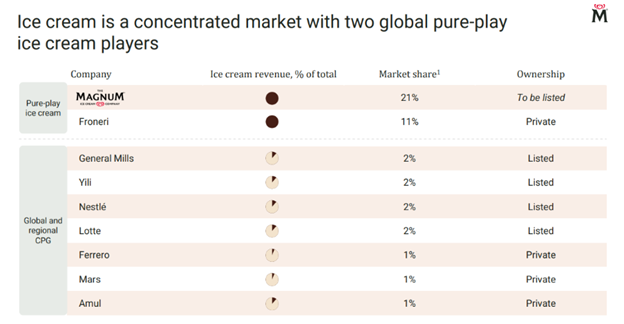
Magnum has no public pure play comps…
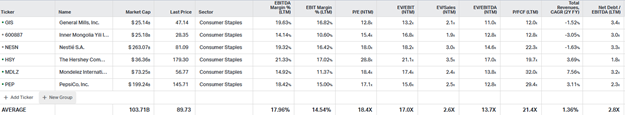
But relevant consumer staples companies trade at 13.7x EBITDA, 2.6x Sales, and 21x FCF.
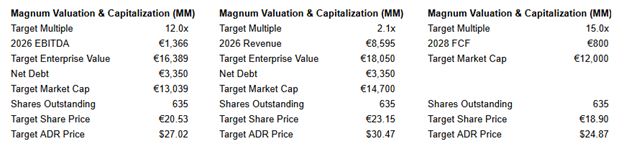
Assuming Magnum will trade at the low end of this range given spin dynamics, I estimate its worth €19- €23 and $25-31/share.
I published a deep dive on Magnum for premium members here.
Other Spin-off Links
Solstice Advanced Materials Starts Trading. It’s a Play on AI and Nuclear Power.
– Barrons likes Solstice
Good Commentary on Honeywell RemainCo
– Secular tailwinds are definitely in place.
Stock Spin-off Investing Podcast: Colin King and I Discuss NATL AMVO, and SOLS
– 3 interesting current spin-off situations
Grupo Herdez: A quick 60% upside
– Very good write up on a company that recently spun off a money losing division.
WSJ: Thyssenkrupp’s Warship Arm to List Next Week as Group Eyes European Defense Cash
– Thyssenkrupp will retain 51% of the business.
Disclosure/Disclaimer:
All expressions of opinion are subject to change without notice. All published emails/articles/correspondence is provided for informational purposes. We do not warrant the completeness or accuracy of this content. Please do your own due diligence and consult with an investment adviser before buying or selling any stock mentioned on www.stockspinoffinvesting.com.

Leave A Comment