

Weekly Update (UNTC, RNA, LBTYA)
March 14, 2026
Before I get into my regular update, I wanted to share one chart that caught my eye.
This chart shows the expected impact on oil prices depending on how long the Strait of Hormuz stays closed.
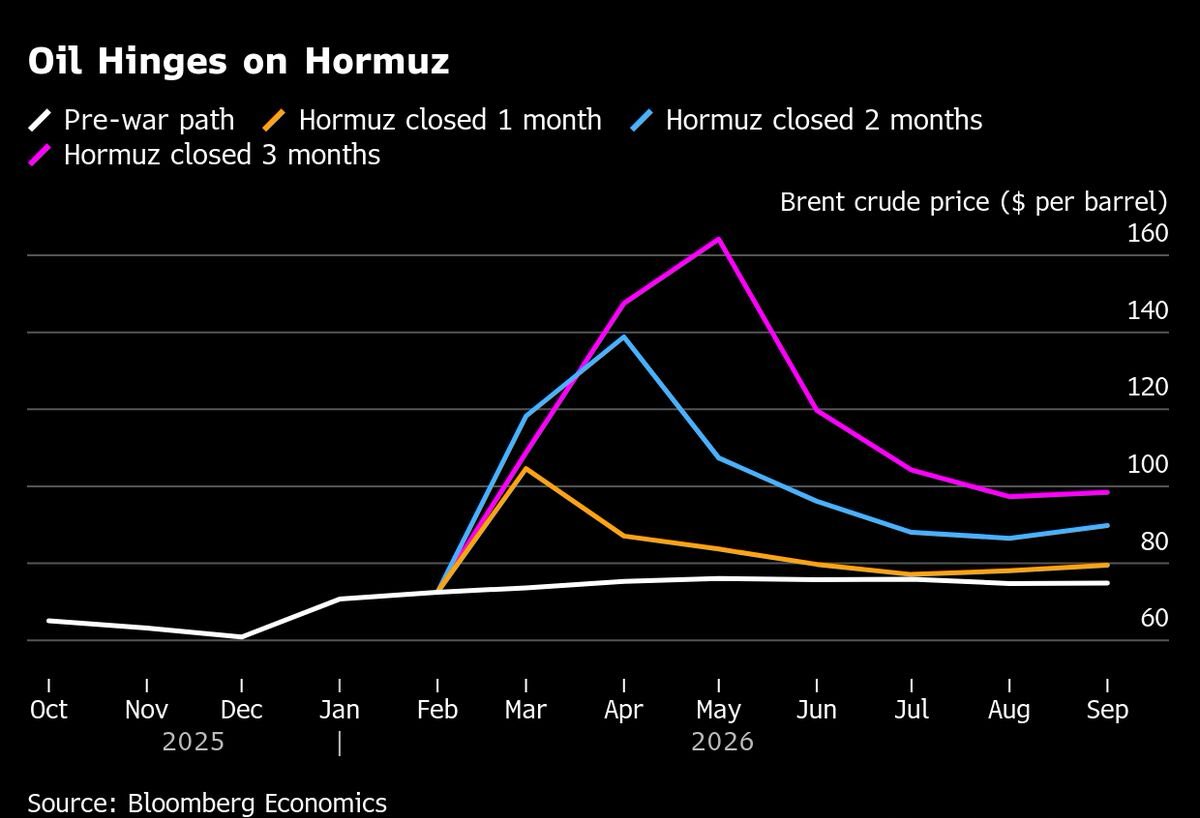
It’s difficult to predict how long it will stay closed, but every day that oil prices remain elevated will benefit Unit Corp (UNTC) which has ~56% of oil production unhedged in 2026.
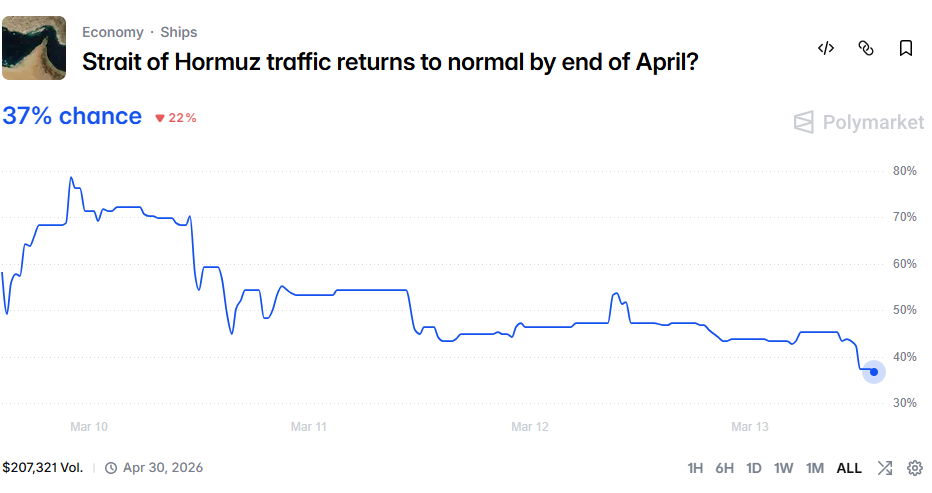
Betting markets suggest low odds of traffic returning to normal by the end of April.
Alright, let’s move on to the rest of this week’s update.
Weekly Update
If you haven’t already, consider joining our discord channel (included with your paid subscription):
Join Discord Channel (you must create a free discord account to join)
It’s basically a chat room where we discuss what’s going on in the special situation market.
Here are a few things we discussed this week:
- Discussion of UNTC’s hedging strategy
- February Treosulfan/Grafapex sales for Medexus look strong.
- Good discussion on REZI
Imminent Spin-off
On February 27, 2026, Atrium Therapeutics (RNA) was spun off from Avinity Biosciences before it was acquired by Novartis (NVS).
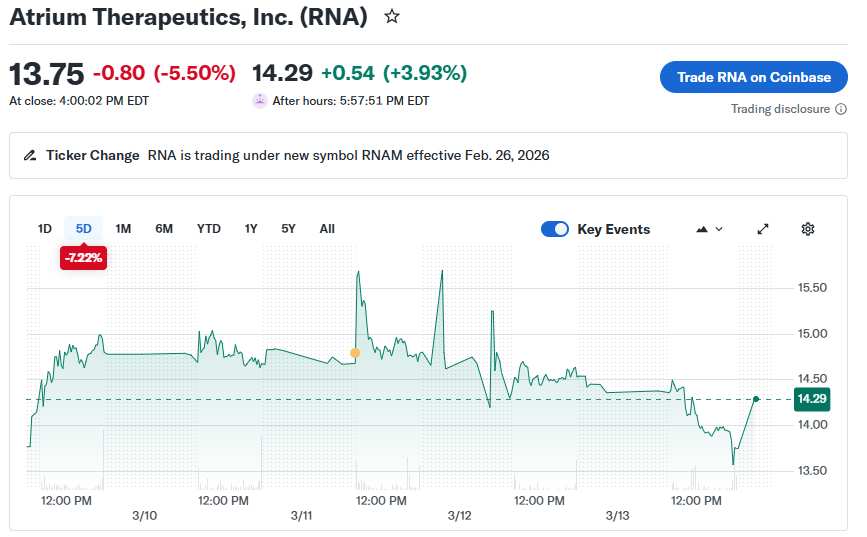
The stock has performed relatively well in initial trading considering the market volatility.
Novartis acquired Avidity’s RNA therapeutics platform and pipeline focused on neuromuscular diseases. Avidity’s RNA programs targeting cardiovascular disease is now Atrium Therapeutics.
Their first two drugs are called:
- ATR-1072
- ATR-1086
These drugs target two rare genetic heart diseases:
- PRKAG2 syndrome
- PLN cardiomyopathy
Both of these diseases:
- Are inherited genetic conditions
- Cause progressive damage to the heart muscle
- Can lead to heart failure, arrhythmias, and early death
- Currently have no approved treatments
Atrium plans to start testing these drugs in humans (Phase 1 trials) to see if they are safe and work as intended.
Atrium is a high risk / high reward biotech. If its platform is successful, it could generate billion dollar drugs. But it is burning significant cash and will need to raise equity within a year or two.
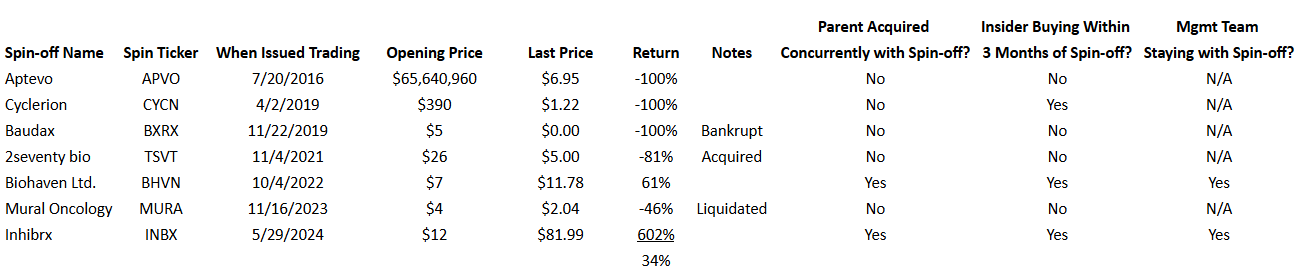
The base rate of success is not great for biotech spin-offs.
Management’s internal discounted cash flow analysis implied a SpinCo equity value of approximately $344MM to $349MM, while Goldman Sachs and Barclays used a more conservative implied value of approximately $270MM, consistent with the amount of cash Atrium will receive at spin.
I think a $270MM equity value is fair given spin-off dynamics and elevated cash burn.
This corresponds to a ~$18/shar fair value.
Spin-off Links
- Great write up on why European Telcos look interesting (especially Liberty Global)
A Net-Net With a Free Call Option on a US$10–12B LNG Project
- Good write up on High Arctic
Aptiv’s Versigent spin-off will unlock value for shareholders – UBS
- UBS sees fair value of $97
Recommendations Updates
Unit Corp
This week, Unit Corp published a new slide deck and its annual report. There were several important takeaways.
1) Hedges. The company has hedged ~44% of its oil production in 2026 at prices between $64 and $74/bbl. For 2027, about ~33% of oil production is hedged between $62 and $65/bbl. While the timing is not ideal given the recent rise in oil prices, the majority of production remains exposed to spot pricing. Oil production also grew 17% last year, so these hedge percentages may be somewhat overstated as I assume flat production.
Approximately ~32% of natural gas production in 2026 is hedged between $4.02 and $4.22/Mcf. This appears well-timed given that Henry Hub spot prices are currently around ~$3.25/Mcf
2) Reserve growth. This was a major positive and increases the company’s terminal value. Proved undeveloped reserves increased 14%. During the year, Unit grew total reserves by 14% while also generating roughly $70MM of free cash flow. That combination is impressive. Unit increasingly looks less like a liquidation story and more like a durable operating business, perhaps even a modest growth story.
3) NOLs. The company still has approximately $105MM of net operating losses (NOLs). Management has indicated that it preferred to utilize these tax assets before pursuing a potential sale of the business. At this point, however, the NOLs appear to be largely utilized and close to being fully exhausted, which could remove a key constraint on strategic alternatives.
4) Potential company sale. On slide 3 of its presentation, Unit Corp notes that “change-of-control ownership restrictions under Article XIV of the charter are now expired.” These provisions were originally designed to limit large share purchases in order to preserve the company’s tax benefits. To me, this effectively reads: “the company is now for sale to the highest bidder.”
All in all, Unit Corp appears well positioned and reasonably valued.
Spin-off Calendar
Upcoming Spin-off Calendar | Completed Spin-off Calendar
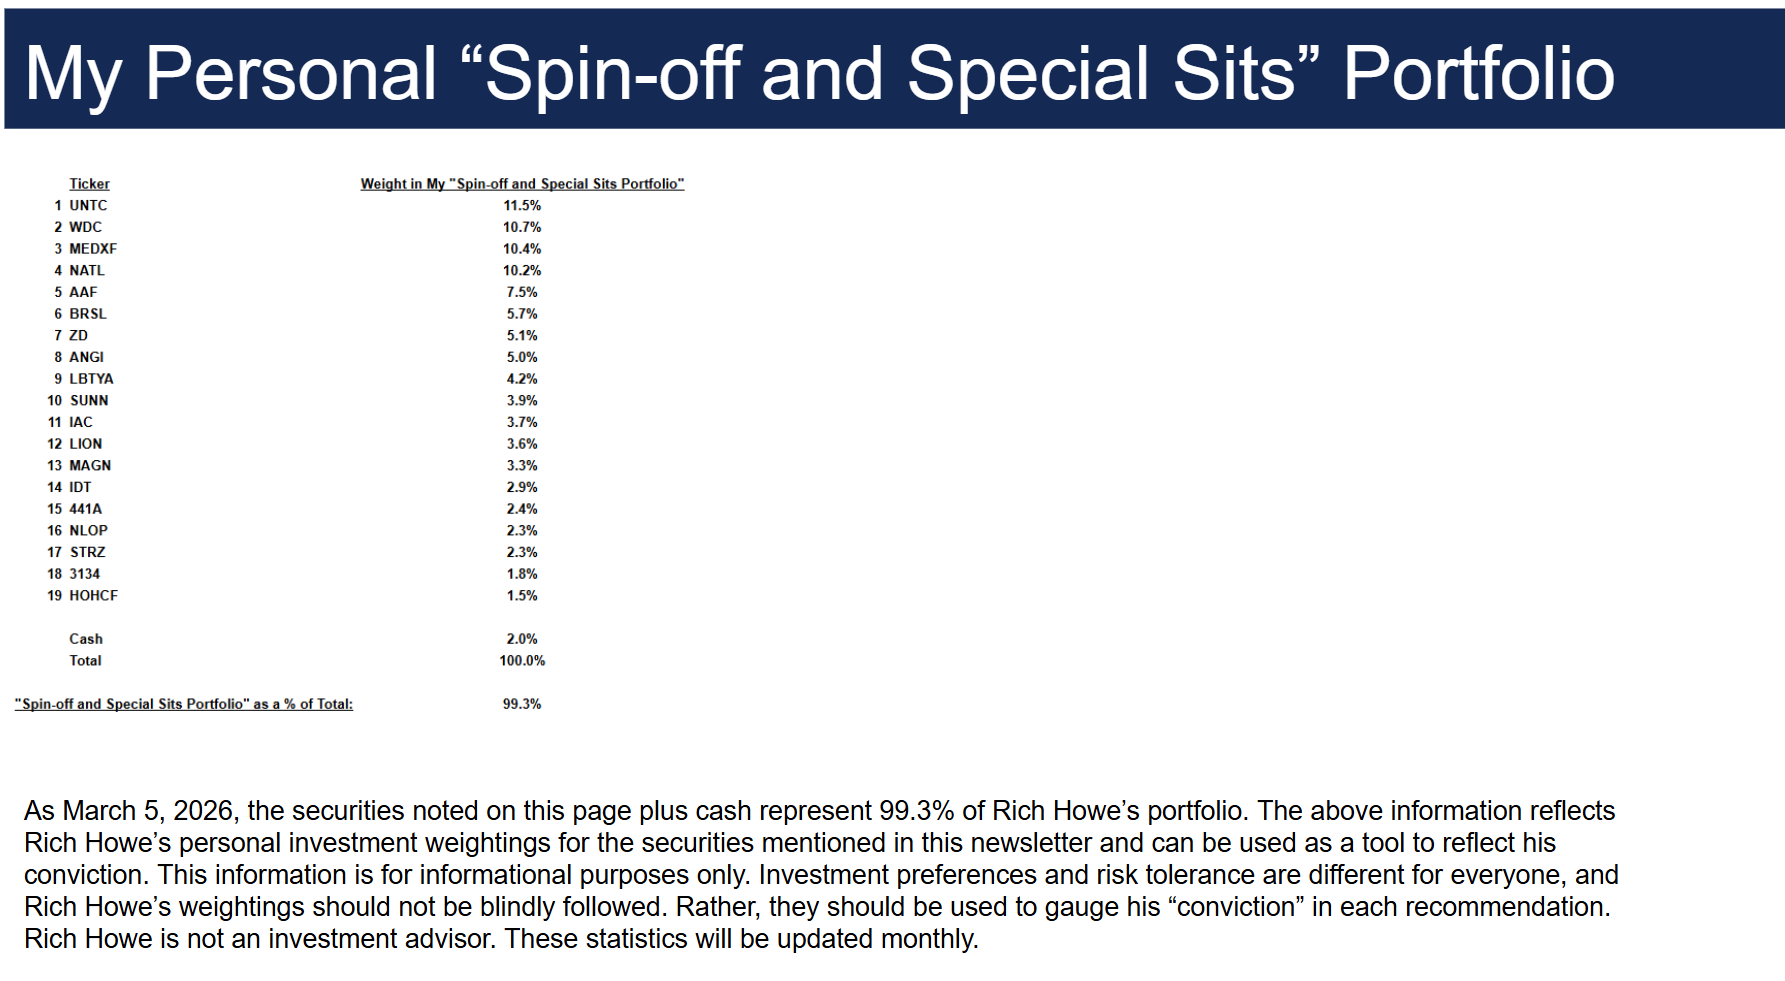
Current Positioning
(updated once a month)
Hope you had a great week!
Rich
Disclaimer:
Rich Howe, owner of Stock Spin-off Investing (“SSOI”), currently is long IDT, MEDXF, AAF, IAC, UNTC, HGHCF, WDC, MAGN, LION, STRZ, NLOP, BRSL TSE: 3134 TSE: 441A, NATL, and ZD. All expressions of opinion are subject to change without notice. This email is provided for informational purposes. Please do your own due diligence and consult with an investment adviser before buying any stock mentioned on www.stockspinoffinvesting.com.
Leave A Comment