

Weekly Update (MFP, HONA, MBGL, CMCSA)
July 10, 2026
Our live monthly Zoom Call starts in 1 hour (1pm ET).
You can use this Zoom link to join.
Here’s what we will cover:
- Review of Recent Spin-offs:
- Honeywell Aerospace (HONA), Mobility Global (MBGL), and Midera Food Processing (MFP).
- Recently Announced Spin-offs
- Review Comcast SOTP.
- Updates on all open recommendations.
- Answer your questions.
- Please let me know in advance if there’s anything specific you’d like me to cover.
Alright, on to the rest of the update.
Weekly Update
If you haven’t already, consider joining our Discord channel (included with your paid subscription):
Join Discord Channel (you must create a free Discord account to join)
It’s basically a chat room where we discuss what’s going on in the special situation market.
Here are a few things we discussed this week:
Recommendations Updates
1. Western Digital (WDC)
Western Digital (WDC) remains volatile, with large swings driven by investor enthusiasm for the AI trade. I continue to believe there is significant earnings upside, as consensus estimates remain too low. This week, several sell-side analysts raised their price targets: Wells Fargo to $730, Goldman Sachs to $650, and Susquehanna to $500. I think an $800 target is reasonable, based on $40/share of 2028 EPS and a 20x P/E multiple.
2. Medexus (MEDXF)
Today I learned, via Bloomberg, that June GRAFAPEX sales were $2.28MM, the strongest month on record and well above the ~$1.5MM area of the prior couple of months. That directly addresses the main hesitation from my June 27 update.
The hesitation was the FY2027 GRAFAPEX guide ($30–32MM, a near-tripling), which looked aggressive and required the ramp to accelerate into a summer stretch management had flagged as seasonally slow. This data addresses that concern. One caveat: the $2.28MM is institutional whole acquisition cost, gross list-price purchasing by institutions, not Medexus’s recognized net revenue, so it doesn’t map dollar-for-dollar. But as a real-time demand proxy it’s exactly what I wanted to see, and the timing is the point. June is the first month of fiscal 2027 and falls in the summer window management said would be soft. Strength here, before the fall acceleration they’re counting on, materially de-risks the guide.
A monthly demand pace in the low-$2MM range annualizes toward the mid-$20MM area on its own, and that’s during the seasonally weak part of the year. If the fall plays out as management described, the $30–32MM guide goes from “aggressive” to “reachable, maybe conservative.” That also supports my above-consensus EBITDA view: consensus sits near $22MM of FY2027 Adjusted EBITDA, and my ~$25MM estimate now looks better founded. The stock still looks cheap at 6.1x FY2027 EBITDA (I’m fully including the business combination payable in my EV calculation).
Recent Spin-off
This week, I’ve been spending a lot of time on the recent Middleby (MIDD) food processing spin-off, Midera (MFP).
I was all excited for indiscriminate selling because I think the long-term outlook is quite attractive, but the stock has gone straight up!
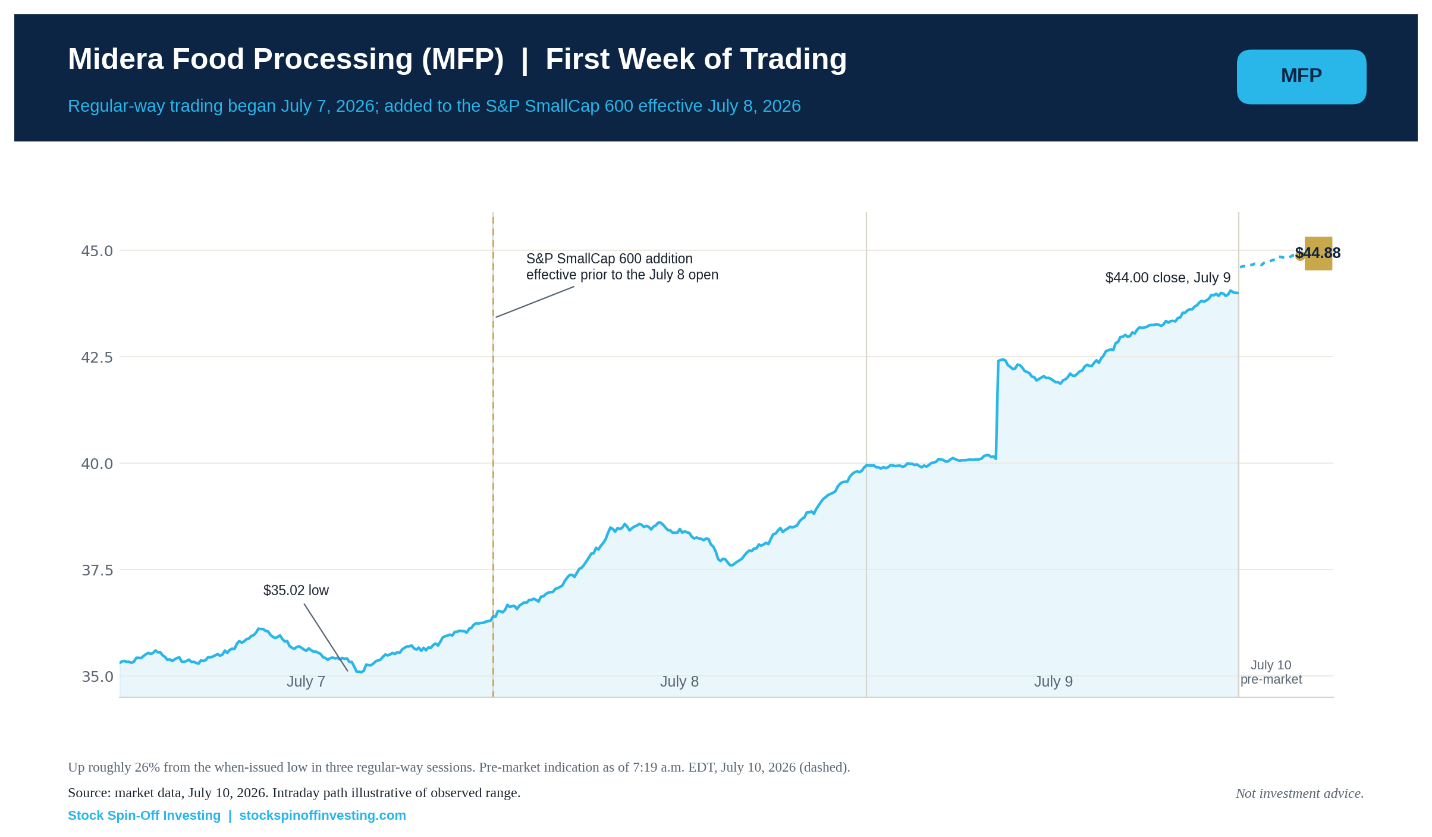
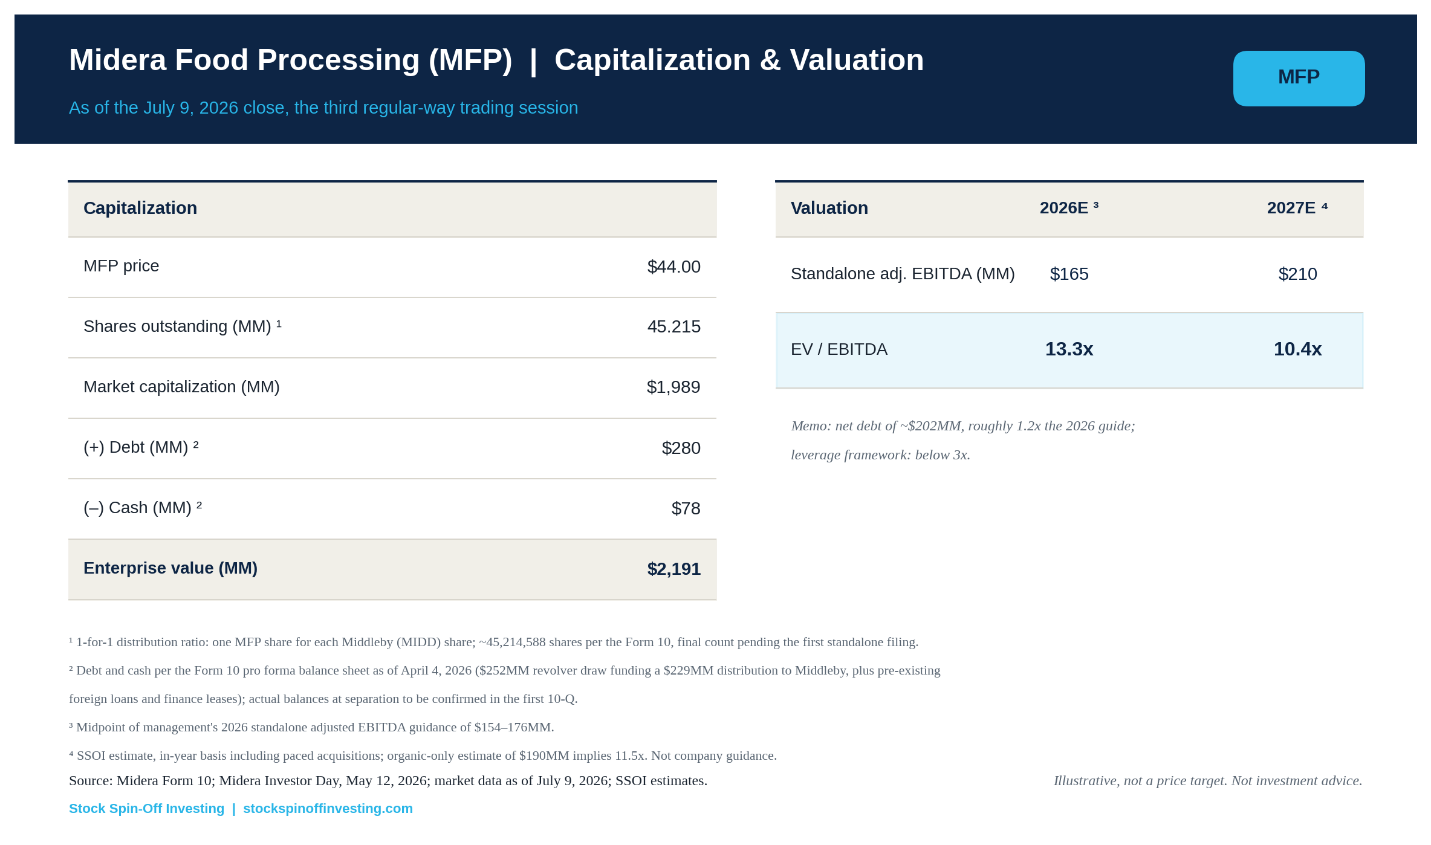
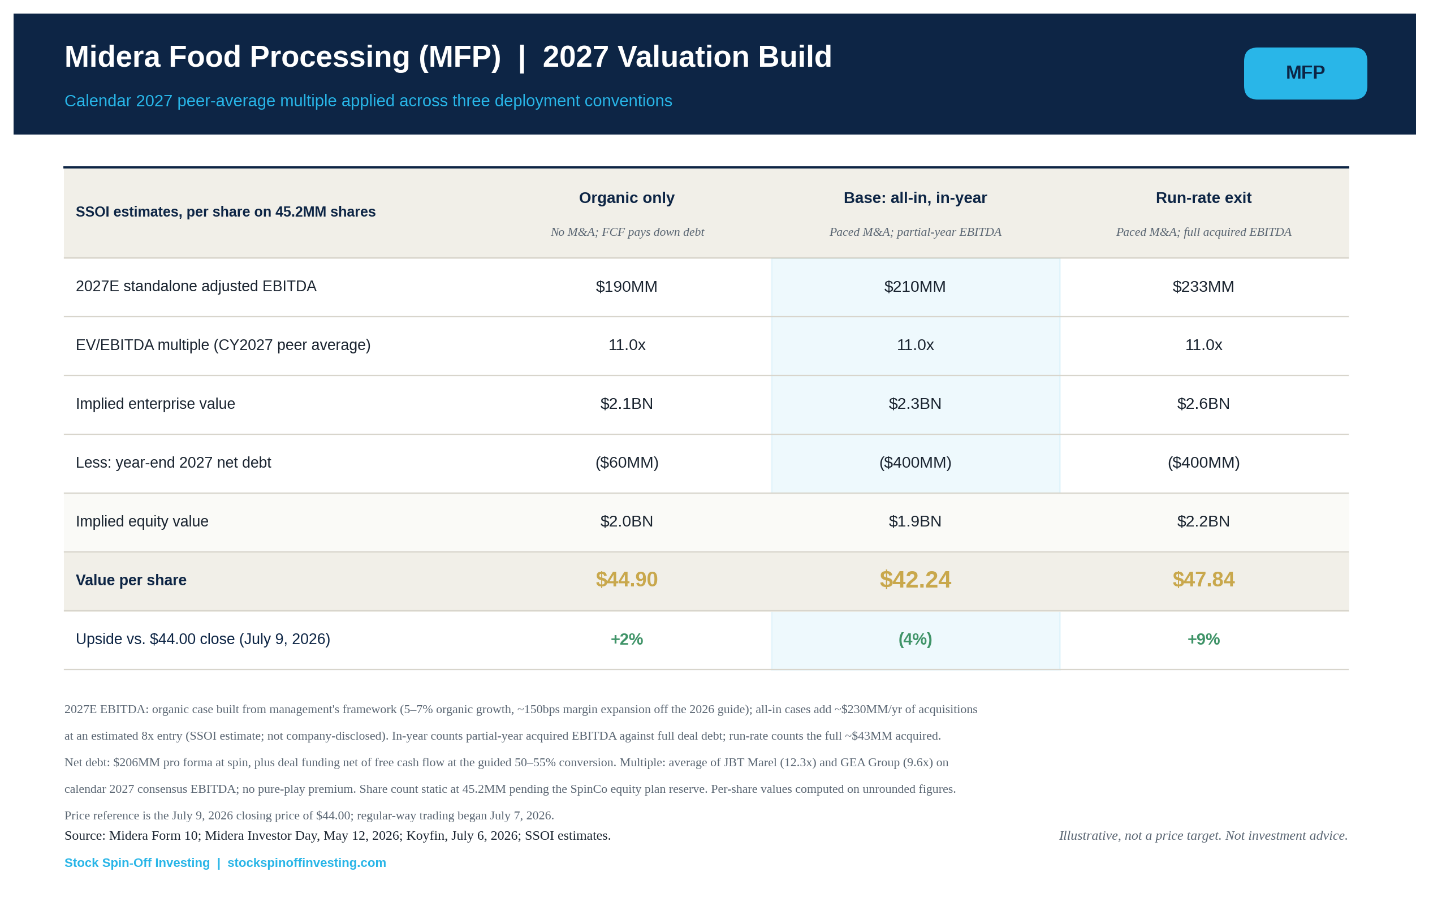
The stock, currently around $44, is trading at 10.4x my 2027 EBITDA estimate of $210MM.
Midera Food Processing makes the industrial equipment that large food manufacturers use to produce the food we buy at the grocery store.
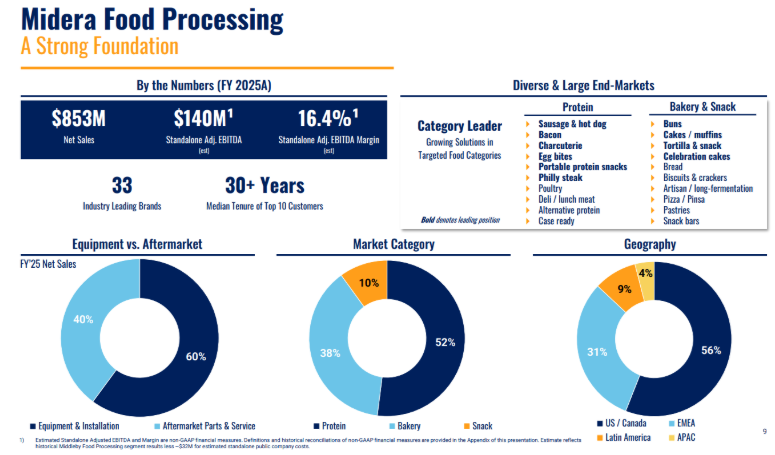
Think about a package of deli turkey, a loaf of sliced bread, a bag of tortilla chips, or a tray of chicken nuggets. The machines that cook, slice, form, package, and freeze those products at scale are exactly what this business makes and sells.
The company’s customers are large protein, bakery, and snack processors like Tyson, Cargill, Hormel, Smithfield, Perdue, Mondelez, and Bimbo.
These are industrial food manufacturers running massive production facilities, and they need highly specialized, expensive equipment that can operate continuously, maintain consistent quality, and meet strict food safety standards.
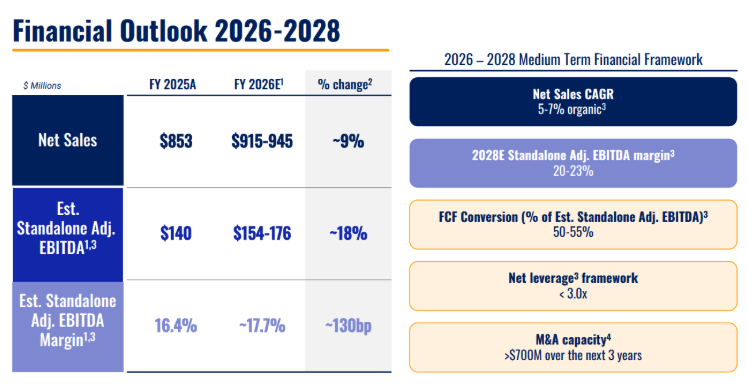
Management expects 5-7% organic growth in the midterm with significant margin expansion.
The acquisition track record is a key part of the Midera story. Over 20 plus years, the Food Processing platform acquired more than 30 companies for roughly $850MM in total, an average deal size under $30MM, at an average adjusted EBITDA margin of approximately 11% at acquisition. Post-integration, the platform operates in the mid-20s. Sourcing is the stated edge: roughly 90% of the deal funnel is proprietary rather than auction-driven, and about 75% of transactions are tuck-ins.
Management does not disclose an entry multiple. Asked directly at the Investor Day, Chief Strategy Officer Matt Fuchsen declined a number but endorsed the derivation: “if you kind of look at the platform construction as a whole with the roughly $850 million of capital deployed at roughly an average of 11% EBITDA, you can kind of back into the math.” Backing into the math, an average deal of roughly $28MM against targets of the disclosed size and margin profile implies an entry multiple of approximately 7x to 9x EBITDA, or roughly 0.9x revenue.
The compounding loop is simple to state and hard to replicate. Midera buys niche, mostly family-owned equipment makers in bilateral deals at an estimated 7x to 9x EBITDA, businesses averaging roughly 11% margins at acquisition. It then grows them (acquired revenue has compounded at roughly 4% organically) and lifts their margins toward the platform’s mid-20s over the holding period, which more than doubles the EBITDA on the same purchase price. The effective multiple on matured deals falls toward 3x to 4x, while the public market values the resulting platform at 10x to 13x and strategic buyers have paid 14x to 17x for scaled assets in this exact niche.
Comps trade at 10.3x 2027 EBITDA.
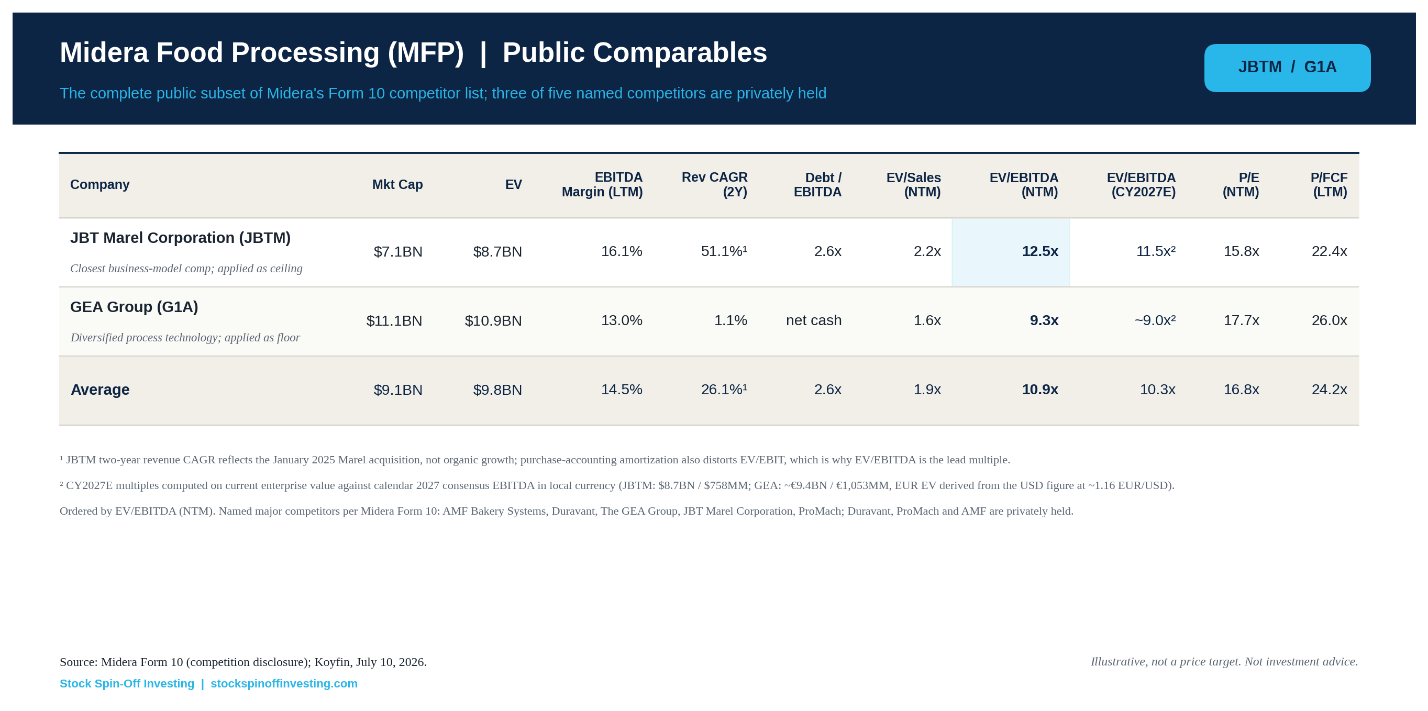
I believe MFP deserves to trade at the high end of the peer group (11x 2027 EBITDA) which implies a ~$48 price target and modest upside.
Longer term, the story gets more interesting.
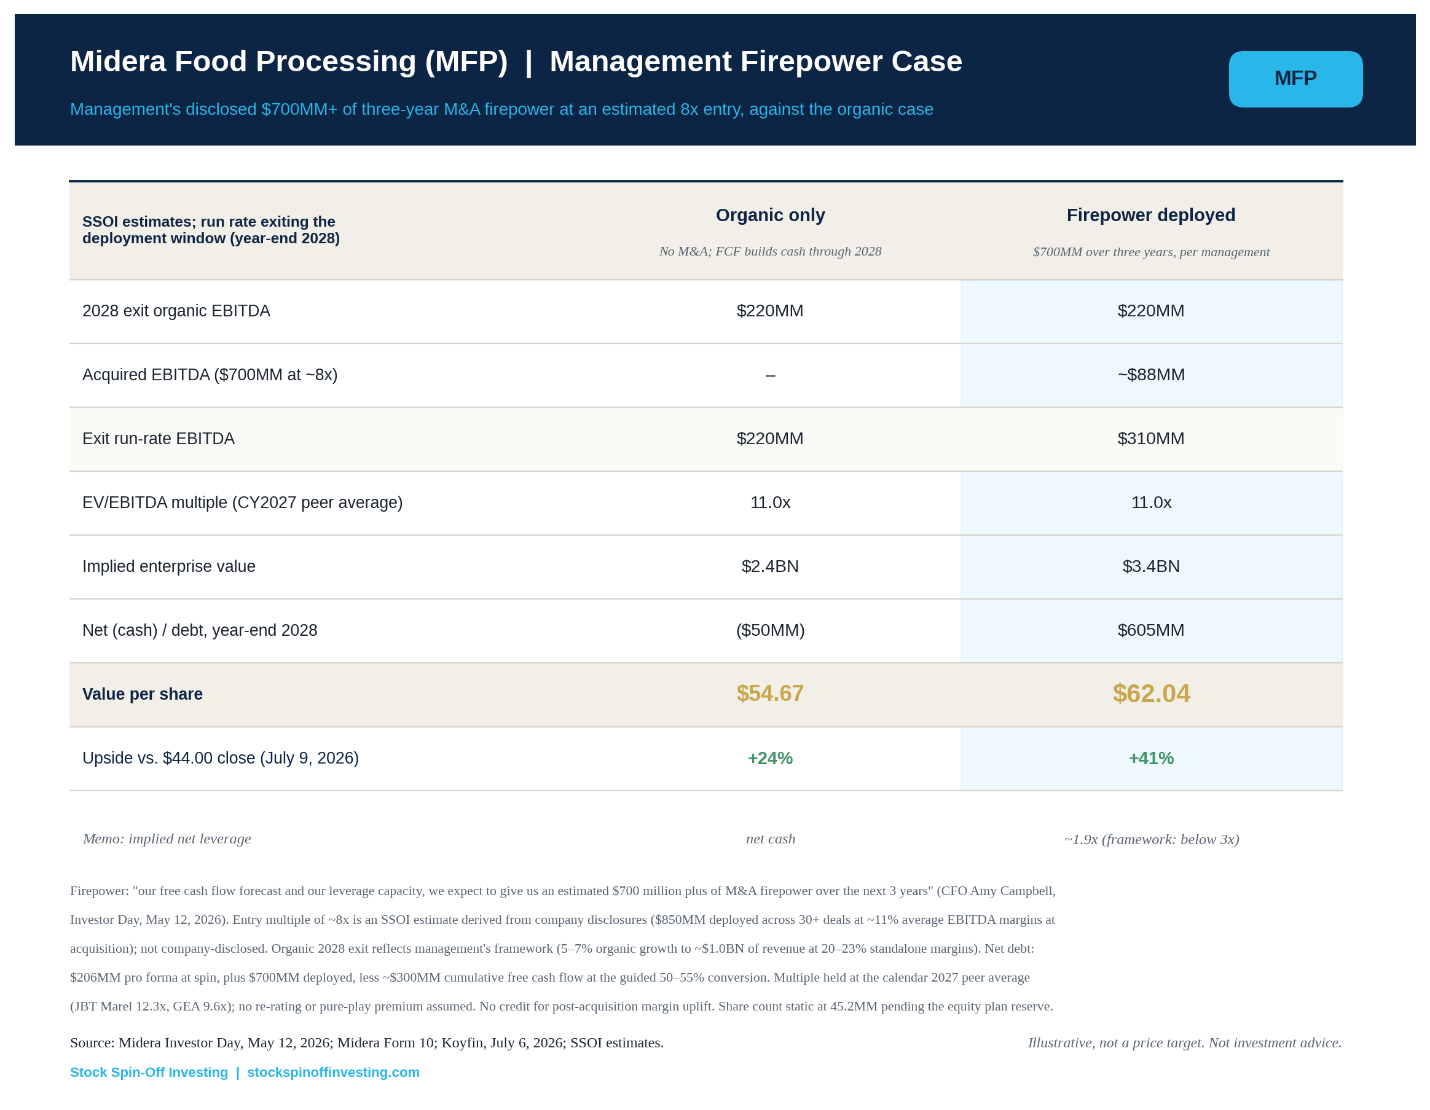
At the 5/12/2026 Investor Day, CFO Amy Campbell indicated that free cash flow and leverage capacity give Midera an estimated $700MM plus of M&A firepower over the next three years.
Assuming the company deploys that full amount at 8x EBITDA, consistent with my estimate of what it has historically paid, the acquisitions add roughly $88MM of EBITDA to an organic base that reaches approximately $220MM by 2028 under management’s own framework, for an exit run rate of about $310MM.
At the same 11x multiple, net of an estimated $605MM of year-end net debt, the stock would be worth approximately $62 in this scenario, roughly 41% above the current price, with the balance sheet still only around 1.9x levered against the stated framework of below 3x.
Even so, I am not going to chase it here. At $44 the market has already priced in a year of management’s framework, and the remaining upside rests almost entirely on acquisitions that have yet to be announced. I would rather wait. Any broad market volatility, or a stumble on the first standalone earnings, might create an attractive buying opportunity.
Spin-off Links
Kingdom Capital Q2 2026 Letter
- Not spin related but good quick write-up on Entravision (EVC)
Podcast: Jeremy Giffon – The Billion Dollar PDF
- People have been raving about this podcast.
- Looking forward to listening.
VIC Write-up: Wickes Group (must create a free account to access)
- 2021 UK spin-off. Looks cheap.
Spin-off Calendar
Upcoming Spin-off Calendar | Completed Spin-off Calendar
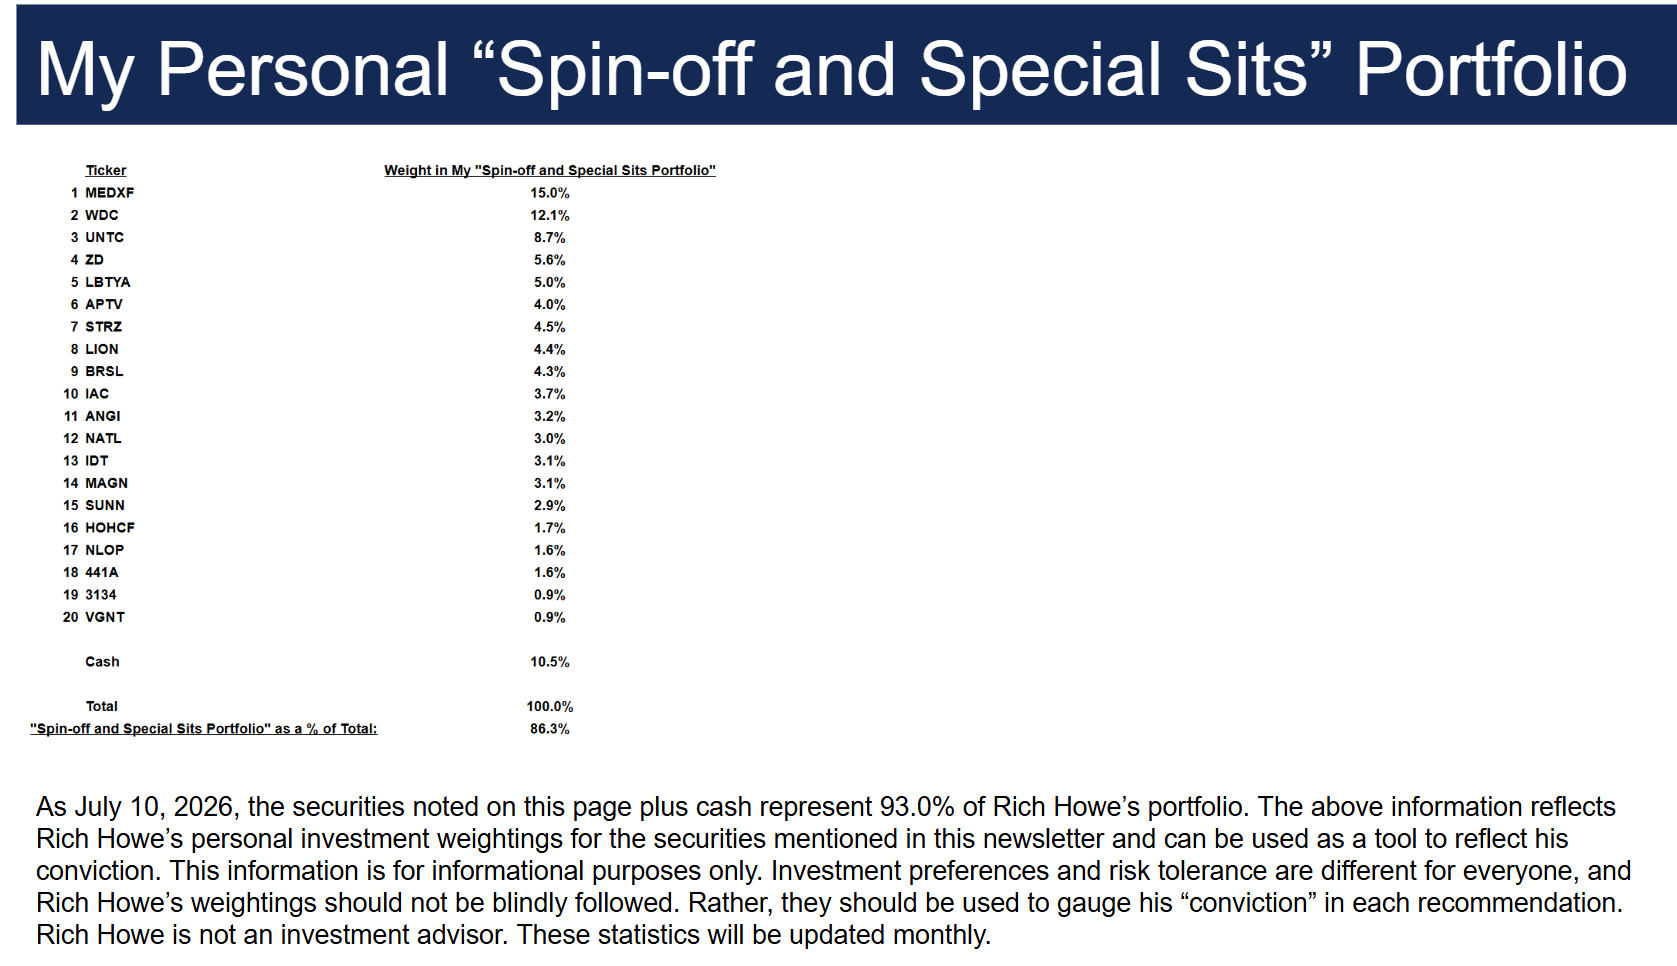
Current Positioning
(updated once a month)
Hope you had a great week!
Rich
Disclaimer:
Rich Howe, owner of Stock Spin-off Investing (“SSOI”), currently is long IDT, MEDXF, IAC, UNTC, HGHCF, WDC, MAGN, LION, STRZ, NLOP, BRSL, TSE: 3134, TSE: 441A, NATL, ZD, APTV, and VGNT. All expressions of opinion are subject to change without notice. This email is provided for informational purposes. Please do your own due diligence and consult with an investment adviser before buying any stock mentioned on www.stockspinoffinvesting.com.
Leave A Comment