

MDU Construction Services Spin-off Notes
October 9, 2024 Update
MDU Resources (MDU) will spin off its construction services business, Everus Construction Group (ECG) on October 31. MDU shareholders will receive one share of ECG for every four shares of MDU. This will be a tax free spin-off.
The construction services business spin-off provides a full range of construction services across the U.S. The two areas of focus are: 1) electrical & mechanical and 2) transmission & distribution.
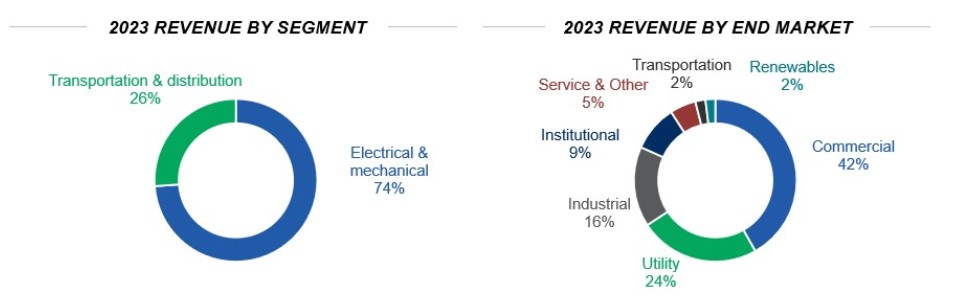
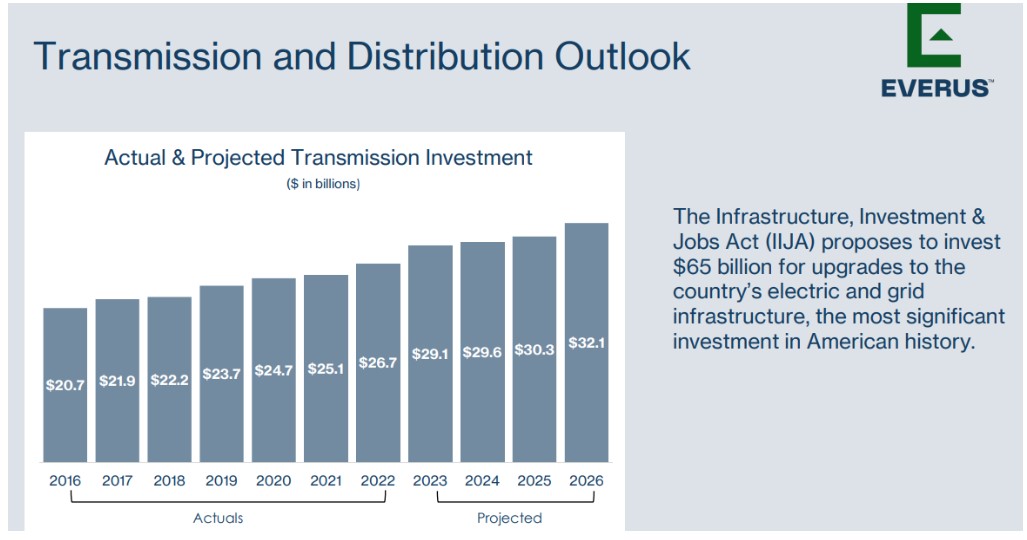
The Everus Construction business grew strongly from 2021 to 2023 (+45%) but revenue is set to decline by ~4% in 2024. The outlook for Everus is strong given strong trends in total construction starts and transmission investment.

Currently, the company’s backlog is at an all-time high of $2.4BN. In terms of a potential valuation, peers (FIX, PRIM, MTZ, PWR, MYRG) trade at 1.2x NTM revenue and 14.9x NTM EBITDA. Assuming these valuations, ECG would trade at a $3.3BN to $3.5BN EV and $3.1BN equity value.
RemainCo is a little tricky to value given it will consist of a regulated utility business and a pipeline business The company has given RemainCo net earnings guidance of $175MM at the midpoint. Utilities (~70% of RemainCo earnings) trade at ~16x forward earnings and pipeline companies (~30% of RemainCo earnings) trade at ~19x forward earnings. On a blended basis, MDU RemainCo should trade at ~17x forward earnings, implying a $3BN market cap.
Add it all up and MDU is worth ~$30/share, slightly ahead of where it trades. Everus will host an analyst day later in October, and I will finetune my analysis.
November 23, 2023 Update
MDU Resources (MDU) on Thursday, November 2, that it plans to spin off the company’s wholly owned construction services business, MDU Construction Services. This is expected to be a tax-free spinoff, completed in late 2024.
The construction services business spin-off provides a full range of construction services across the U.S. The two areas of focus are: 1) electrical & mechanical and 2) transmission & distribution.
This spin-off transaction would officially make MDU Resources *almost” a pure-play regulated energy delivery business. The only remaining “non-regulated utility” business would be its pipeline business.
Earlier this year, MDU spun off its construction materials business, Knife River.
MDU management expects the regulated utility business to generate $155MM to $165MM in net earnings in 2023. It expects the construction services business to generate $210MM to $230MM in EBITDA in 2023.
Based on my preliminary sum-of-the-parts analysis, I estimate that MDU is worth ~$24/share, implying decent upside from its current share price.
Leave A Comment