

Buy NLTX: Another Biotech Liquidation
Neoleukin Therapeutics (NLTX)
March 29, 2023
Market Cap: $35.4MM
Enterprise Value: -$42MM
Stock Price: $0.64
Target Price: $0.84
Upside: +31%
Summary
NLTX is trading at a market cap of $35MM and an enterprise value of negative $42MM. It has announced it is laying off 82% of its workforce including its president and CEO. The company is undergoing a strategy review to “maximize shareholder value.” While the company hasn’t formally announced a liquidation, I believe that is the most likely outcome. With conservative cash burn assumptions, I see 38% upside. I would buy up to a price of $0.69.
Resources
November 12, 2022 Press Release
Background
Neoleukin is a biotech that is focused on de novo proteins.
What are de novo proteins?
I don’t really know, but here’s my limited understanding…
All proteins that exist today have resulted from natural evolution or the modification of naturally occurring proteins.
Neoleukin was focused on creating proteins from scratch.
The idea was that these new, computationally designed proteins would be better equipped to fight cancer and other illnesses.
NLTX had several de novo proteins in development…
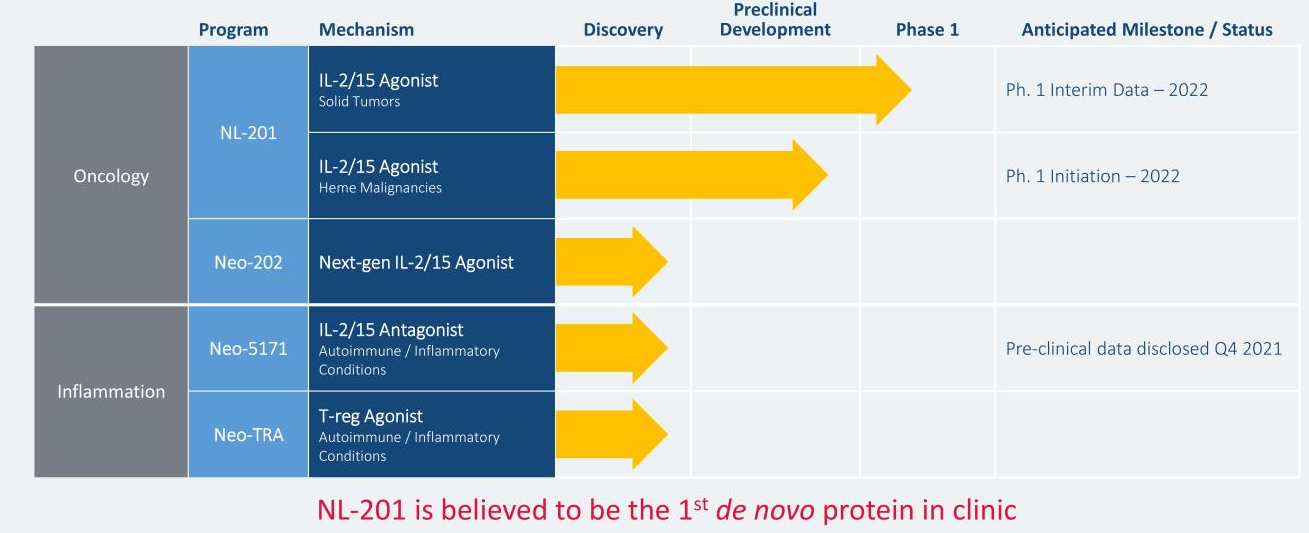
But the most promising one was NL-201.
On November 14, 2022, NLTX announced that it was discontinuing development of NL-201 as the early data didn’t indicate enough promise.
At the time, the company announced that it would cut 40% of personnel which would lengthen NTLX’s cash runway to the second half of 2025.
The plan was to focus on developing the next generation of de novo proteins.
On March 8, 2023, NLTX announced that it would cut an additional 70% of its employees including its CEO/President and review strategic alternatives.
NLTX has “engaged SVB Securities to assist in reviewing strategic alternatives for the Company with the goal of maximizing shareholder value. Such alternatives may include a sale, merger, divestiture of assets, licensing or other strategic transaction.”
The Liquidation Math
While NLTX has not announced a liquidation, I think it is likely.
Let’s start with NLTX’s current market cap.
Including 12.6MM cashless warrants outstanding, NLTX has 55.3MM shares outstanding and trades for a market cap of $35MM.
As of Q4 2022, it had net cash (current assets minus total liabilities) of $77.5MM.
In Q3 ‘22, NLTX generated an operating loss of $13MM.
In Q4 ‘22, NLTX burned an additional $10.4MM of cash.
In Q1 2023, I’m going to assume cash burn declines by 40% to $6.2MM given the restructuring.
NLTX did/will incur costs for its restructuring:
- $7.3MM (midpoint) estimate for the November 12 restructuring announcement (disclosed in 10-Q).
- $2.75MM (midpoint) estimate for the March restructuring announcement (disclosed in 8-K)
So in total, NLTX expects to incur ~$10.05MM of costs for its restructuring.
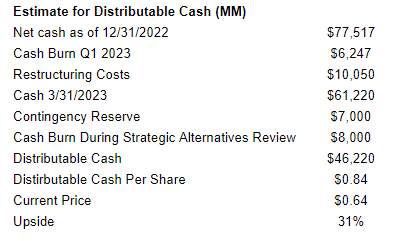
Factoring in estimated quarterly cash burn and restructuring costs, I estimate net cash at $61.2MM.
This is still significantly higher than NLTX’s current market cap ($35MM).
How much of that $61.2MM will investors actually see?
We don’t know because the company hasn’t formalized a liquidation, but if it does go down the liquidation path, I assume it will burn an additional $15MM.
Here’s how I get there:
The CEO of CBIO (former recommendation) said it costs $6MM per year to run a public biotech even with minimal employees. Let’s assume NLTX burns $8MM.
So I’m assuming the strategic review will take through the end of the year, and that the company will burn an additional $8MM during that process.
Next the reserve.
Sio Gene Therapeutics is liquidating and estimates it will have to reserve $6MM to $7MM for unknown contingencies (see below):
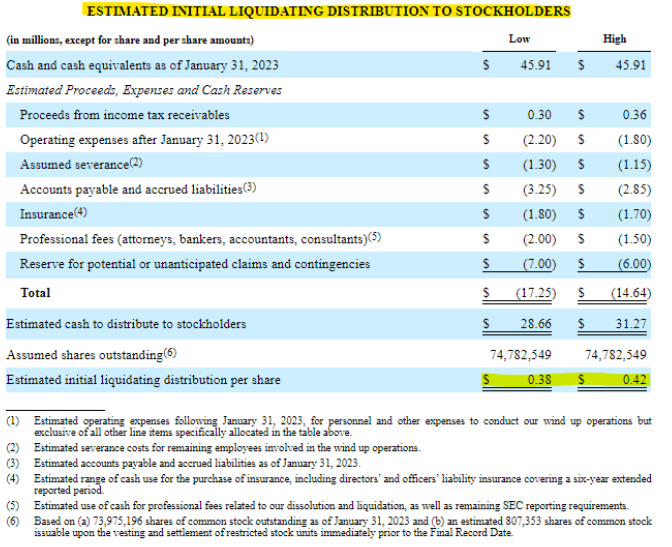
Why does a liquidating company have to reserve for unanticipated claims and contingencies?
Maybe there is a bill that wasn’t paid or a lawsuit that materializes.
Anyway, a reserve contingency is not unusual, and I think $7MM is a reasonable assumption.
Assuming NLTX decides to liquidate, I believe it will be able to payout $46.2MM or $0.84 per share.
The Upside Case
I think the liquidation math that I’ve outlined above is fairly conservative.
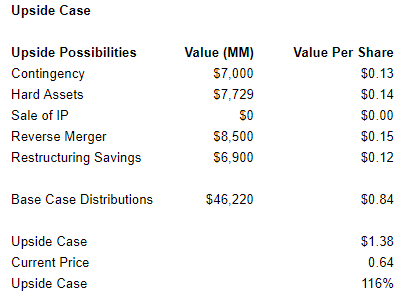
And there are some upside drivers that could materialize:
- $7MM contingency reserve.
- If no contingencies emerge, it’s likely that the contingency reserve will be distributed eventually. This would be worth $0.13 per share.
- Sale of hard assets.
- NLTX has $7.8MM of hard (non-current) assets that could be sold. This would be worth $0.14 per share.
- Sale of IP
- I think this is probably unlikely. CBIO sold its phase III hemophilia assets for just $6MM. Phase III assets are usually more valuable than earlier stage IP and NLTX doesn’t have any Phase II or III pipeline assets.
- However, CBIO did sell its preclinical complement IP for $60MM in cash. So anything is possible.
- Reverse merger.
- CBIO entered into a reverse merger and received $8.5MM of value for its shell. If NLTX entered into a similar transaction it would be worth $0.15 per share.
- Restructuring costs.
- NLTX initially estimated restructuring costs at $10.05MM ($7.3MM for the first restructuring and $2.75MM for the second restructuring). However, in the recently filed 10-k, the company reduced its aggregate restructuring estimate for the first restructuring from $7.3MM to $1.8MM (and $1.4MM of the $1.8MM was realized in 2022). If my reading is correct, this would represent savings of $6.9MM or $0.12 per share from what I’ve modeled above.
If all the upside drivers play out, distributable proceeds could reach $1.38, over 100% above the current share price.
Conclusion
I think NLTX represents another compelling biotech liquidation.
To me, it looks like a high uncertainty, low risk opportunity.
I think odds are very good that there is decent upside (20%+) from here, and a lower probability that there is material upside.
I think the risk of losing money is low (buying at current levels).
My strategy is to buy up to a price of $0.69. If I buy at $0.69, I’m expecting to generate a 21% return. Obviously the lower you buy, the better, but I plan to be patient / disciplined as this stock is a micro-cap and will be volatile.
Risks
Liquidation Doesn’t Happen
- I’m assuming a liquidation happens, but this is not guaranteed.
- If a liquidation doesn’t happen, there are still several attractive ways to win (sale, merger, etc.).
Estimates are Wrong
- My estimates could be wildly off. But I think I’ve been relatively conservative.
Company decides to continue developing drugs
- Given that 82% of the employees have been fired including the President/CEO, I don’t think this is likely.
Disclosure/Disclaimer:
Rich Howe, owner of Stock Spin-off Investing (“SSOI”), owns 3 shares of NLTX at the time of this write-up but plans to buy more over time. All expressions of opinion are subject to change without notice. This article is provided for informational purposes. We do not warrant the completeness or accuracy of this content. Please do your own due diligence and consult with an investment adviser before buying or selling any stock mentioned on www.stockspinoffinvesting.com.
Leave A Comment