

5 Takeaways from Everus Analyst Day
October 19, 2024
Summary
This week, Everus (upcoming MDU spin-off) hosted an analyst day to review its business prospects and provide long-term guidance. Today, I want to share 5 key takeaways from the event.
Resources
Form 10 – September 2024
MDU September Presentation – September 2024
MDU Investor Relations – October 2024
(1) The Basics
On October 31, 2024, MDU Resources (MDU) will spin off its construction services business, Everus Construction Group (ECG).
MDU shareholders will receive one share of ECG for every four shares of MDU. This will be a tax free spin-off.
(2) Revenue Mix
Everus ranks as the 10th largest specialty contractor in the United States, serving approximately 3,700 customers across more than 40,000 projects in 2023.
Everus offers specialty contracting services to a diverse set of end markets across the United States
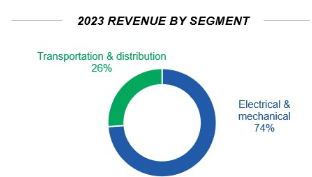
About ¾ of revenue comes from the electrical & mechanical segment while the balance comes from transportation & distribution.
(3) Everus is very diversified by end market
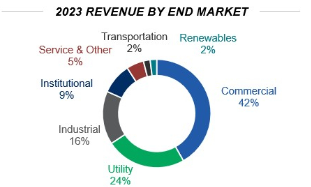
One thing that management touted during the analyst day was that the business is very diversified by end market.
This graphic shows that nicely.
(4) Historical growth has been strong and should continue
From 2021 to 2023, revenue grew at a 10.8% CAGR.
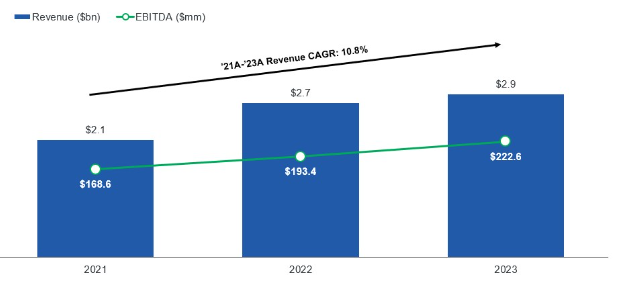
Construction revenue through the first half of 2024 is down 11% driven by tough comps in hospitality, but the long term outlook remains robust.
Management expects 5% to 7% organic revenue growth and 7% to 9% EBITDA growth.
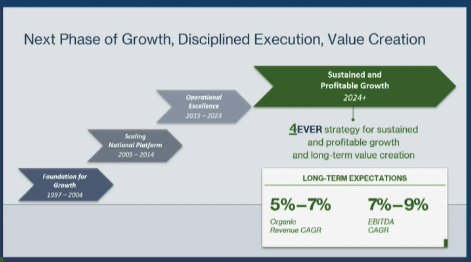
What will drive the growth?
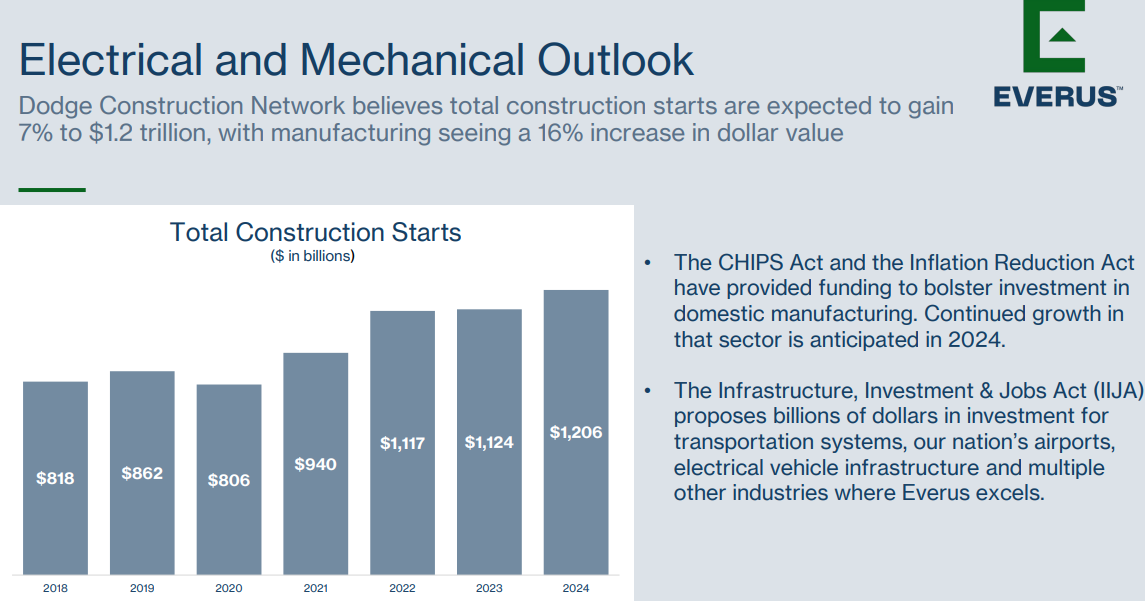
The CHIPS Act and Inflation Reduction Act are benefitting the Electrical and Mechanical segment. Data center demand (although lower margin) is a nice tailwind.
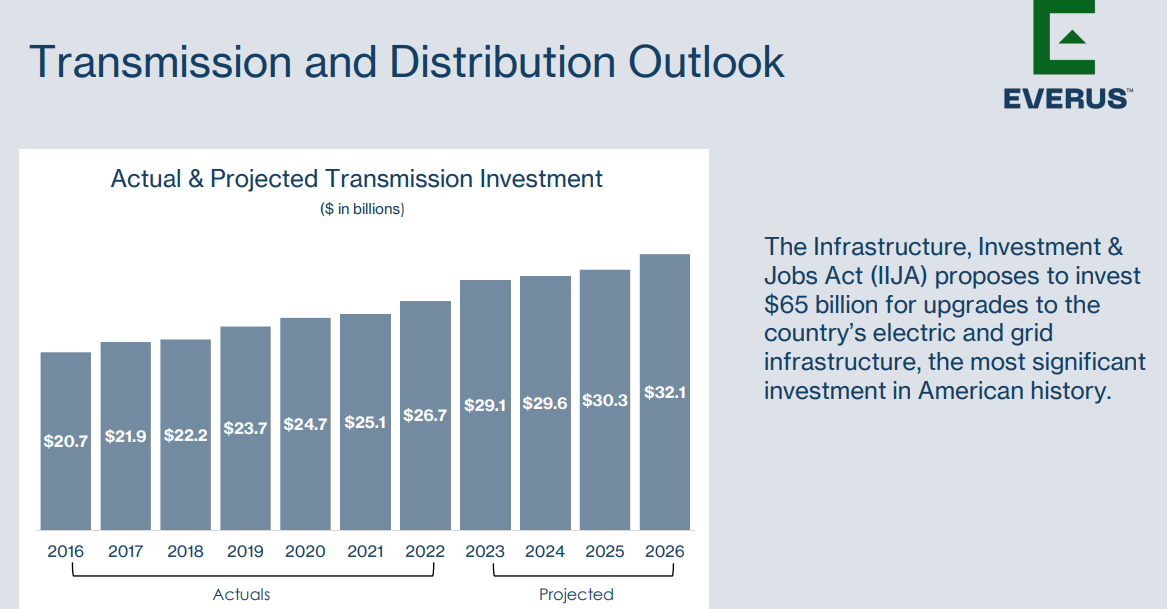
While the Infrastructure, Investment & Jobs Act are benefiting the Transmission and Distribution segment.
(5) Everus could trade at a $3.3BN market cap.
Peers trade at 1.3x NTM revenue and 15.2x NTM EBITDA.
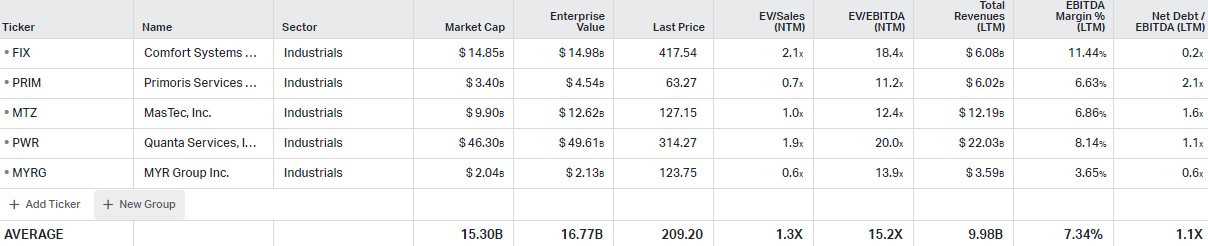
Assuming Everus trades in line with peers, it would be valued at a $3.5BN EV, $3.3BN market cap, and $64/share price.
The key question that I’m going to dig into more as the spin-off approaches is whether ECG should trade closer to PWR (higher valuation) or MYRG/PRIM (lower valuation). There is a huge difference between how those companies are valued by the market.
Disclosure/Disclaimer:
All expressions of opinion are subject to change without notice. All published emails/articles/correspondence is provided for informational purposes. We do not warrant the completeness or accuracy of this content. Please do your own due diligence and consult with an investment adviser before buying or selling any stock mentioned on www.stockspinoffinvesting.com.
Leave A Comment