

How much FCF will Unit Generate in 2023?
April 6, 2023
Unit is Cheap on Trailing Numbers
As it currently stands, Unit is extremely cheap on trailing numbers.
Unit generated $129MM in free cash flow last year.
At $42 per share, its market cap is $403MM.
After adjusting for the special dividend that was paid in January, Unit has $118MM of net cash on its balance sheet.
Its enterprise value is $285MM.
Thus, Unit is currently trading at 3.1x FCF and an EV/FCF multiple of 2.2x.
This seems ludicrously cheap.
But the key question is the following:
What is Unit Corp’s earnings power going forward?
Free Cash Flow Generation in 2023?
Unit Corp sold its midstream asset for $20MM in February.
As such, it only has two segments remaining: upstream and drilling.
Upstream Division
Production
Unit’s natural decline rate is closer to 10-12% but the company sold off some assets in 2022 which resulted in a sharper decline.
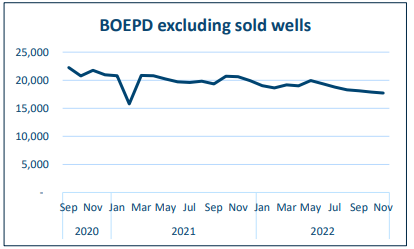
Factoring sold properties, oil production, NGL production and natural gas production declined by 22%, 18% and 17%, respectively in 2022.
I will assume the same % declines in 2023.
Energy Prices
Unit does have some hedges in place:

But for the unhedged prices, I’m assuming the following:
WTI Oil: I’m going to assume $75/bbl for oil (average price through today is $75 and futures indicate a $75-80 range).
Natural gas: I’m going to assume $2.50/Mcf (average price through today is $2.48 and futures indicate a range of $2.00 to $3.50.
Liquid natural gas: This is a little harder to get up-to-date pricing on, but a source tells me NGL’s are currently priced at $25/Bbl.
Using these assumptions, the upstream division will generate $166MM in revenue in 2023.
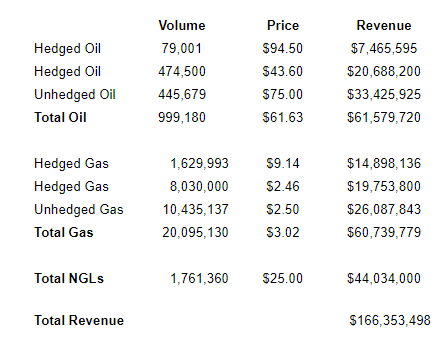
Assuming flat operating costs (perhaps conservative given lower production) of $93.8MM, the upstream division will generate $72.5MM in EBITDA in 2023.
Drilling Division
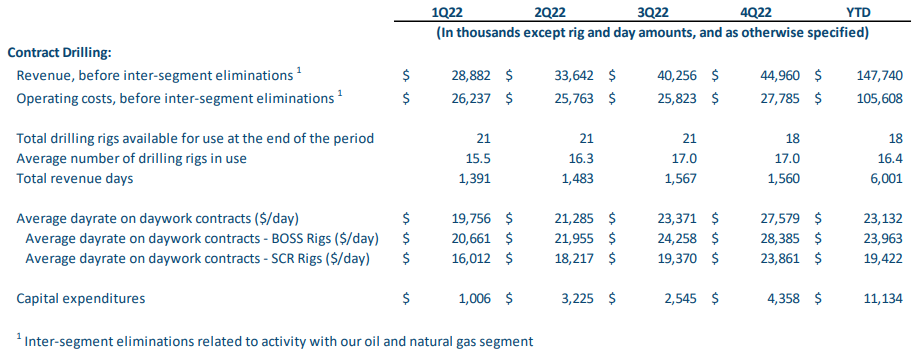
As shown above the drilling segment generated $17.2MM of EBITDA in Q4 or $68.7MM on an annualized basis.
I’m expecting $176MM in revenue in 2023. Key assumption is the BOSS day rate gets up to $32k per day. The BOSS rigs have been 100% utilized since Q2 2022 and Unit has negotiated increased day rates throughout all of 2022. I expect that to continue into 2023.
I’m assuming 90% utilization which could prove conservative given utilization has been at 100% for the past three quarters.
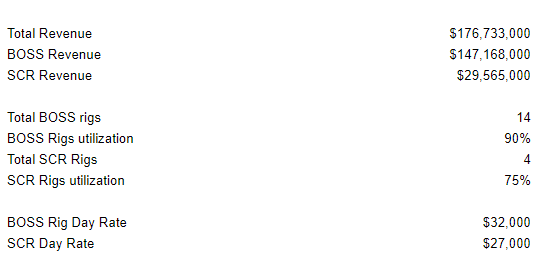
In terms of costs, guidance is that Q4 levels $27.8MM or $111.2MM on an annualized basis is a good assumption.
If this holds true, the drilling business should generate $65.6MM of EBITDA in 2023.
Putting it all Together.
Guidance for upstream capex is $10MM to $20MM (I will assume $15MM).
Last year, capex for drilling was $11MM.
G&A was $24MM last year, but I assume that falls to $20MM given assets have been sold off.
UNTC doesn’t pay taxes as it has $331MM of net operating loss carryforwards.
As such, I estimate UNTC will generate $92MM in free cash flow in 2023.
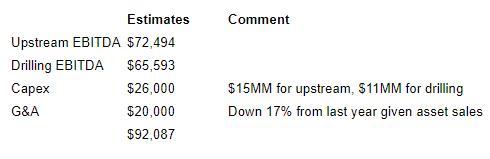
On forward numbers, Unit is trading at 4.1x FCF and 3.1x on an EV/FCF basis.
Even better, management has committed to returning cash to shareholders through regular and special dividends.
Unit Corp remains a high conviction idea for me.
If energy markets go to hell, downside is protected given Unit’s large net cash balance sheet.
If energy markets stay as they are today, the business is going to gush free cash flow.
Disclosure/Disclaimer:
Rich Howe, owner of Stock Spin-off Investing (“SSOI”), owns UNTC shares. All expressions of opinion are subject to change without notice. This article is provided for informational purposes. We do not warrant the completeness or accuracy of this content. Please do your own due diligence and consult with an investment adviser before buying or selling any stock mentioned on www.stockspinoffinvesting.com.
Leave A Comment