

Maple Leaf Foods Spin-off Notes
July 12, 2024 Update
On July 9, 2024, Maple Leaf Foods (TSX: MFI) announced that it will spin off its pork business. RemainCo will be a “brand-led consumer packaged goods company.”
The rationale for the spin-off is to “unlock value and unleash potential.” The “unlock” relates to MFI’s current valuation. MFI currently trades at 1.0x forward sales and 8.5x forward EBITDA.
The “unleash” relates to the spin-off and its ability to go after new growth opportunities.
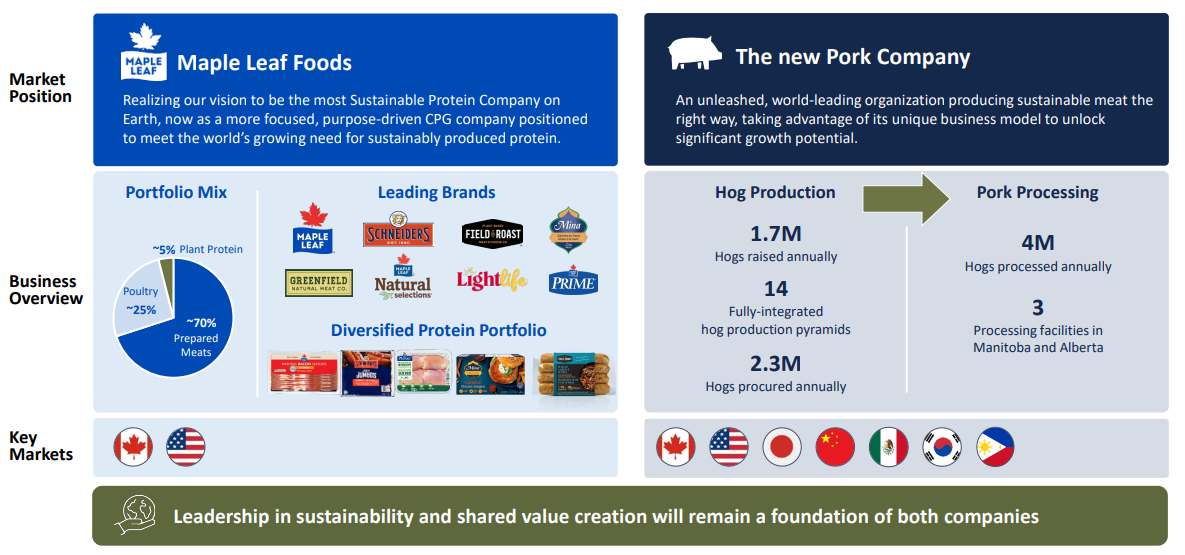
The spin-off pork company generated $1.7BN in TTM sales and $70MM in TTM EBITDA while the RemainCo generated ~$3.6BN in TTM sales and ~$395MM in TTM EBITDA. Management believes that under “normal” market conditions, the pork company will generate ~$180MM of EBITDA annually.
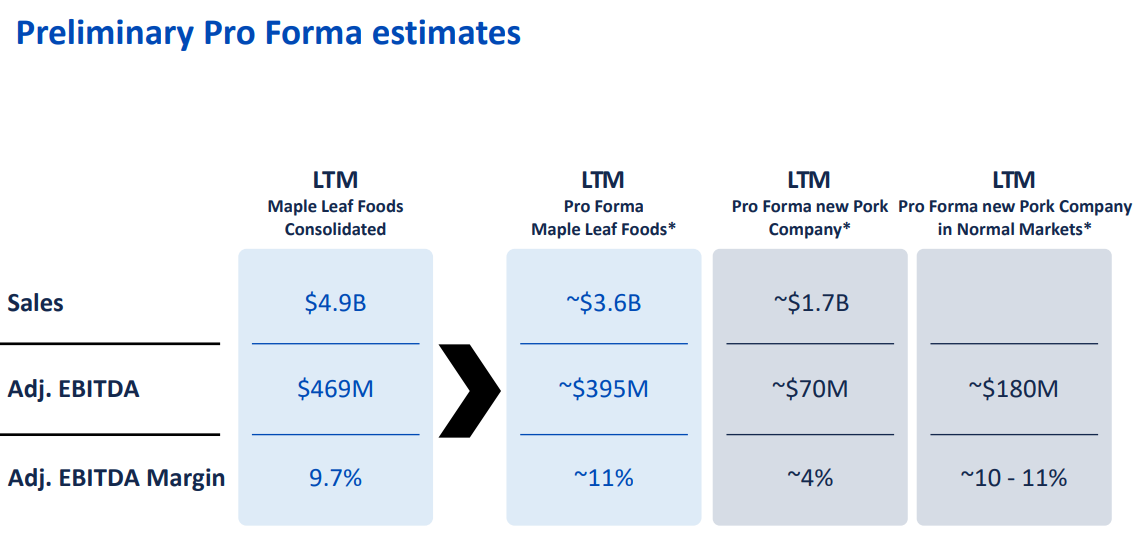
With regards to management’s desire to “unlock” value, it relates to the valuation of the RemainCo. During the the spin-off announcement, management said the following:
“So, since the beginning of time, Luke, the capital markets, for reasons we all understand, has differentiated between the upstream businesses and the downstream businesses. We have both in our portfolio. The challenge in keeping them together in this way, the way that they’ve been to date is it becomes restrictive for each one of them. The CPG company inside that mixture doesn’t have its virtues properly unlocked in the capital markets and recognized. The upstream business becomes restricted in its opportunities in capital availability to grow because the amalgamation doesn’t want to increase the exposure – the capital exposure to that upstream business when it’s combined. So, you will note that, in most other examples, a separation like this makes really good sense to both unlock the value of the CPG company and unleash the potential for growth, its own independent growth, in the upstream business. Just because they’re different doesn’t mean one is better than the other. They’re just different. And there’s many examples when – in the food industry when the upstream and the downstream businesses should be separated like this. So that’s the overarching why here. It creates opportunities and potential, I think, Luke, for both businesses.”
I intend to speak to the company to better understand the best comps, but I imagine management believes the spin-off will eventually see EBITDA recover from ~$70MM to $180MM and that it will trade inline with Tyson Foods (TSN) at ~9.1x EBITDA while RemainCo will trade inline with Hormel Foods (13.2x EBITDA). Using these assumptions, my initial SOTP valuation suggests a potential $40/share valuation.
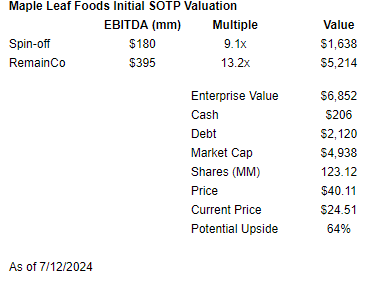
This is just a preliminary estimate and probably too optimistic. I will review my assumptions (primarily comps and dissynergies) Call transcript. Spin-off presentation. I didn’t see any mention of timing, but I expect the spin-off to be completed within 12 months.
Leave A Comment