

Weekly Update (AMS, LION, Tariffs)
April 12, 2025
This week the only thing that mattered was tariffs.
In my recommendation update section, I will provide some commentary on which recommendations are most impacted by tariffs.
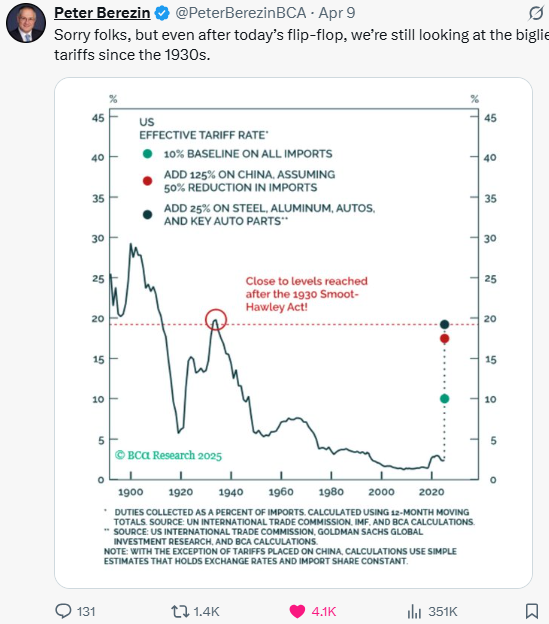
On April 9, 2025, President Donald Trump announced a 90-day suspension of increased tariffs on most imported goods, maintaining a base tariff of 10% during this period. However, tariffs on Chinese imports were raised to 125%, intensifying the trade tensions between the U.S. and China.
If the 10% tariff holds, it will still represent a significant increase relative to historic norms.
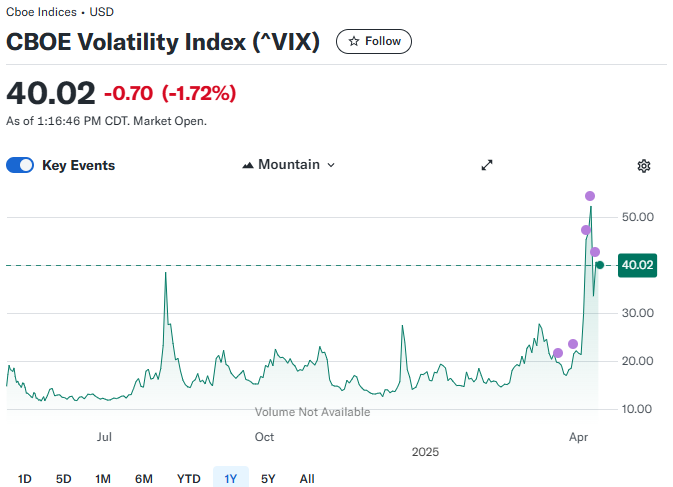
Volatility has been extremely elevated of late with the VIX surging to 60 on April 7th.
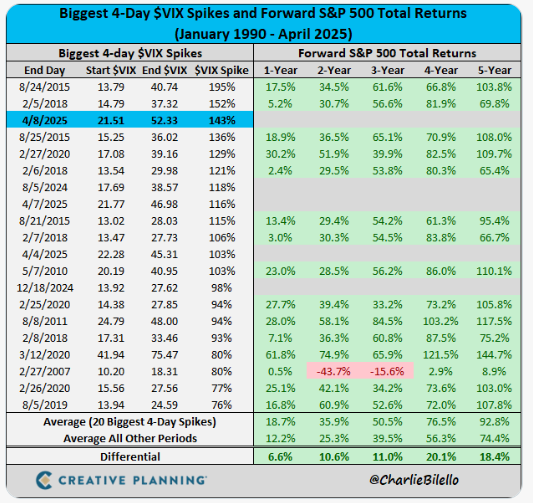
Historically, a surge in volatility is a good time to buy stocks.
I’m not necessarily interested in buying “the market” today because volatility is high, but I do think there are compelling opportunities given market dislocation. Havas (HAVAS) represents one such idea. Angi (ANGI) is another. I’m working on several other ideas.
In general, I think ex-US stocks and small cap US stocks that are insulated from the tariffs look attractive.
Now let’s move on to my regular update.
Weekly Update
If you haven’t already, consider joining our discord channel (included with your paid subscription):
Join Discord Channel (you must create a free discord account to join)
It’s basically a chat room where we discuss what’s going on in the special situation market:
Here are a few things we discussed this week:
1. Discussion on Imminent LION spin-off and RemainCo
Newly Announced Spin-offs
Due to recent market volatility, there have been no new spin-off announcements. However, this week I delved into the upcoming spin-off of Anglo American’s platinum business and would like to share the latest developments.
Anglo American (LSE: AAL) is set to demerge its South African platinum subsidiary, Anglo American Platinum (JSE: AMS), with the demerger expected to take effect on May 31, 2025. Anglo American currently owns 66.7% of Angol American Platinum. Following the demerger, Anglo American will retain a 19.9% stake in the newly independent company. This strategic move is part of Anglo American’s broader restructuring plan to simplify its portfolio and focus on core assets in copper, premium iron ore, and crop nutrients.
The demerger was accelerated after Anglo American rejected a $49 billion takeover bid from BHP in 2024. BHP’s proposal included spinning off Anglo’s South African platinum and iron ore assets. In response, Anglo American proactively restructured its operations to concentrate on commodities essential for the global energy transition.
In 2024, Anglo American Platinum reported revenues of ZAR109.0 billion (approximately $6.7 billion), down 13% from the previous year, and net income of ZAR7.06 billion (approximately $457 million), a 46% decline. The company’s market capitalization stands at approximately $9.5 billion. It is primarily listed on the Johannesburg Stock Exchange and plans to establish a secondary listing on the London Stock Exchange post-demerger.
I will be watching the spin-off closely (timing: June) for selling pressure.
Recent Spin-off
On April 1, 2025, IAC Inc (IAC) spun off Angi Inc (ANGI).
Angi operates the largest digital marketplace for home services in the U.S., connecting homeowners with contractors across Angi’s Ads and Leads platform (formerly HomeAdvisor/Angie’s List) and Services (pre-priced jobs fulfilled via Angi’s network), with
ANGI has fallen sharply with the rest of the market despite no tariff exposure.
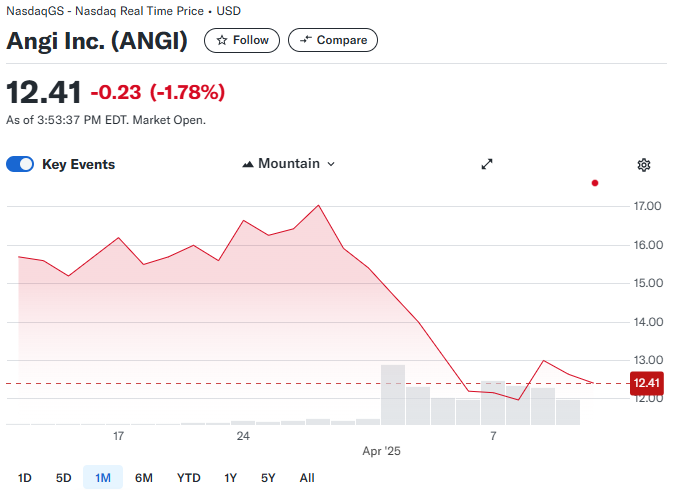
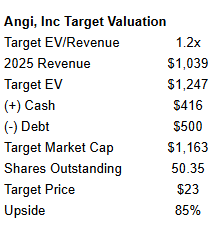
From a valuation perspective, ANGI looks very cheap trading at 0.7x NTM revenue and 5.3x NTM EBITDA.
Angi doesn’t have any perfect comps, but it is trading at a discount to its closest public comps.
I see significant upside for the stock over the next 12 months.
Imminent Spin-offs
Lions Gate Entertainment (LGF.A/LGF.B) is in the process of spinning off its studio business, Lionsgate Studios (LION) from its Starz media networks division, creating two independent public companies.
The separation will result in Lionsgate Studios Corp. as a pure-play film and TV production company and Starz Entertainment Corp. (RemainCo) as a standalone premium streaming and linear network operator.
This long-anticipated move is designed to unlock shareholder value and sharpen each business’s strategic focus, allowing the studio and Starz to pursue tailored opportunities in content production and distribution respectively.
On its last earnings call, Lions Gate management noted it expects a shareholder meeting to approve the spin-off “in mid-to-late April, with separation shortly thereafter.”
Since the earnings call, the shareholder meeting has been set for April 23, 2025. Thus, the spin-off could happen before the end of April.
LGF.A/LGF.B currently owns 87.5% of Lionsgate Studios (LION). The bull case for Lionsgate Studios is that the company is the only remaining independent studio. Typically, studios have been acquired for multiples of at least 16x.
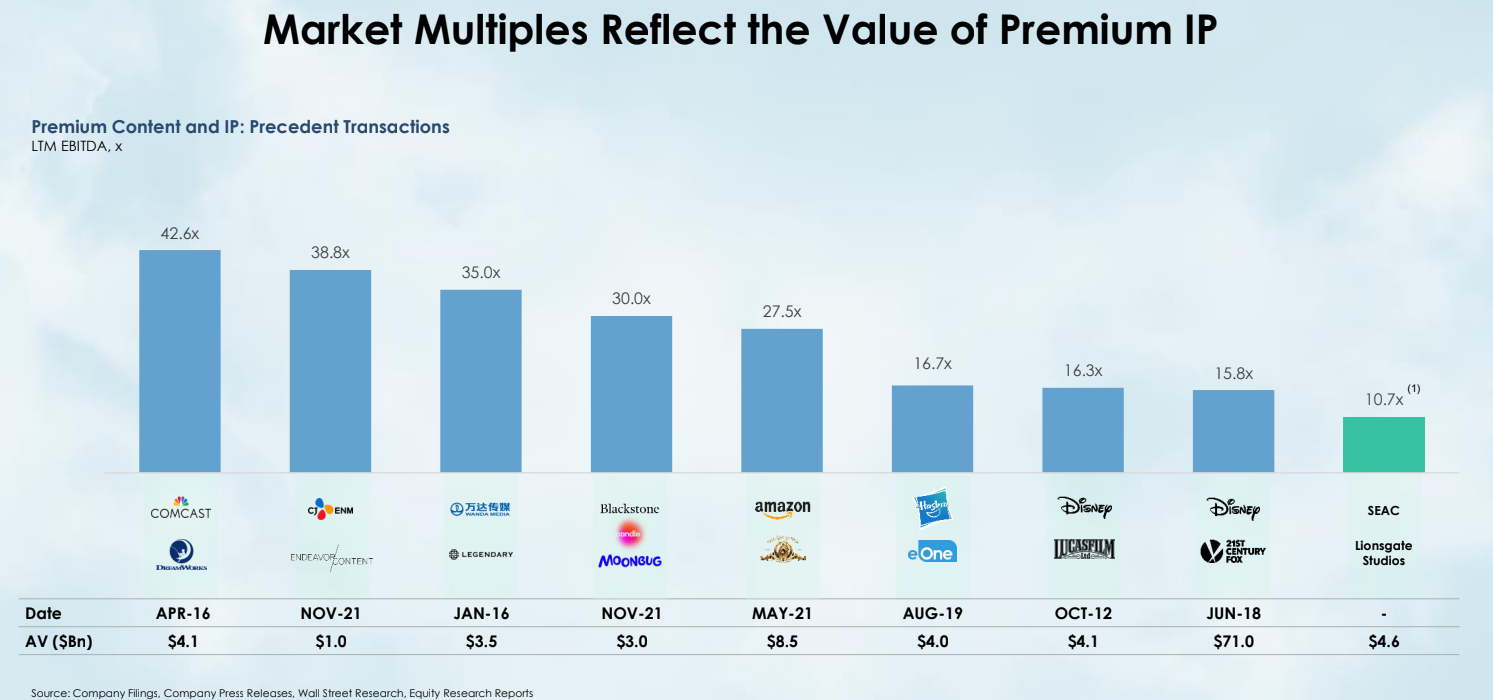
Currently, LION is trading at 12.8x NTM EBITDA.
The other interesting aspect of this situation is the RemainCo stub which will be called Starz.
LGF.A shareholders will receive 1.12 shares of LION for each share of LGF.A owned. As such, the implied share price of Starz is $0.62 or a market cap of $155MM and an enterprise value of $780MM.
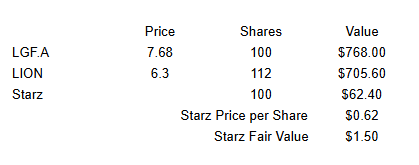
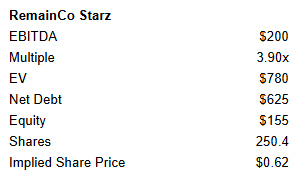
This implied valuation looks cheap. More work to do on this, but it is high on my priority list.
Spin-off Links
Anglo American intends to demerge Anglo American Platinum in May
- I will be watching this situation for selling pressure.
VIC: GALAPAGOS_NV Investment Case
- Good overview of the situation
- Spin-off will use $2BN to acquire external assets.
GDV: Preferred Spin-Off And Distribution Bump
- Gabelli Dividend & Income Fund is spinning out a preferred closed end fund.
- This needs to be approved by shareholders so I’m not adding it to my calendar yet, but it’s an interesting quirky situation which could be mispriced.
Recommendations Updates
In this section, I want to share my thoughts on which of my recommendations will be most impacted by tariffs:
(1) Magnera (MAGN)
Magnera is actually pretty well positioned for tariffs as the company has historically been able to pass through costs to customers. Furthermore, Magnera has manufacturing in North America, Europe and Asia and generally manufactures where it sells its products.
The bigger issue for Magnera would be a global recession as the company has 4.5x of leverage and slim margins. On the positive side, the Company’s nearest significant debt maturity is not until October 2029, and I’m confident the company would be able to manage through a downturn.
(2) Western Digital (WDC)
As far as I understand, the majority of Western Digital’s hard drive manufacturing is in Vietnam which is subject to tariffs. As of April 2025, the United States had proposed a 46% tariff on all imports from Vietnam, citing trade imbalances and alleged unfair practices. However, this tariff has been temporarily suspended as both nations engage in trade negotiations.
On the positive side, Western Digital does not have a meaningful manufacturing presence in China. My sense (hope!) is that a reasonable trade agreement can be made with all countries except China. I wish a reasonable agreement could be made with China, but it doesn’t look possible given the Trump administration’s rhetoric.
In terms of the financial impact, I believe the Company should be able to pass the increased cost on to the end customer. HDD has such a price advantage vs. other forms of memory (which will also be impacted by tariffs), that it will still be in high demand for data centers.
(3) Garrett Motion (GTX)
Garrett Motion (GTX) is potentially exposed to 2 set of tariffs: Mexico tariffs and auto tariffs.
The U.S. represents 20% of sales for Garrett. The company manufactures its turbo chargers in Mexico for the US market. Although Trump recently paused most of his reciprocal tariffs for 90 days, the baseline 10% tariffs remain in effect for Mexico (and all countries). I’m hopeful a reasonable trade agreement can be worked out. As of April 11, 2025, the U.S. government’s 25% tariff on imported automobiles remains in effect and has not been paused. While President Trump announced a 90-day suspension of many newly imposed tariffs on April 9, this pause does not apply to the automotive sector. The 25% tariff on imported passenger vehicles and light trucks, implemented on April 3, continues to be enforced. Additionally, a 25% tariff on imported auto parts is scheduled to take effect on May 3. Historically, Garrett has been able to pass through costs. The bigger issue for Garrett would be if the tariff issue causes a recession in the U.S. or globally as car demand would decline. Nonetheless, Garrett has just 2.5x of debt, generates significant cash flow and has a relatively flexible structure.
To date, I haven’t bought or sold any MAGN, WDC, or GTX as I’m waiting for more information from the company’s to better understand the situation.
Spin-off Calendar
Upcoming Spin-off Calendar | Completed Spin-off Calendar
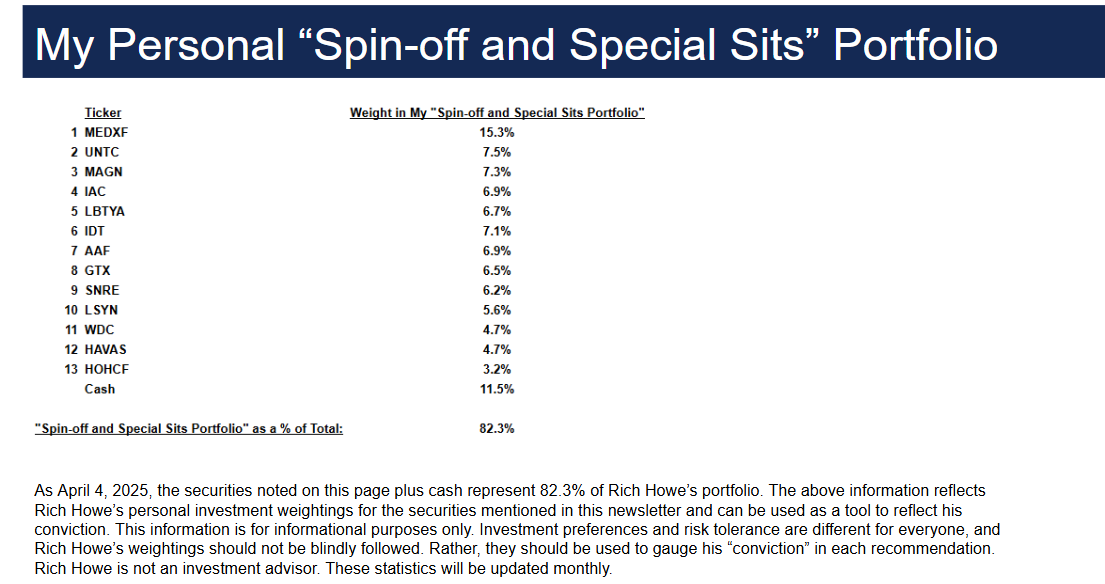
Current Positioning
(updated once a month)
Hope you had a great week!
Rich
Disclaimer:
Rich Howe, owner of Stock Spin-off Investing (“SSOI”), currently is long LSYN, IDT, MEDXF, GTX, AAF, IAC, UNTC, HGHAF, SEG, WDC, MAGN, HAVAS. All expressions of opinion are subject to change without notice. This email is provided for informational purposes. Please do your own due diligence and consult with an investment adviser before buying any stock mentioned on www.stockspinoffinvesting.com.’
Leave A Comment