

Weekly Update (IGT, RAL, FTV)
July 5, 2025
Next week, I will host my monthly update call.
The call will be on Friday July 11th at 1pm ET and you can use this link to join.
Agenda:
- Thoughts on IGT/BRSL into the special dividend and share repurchase
- Review of Recent Spin-offs: Amrize and Ralliant
- Updates on all open recommendations
- Answer your questions
Before I get into my regular update, I want to flag one thing that caught my eye this week. As shown in the chart below, market strength usually begets more strength.
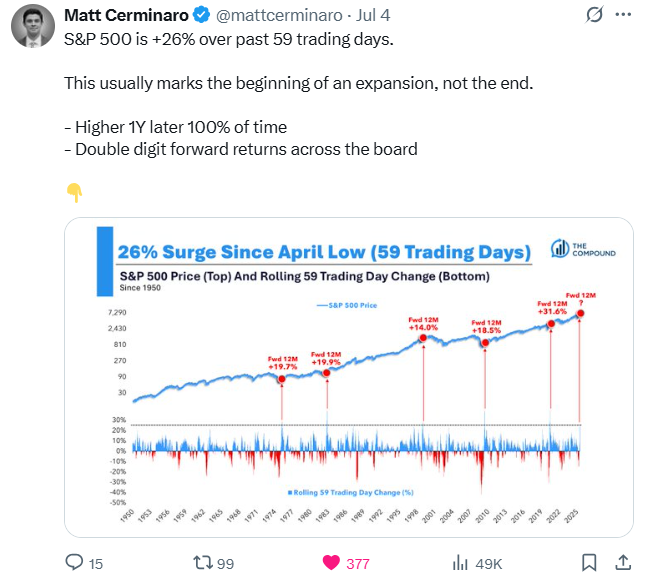
While I’m not increasing my stock purchases solely due to recent market strength—my focus remains on bottom-up, catalyst-driven ideas—I find that staying informed about market technicals provides valuable context.
Alright, let’s get into my regular update.
Weekly Update
If you haven’t already, consider joining our discord channel (included with your paid subscription):
Join Discord Channel (you must create a free discord account to join)
It’s basically a chat room where we discuss what’s going on in the special situation market:
Here are a few things we discussed this week:
(2) Great contributions and insights from members on IGT
Recent Spin-offs
Fortive (FTV) spun off 1 share of Ralliant (RAL) for each 3 shares owned. As such, Ralliant has 113MM shares outstanding and a market cap of $5.1BN and enterprise value of $6.1BN.
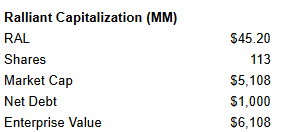
The rationale for the spin-off is to separate the “BadCo” (Ralliant) from the “GoodCo” (Fortive RemainCo).
As shown below, Ralliant has “worse” summary statistics than Fortive RemainCo.
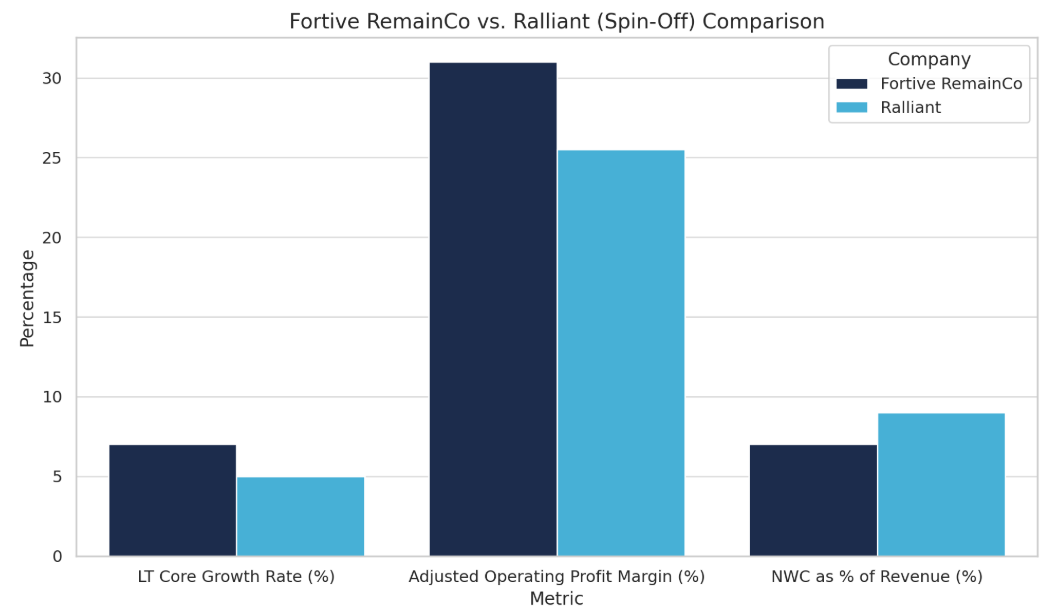
Ralliant is not that bad of a “BadCo.” I’ve seen much worse!
Ralliant’s end markets aren’t in secular decline, it isn’t highly levered, and it should be able to grow over time.
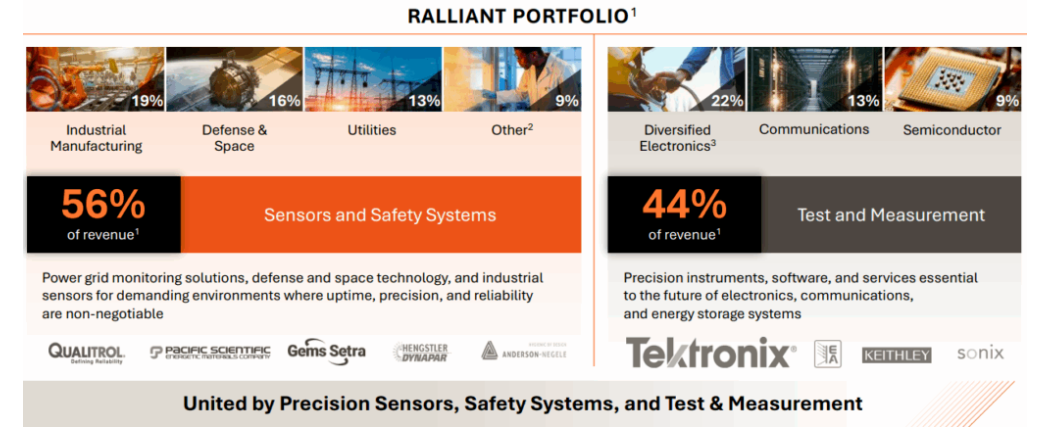
Within Fortive, Ralliant was known as Precision Technologies.
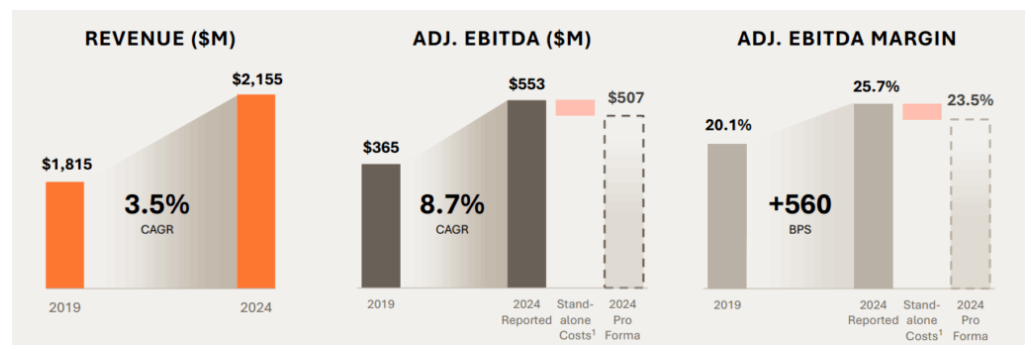
Management claims that revenue has grown at a 3.5% CAGR since 2019.
But I went back and pulled historical revenue from Fortive’s 10Ks, I got a 2.7% revenue CAGR.
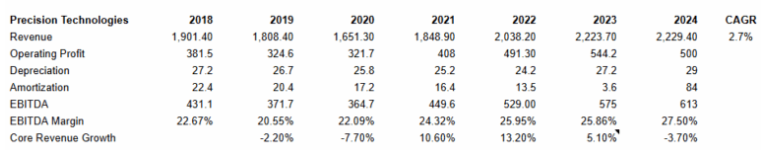
Further, I estimate that at least half of that growth was driven by acquisitions.
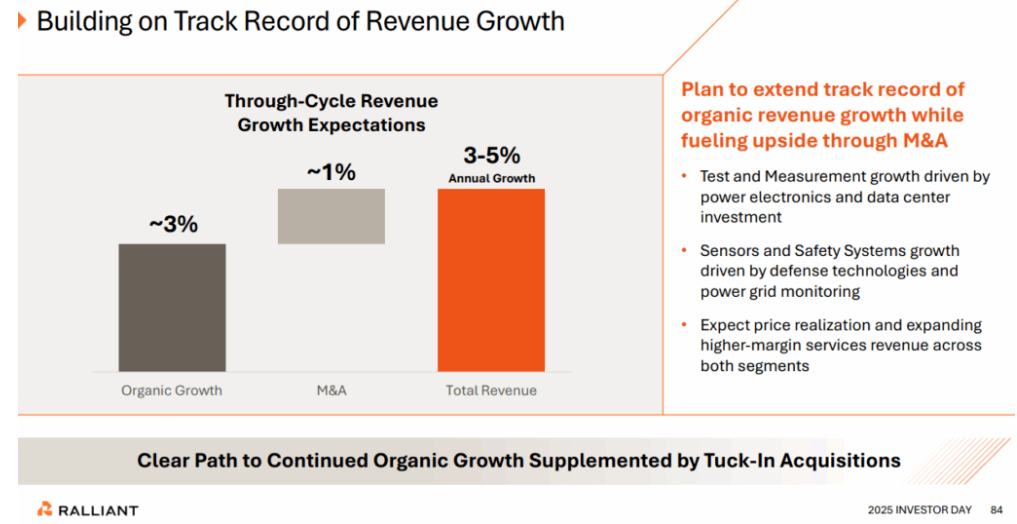
Management is guiding to ~3% organic growth going forward with an additional ~1% contribution from acquisitions.
I think this is probably optimistic.
In the most recent quarter (Q1 2025), Precision Technologies revenue declined 8.4% on a constant currency basis. This is obviously concerning.
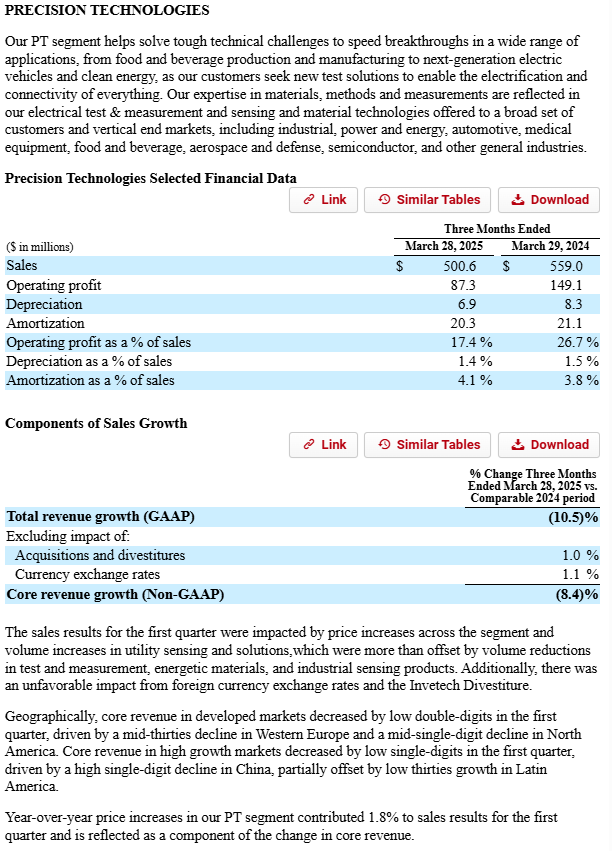
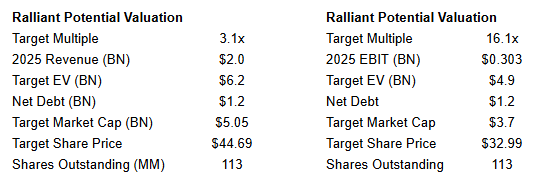
If we annualize Q1 results, Ralliant is on pace to generate $2BN of revenue and $349MM of EBIT.
The company is guiding to $46.2MM of public company expenses.
So we can decrease EBIT to $303MM.
Ralliant comps trade at 4.8x revenue and 19.8x on an EV/EBIT.
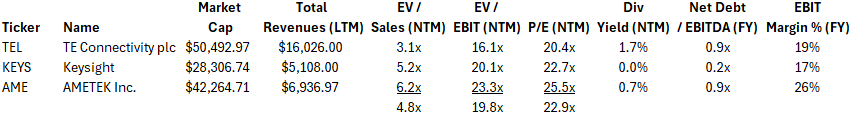
If we assume Ralliant should trade at the low end of its peer group given 1) its smaller size and 2) large decline in Q1 organic growth, the stock is worth $33 and $45.
I’m not interested in buying Ralliant today given it generated an ~8% decline in organic sales and significant margin compression in Q1 2025. This is concerning given performance was significantly worse than industry peers.
To consider buying the stock, I would need to see signs of stability (both top and bottom line).
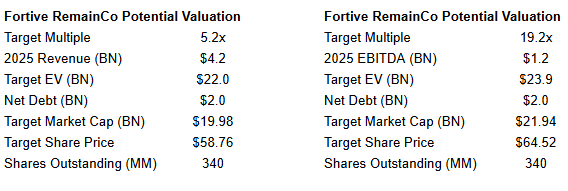
After the spin‑off, Fortive RemainCo is comprise the IOS and AHS segments (roughly $4.0–4.1B in 2024 revenue).
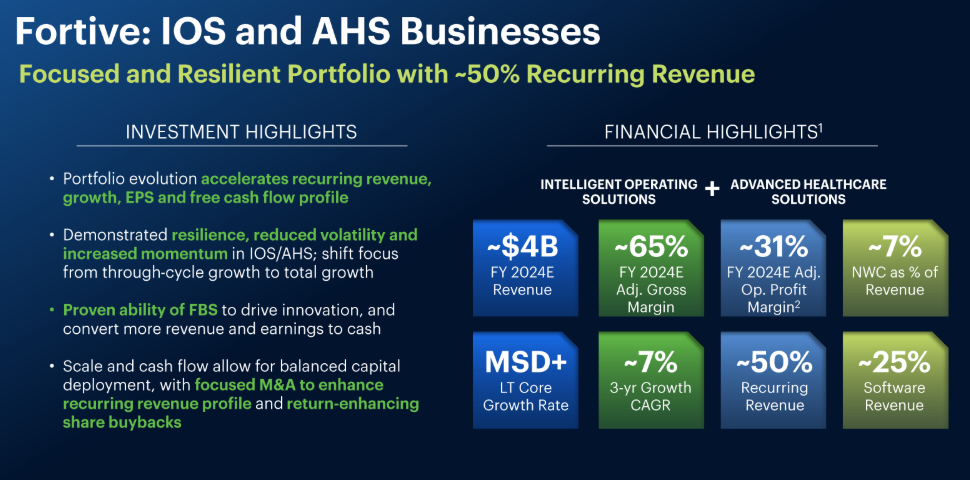
Comps include industrial automation and healthcare instruments (e.g. Rockwell Automation, Emerson, Honeywell, Agilent, Danaher).
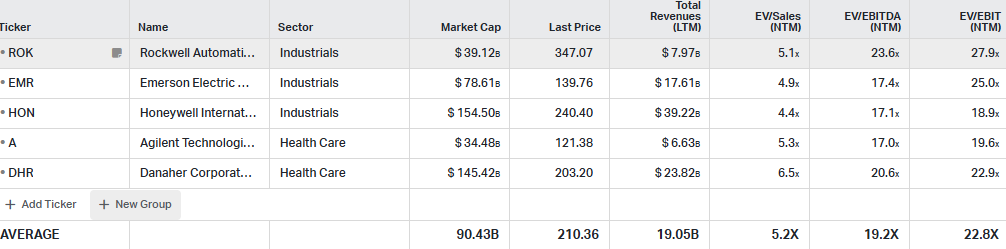
Assuming Fortive RemainCo trades inline with peers (5.2x EV/Revenue and 19.2x EV/EBITDA), it is worth between $59 and $65 (current price is $53).
Spin-off Links
Good Write-up on Valterra Platinum
- Great article on a recent spin-off from Anglo American
Why It’s Time to Buy This Rocks and Cement Spinoff Stock You’ve Probably Never Heard Of
- Barron’s likes Amrize.
Recommendations Updates
- International Gaming Technologies
This week, International Gaming Technologies announced that the Apollo transaction closed and that the company would return a significant portion of the proceeds to investors. This is the positive catalyst that I was expecting. A few points:
- IGT changed its name to Brightstar Lottery PLC (BRSL).
- Total proceeds from the transaction was $4.0BN, ahead of $3.6BN in expected proceeds ($400MM represents 11% of BRSL’s market cap).
- BRSL will pay a $3 special dividend to shareholders (record date is July 14th)
- BRSL authorized a $500MM share repurchase plan. It has signaled that it plans to be aggressive with its buybacks. Given the De Agostini family owns 42.1% of shares outstanding, the buyback will represent a sizeable portion of the float.
- I’ve heard that the dividends paid will stay the same. If shares outstanding go down significantly due to the buyback, the dividend per share will go up. Assuming IGT drops by $3 when the dividend is paid, the stock is currently trading at a dividend yield of 5.7%. Since COVID, the highest the dividend yield has traded is 5.5%.
I continue to like IGT and expect the stock to continue to perform well into the dividend distribution. It continues to trade at a discount to peers.
Spin-off Calendar
Upcoming Spin-off Calendar | Completed Spin-off Calendar
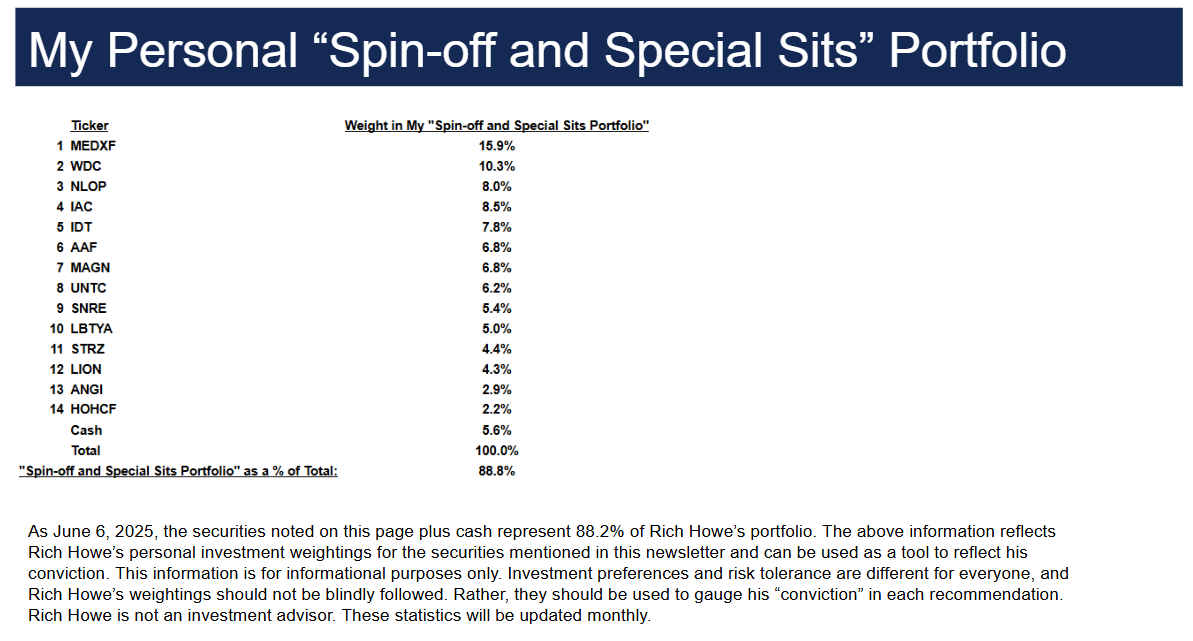
Current Positioning
(updated once a month)
Hope you had a great week!
Rich
Disclaimer:
Rich Howe, owner of Stock Spin-off Investing (“SSOI”), currently is long IDT, MEDXF, AAF, IAC, UNTC, HGHCF, WDC, MAGN, LION, STRZ, NLOP, IGT. All expressions of opinion are subject to change without notice. This email is provided for informational purposes. Please do your own due diligence and consult with an investment adviser before buying any stock mentioned on www.stockspinoffinvesting.com.’
Leave A Comment