

Weekly Update (MICC, MEDXF, STRZ)
November 15, 2025
Before I get into my regular update, I want to highlight one chart that caught my eye.
The Wall Street Journal recently published a good article highlighting that streaming costs are soaring but consumers continue to be willing to pay.
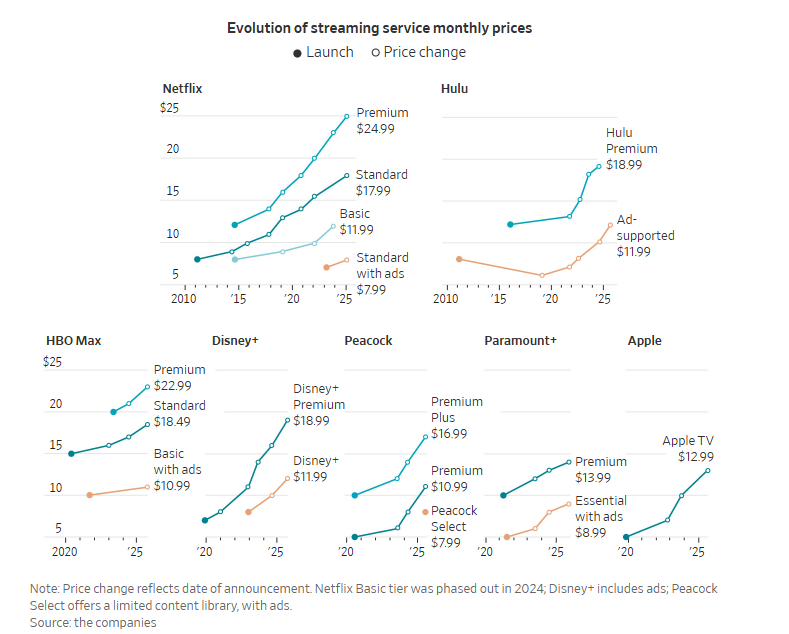
This is good news for Starz (STRZ), a pure play streaming service that is relatively cheap vs. its larger competitors.
Here’s what Starz management said on its most recent conference call:
“And as people continue to raise rate as a way to drive revenue, it creates room for us to also raise our rate because as a complementary partner, we’ve always wanted a large gap between the stated retail rate of our broad-based streaming partners versus our complementary service. And so it continues to give us the ability to raise rate if we need to.”
I continue to think Starz looks attractive. It is showing sequential revenue growth and OTT subscriber growth yet trades at 3.7x EBITDA and 2x FCF.
Weekly Update
If you haven’t already, consider joining our discord channel (included with your paid subscription):
Join Discord Channel (you must create a free discord account to join)
It’s basically a chat room where we discuss what’s going on in the special situation market.
Here are a few things we discussed this week:
- Good discussion on recent results from Medexus
- Merger arbitrage idea shared by subscriber
- Speculation on what is driving Sunrise weakness
Imminent Spin-off
Unilever (UL) has stated that the spin-off is on track to complete by December 6, 2025, with trading of The Magnum Ice Cream Company (MICC) shares expected to begin on December 8, 2025. I’m not interested in owning Unilever, but would be interested in Magnum at the right price.
The decision to spin off the ice cream segment reflects management’s desire to separate a highly seasonal, more capital-intensive, lower-margin business from RemainCo.
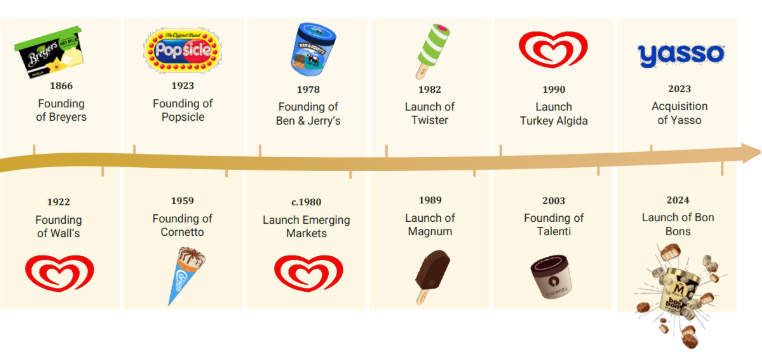
The company has been around for 160 years and has many notable brands.
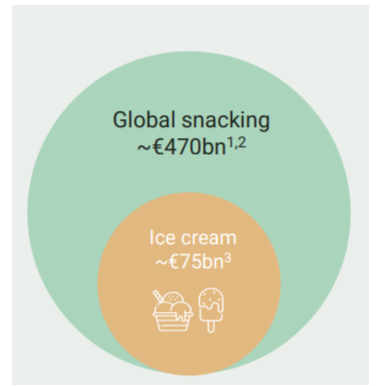
Ice cream is a large portion of the global snacking market.
It has historically grown at a rate of 3-4%…
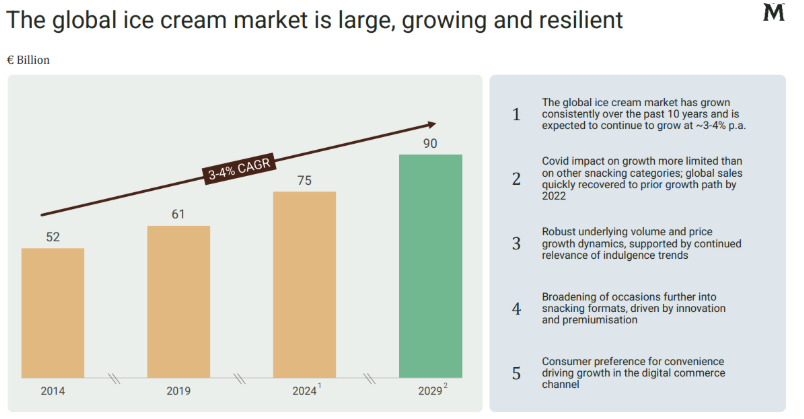
I was concerned that growth would be negatively impacted by the increased proliferation of GLP-1s, but it doesn’t seem to be having a big impact yet.
Magnum has historically grown at a 3% organic CAGR and expects to grow at 3% to 5% per year going forward.
Magnum’s business is split roughly 50/50 between At-Home and Away-from-Home.
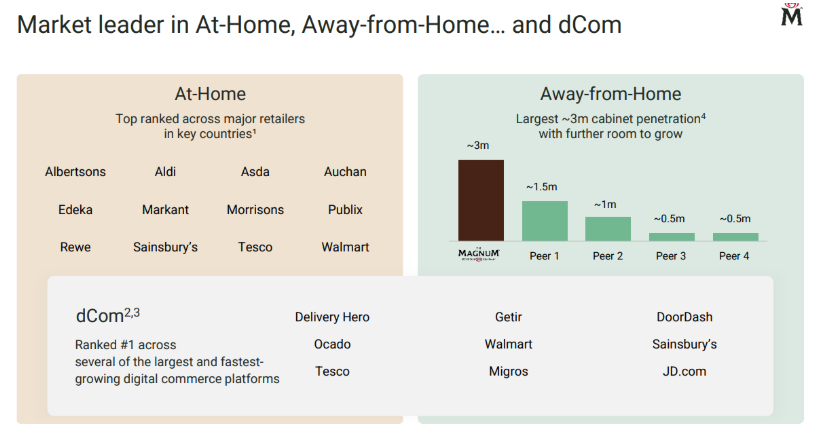
A cabinet is a commercial ice-cream freezer or display chest used to store and sell ice-cream products at retail and out-of-home locations (e.g., small shops, gas stations, beach kiosks).
These freezers are typically owned or leased by the manufacturer, not the retailer. Unilever installs and maintains them to ensure proper temperature control and prominent brand visibility (e.g., the red Wall’s logo or Magnum branding).
The company’s network of ~3 million cabinets worldwide means Magnum (and Unilever’s other brands like Cornetto and Ben & Jerry’s) have one of the largest direct-to-freezer retail footprints in the world.
Management has been doing a good job of accelerating volume growth recently…
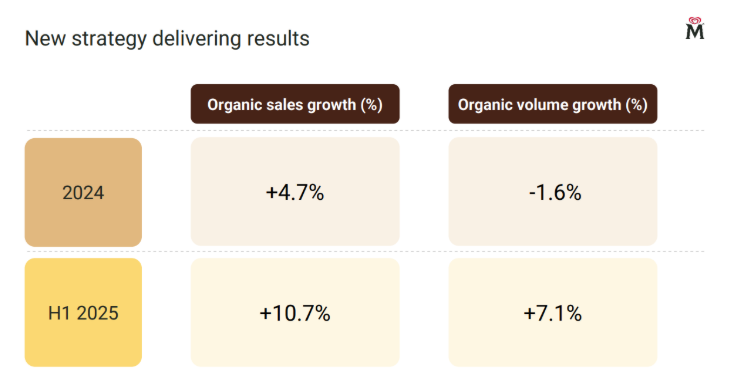
What has driven the volume acceleration?
During 2022–2023, inflation forced Unilever to push through high double-digit price increases (especially in Europe and Latin America). That depressed volumes.
In 2024, pricing stabilized (low single digits) while volumes turned positive again, meaning consumers came back to the category once sticker shock faded.
Magnum and Cornetto benefited most, with premium impulse SKUs (Magnum Double Gold Caramel, Cornetto Soft) outperforming lower-tier lines.
Management said at its analyst day that “balanced price and volume growth” was the main driver of the recent +7 % underlying sales growth.
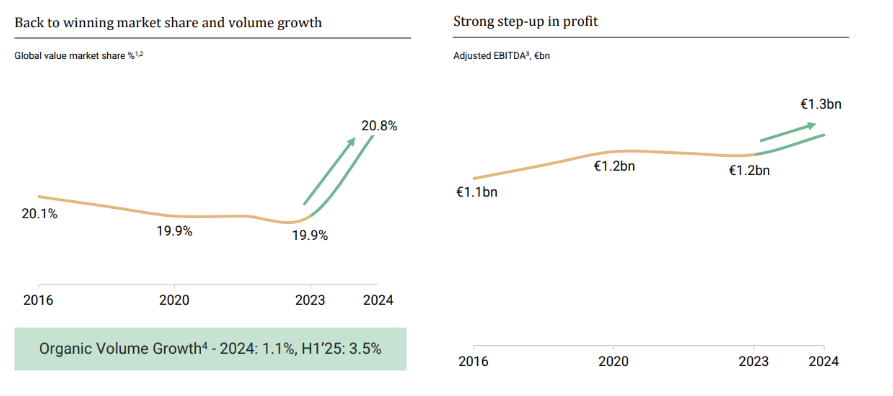
Margins have been increasing inline with volumes.
Magnum has no public pure play comps…
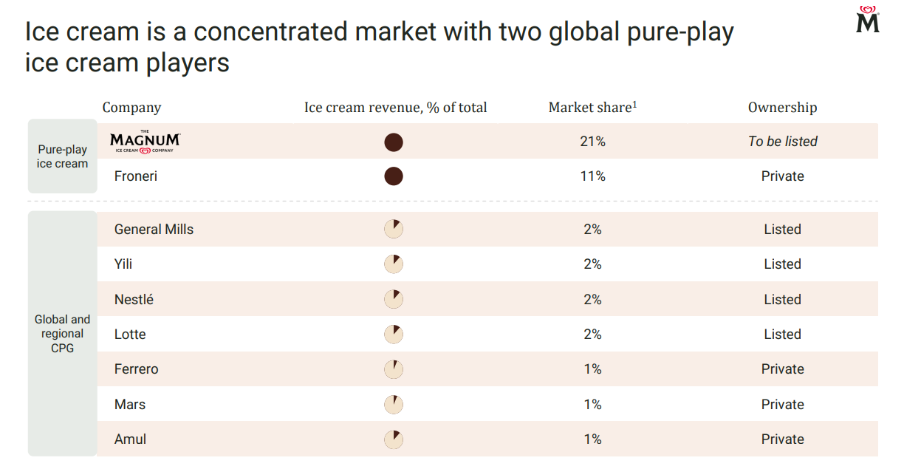
But relevant consumer staples companies trade at 13.7x EBITDA, 2.6x Sales, and 21x FCF.
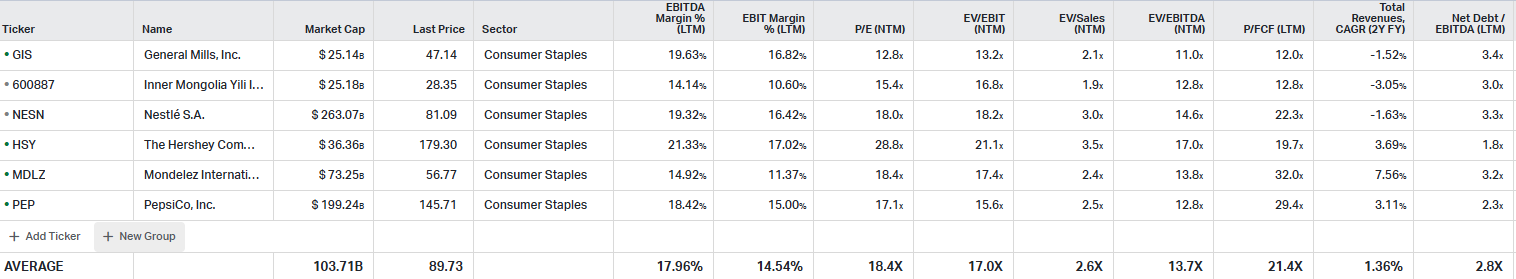
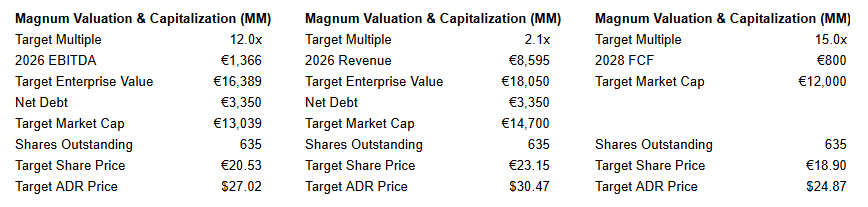
Assuming Magnum will trade at the low end of this range given spin dynamics, I estimate its worth €19- €23 and $25-31/share.
Spin-off Links
VERSANT to Host Inaugural Investor Day on December 4, 2025
- Comcast spin-off to happen before year end.
Western Digital And Seagate: Race To The Top, Progression And Navigating The HDD Market
- Good summary of the current state of the HDD market.
VIC: Teleflex Investment Case (must create free account to read)
- Good overview of imminent spin-off.
Recommendations Updates
(1) Medexus
Medexus delivered a solid fiscal Q2, highlighted by strong execution on GRAFAPEX and a clearer setup for meaningful year-over-year growth beginning in mid-2026. While reported revenue declined due to known headwinds in the legacy portfolio, the underlying trajectory is improving, with multiple drivers poised to inflect over the next few quarters.
GRAFAPEX continues to exceed expectations. October was the strongest month since launch, reimbursement progress has been highly favorable, and both pediatric and now adult adoption is building. Importantly, management updated its MD&A: GRAFAPEX is now expected to generate $100–$175 million of annual product-level revenue within five years, up from the prior $100 million estimate. This revised range equates to 27–42% share of a U.S. bone-marrow transplant market of roughly 10,000 procedures per year—a significant opportunity relative to Medexus’s current scale.
NTAP reimbursement, effective October 1, is another underappreciated tailwind. Medicare/Medicaid represents 20–30% of the total transplant market, and NTAP should meaningfully accelerate adoption in this segment. The company noted that wholesaler inventory sits at 1.5–2 months of supply, which may distort near-term reported revenue, but underlying demand remains healthy at ~$2M per quarter.
Rasuvo is also poised for improvement. With competitor Otrexup withdrawn from the market (formerly ~20% share), Medexus expects rising unit demand as competitor inventory clears. Pricing has troughed, and management sees opportunities for price appreciation as contracts renew.
IXINITY remains stable, while the Canadian portfolio should trough over the next couple of quarters.
Medexus is working to refinance its March 2026 debt maturity and expects to provide an update soon.
All in all, I think the setup looks attractive heading into next year. I think starting fiscal Q1 (quarter ending June 30, 2026), Medexus is going to be showing very strong revenue and earnings growth. At that point, I don’t think the market can ignore it (current valuation is 1x revenue and 4x FCF).
(2) Starz
Starz delivered a solid fiscal 3Q25, showing sequential revenue growth, renewed OTT momentum, and steady progress on its post-separation strategy. Management reiterated its long-term plan to expand margins to 20% by 2028, improve free cash flow conversion, and lower leverage through greater ownership of its content slate.
A major update this quarter was the restructuring of Starz’s Canadian business. The company is moving from a joint-venture model to a straightforward licensing agreement with Bell, which provides stable, incremental revenue and removes the need to operate an international service directly. At the same time, Starz is accelerating its push into owned content. Fightland, its first fully owned post-separation series, is in production with a co-commission partner nearly secured—improving economics and adding international revenue. Three additional owned titles are progressing through writers’ rooms and are expected to contribute to a goal of owning half of the slate by 2027.
Operational results were solid. Starz added 110K U.S. OTT subscribers—growth in three of the last four quarters—driven by strong engagement from Outlander: Blood of My Blood and the early premiere of Ballerina. Engagement reached a 12-month high. Revenue increased sequentially to $321M, while OIBDA of $22M declined as expected due to heavier marketing spend. Management reaffirmed its ~$200M full-year OIBDA target and expects leverage to fall to ~3.1× by year-end.
Content spending is set to decline meaningfully in 2026 and again in 2027 as the slate “de-ages” and more shows are owned, setting up structurally higher margins and stronger free cash flow.
I continue to think Starz looks attractive. Fundamentals appear to be stable yet the stock is priced for bankruptcy (3.7x EBITDA and ~2x FCF).
Spin-off Calendar
Upcoming Spin-off Calendar | Completed Spin-off Calendar
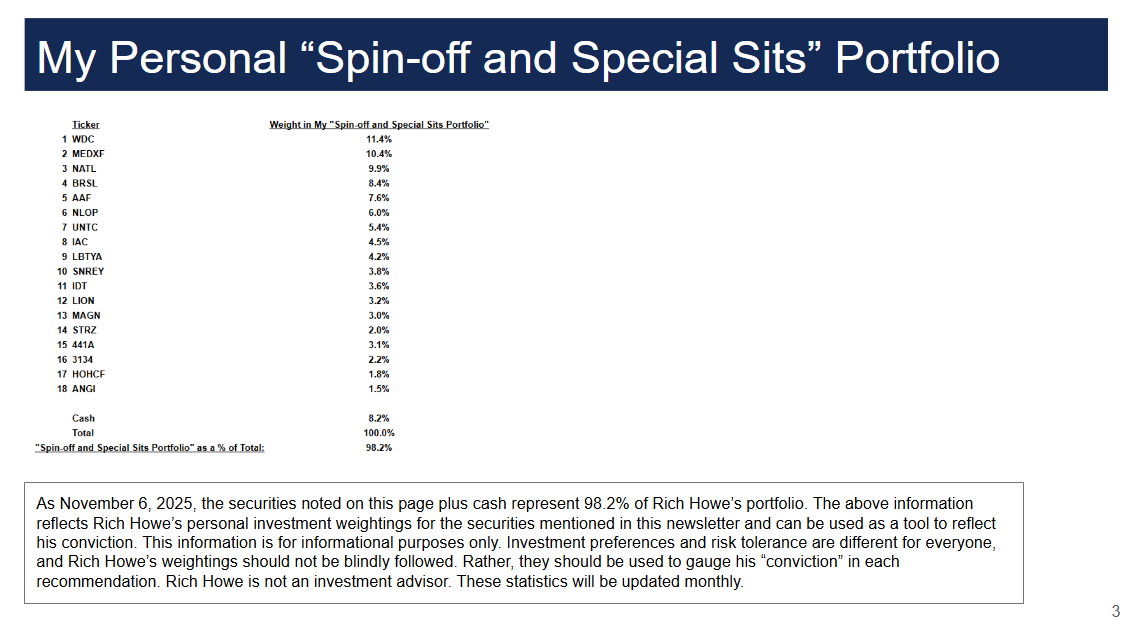
Current Positioning
(updated once a month)
Hope you had a great week!
Rich
Disclaimer:
Rich Howe, owner of Stock Spin-off Investing (“SSOI”), currently is long IDT, MEDXF, AAF, IAC, UNTC, HGHCF, WDC, MAGN, LION, STRZ, NLOP, BRSL TSE: 3134 TSE: 441A, and NATL. All expressions of opinion are subject to change without notice. This email is provided for informational purposes. Please do your own due diligence and consult with an investment adviser before buying any stock mentioned on www.stockspinoffinvesting.com.’
Leave A Comment