

Weekly Update (MIDD, SNDK, RHLD, SNRE)
March 1, 2025
Good morning,
This was a big week in the stock spin-off investing word…
On Monday, Western Digital (WDC) spun off its NAND flash business, Sandisk (SNDK).
On Friday, CompoSecure (CMPO) spun off its management company, Resolute Holdings (RHLD).
During the week, we got earnings from Howard Hughes (HHH) and Sunrise Communications (SNRE).
I also hosted an investor webinar to review my best idea for 2025. You can watch a replay here.
Next week at 1pm ET (I’m moving back the time so more people can join), I will host my monthly Zoom meeting to discuss open recommendations and recent spin-off news. Stay tuned for an invite with the agenda.
Weekly Update
If you haven’t already, consider joining our discord channel (included with your paid subscription):
Join Discord Channel (you must create a free discord account to join)
It’s basically a chat room where we discuss what’s going on in the special situation market:
Here are a few things we discussed this week:
1. Discussion of Sunrise Communications results
New Spin-off Announcements
The Middleby Corporation (MIDD) announced its plan to spin off its food processing business on February 25, 2025. This strategic move aims to allow Middleby to concentrate on its core commercial foodservice and residential kitchen equipment sectors, while enabling the new entity to focus exclusively on food processing operations.
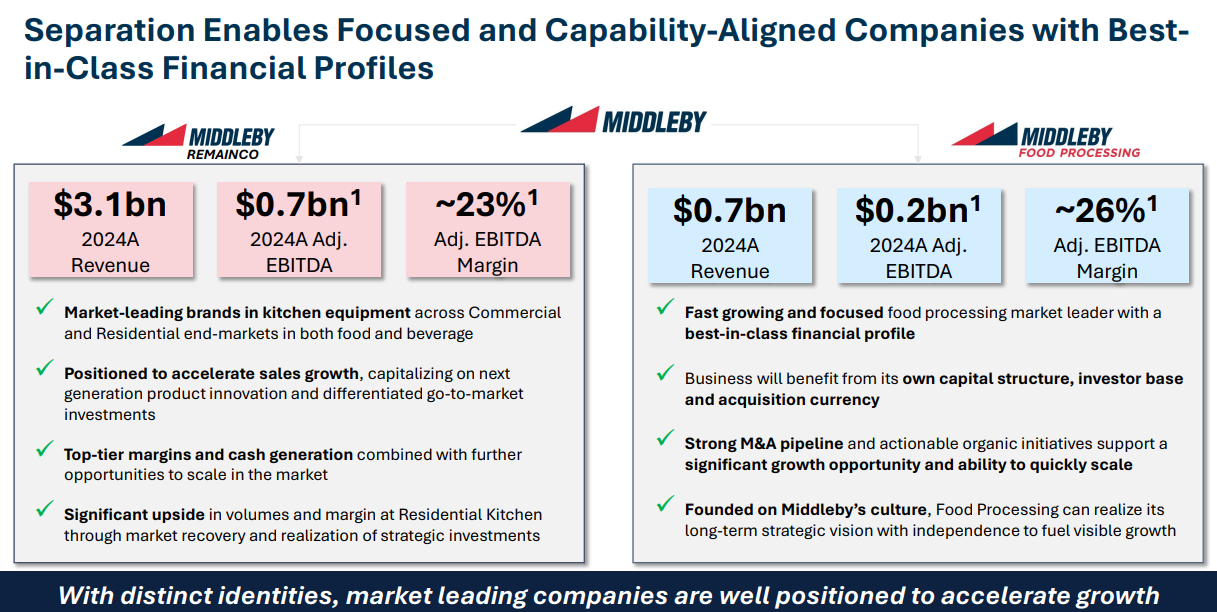
The spin-off is expected to be executed as a tax-free transaction, with completion anticipated by early 2026. The newly formed company will specialize in equipment and technologies for industrial protein, bakery, and snack processors. Post-separation, Middleby will continue to focus on its commercial and residential kitchen equipment businesses, pursuing growth through mergers and acquisitions.
The announcement was made after Ed Garden, founder of Garden Investments, established a 5% stake in the company and advocated for change.
MIDD trades at 12x forward EBITDA and 17x forward earnings. This transaction should unlock value as the spin-off, with higher margins and faster growth, should trade at a higher multiple. Analyst Mircea Dobre from Baird believes Middleby is worth $227 on a sum-of-the-parts (SOTP) basis.
Recent Spin-offs
Western Digital (WDC) spun off is NAND flash business, Sandisk (SNDK), on February 24, 2024.Sandisk opened regular-way trading $52 and has since declined to $47. At Sandisk’s current price, it is trading at 1.0x revenue.
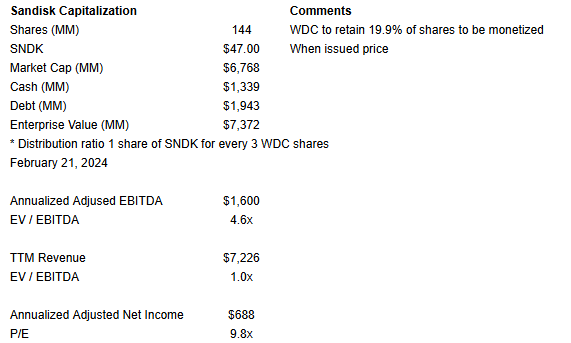
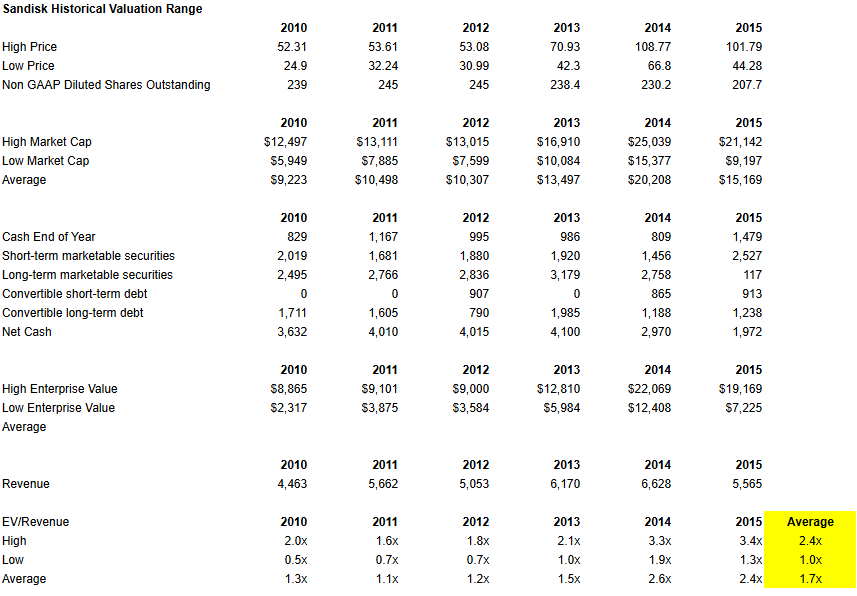
This valuation looks cheap relative to Xioxia (Sandisk’s JV partner) at 1.4x revenue and Sandisk’s historical valuation range (1x to 2.7x revenue) the last time it was a public company.
Western Digital RemainCo looks like a compelling story. It’s benefiting from secular tailwinds of increased data storage needs.
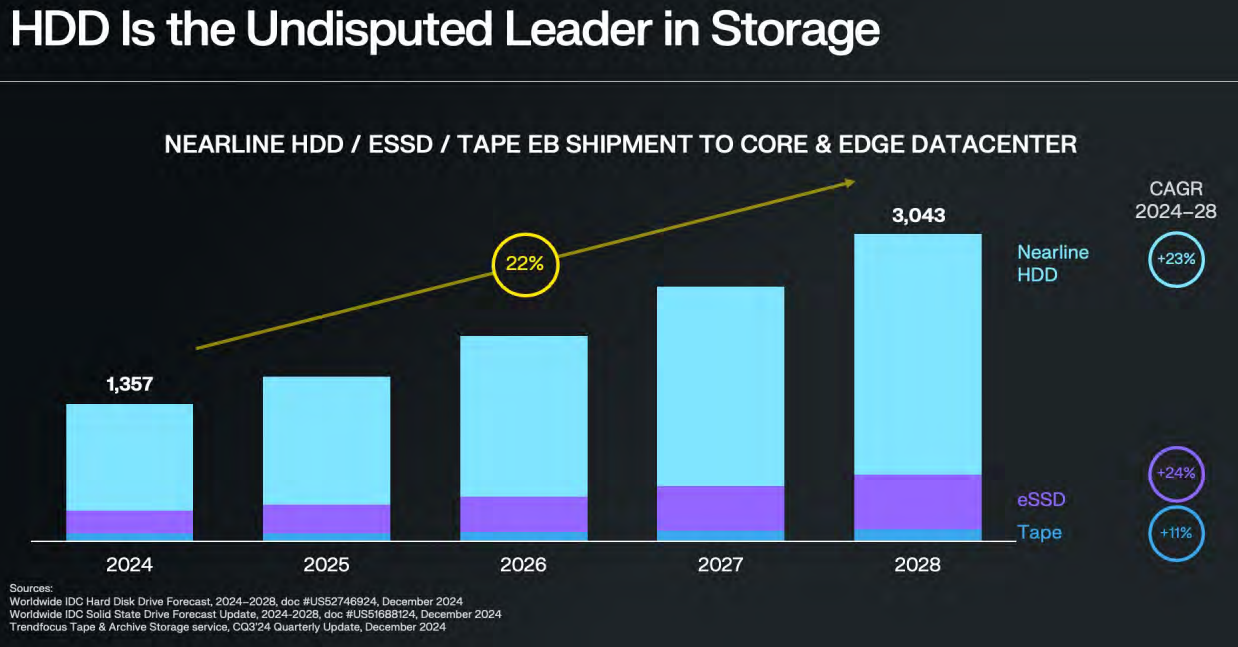
AI has not contributed much to growth but will in the next couple of years.
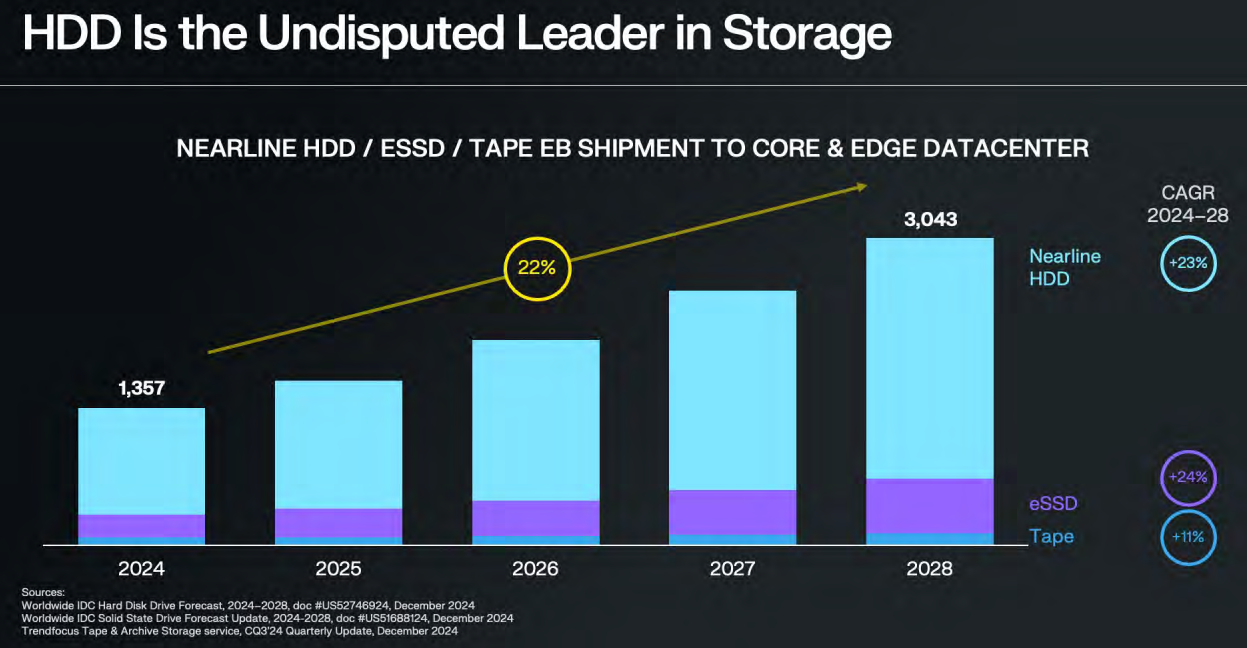
In the hard drive business, competition muted given its an oligopoly market with Seagate Technologies (STX).
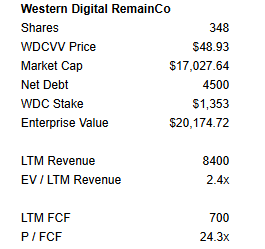
Seagate trades at 3.2x LTM revenue so Western Digital RemainCo has room for multiple expansion. The company is planning to return 100% of excess FCF to shareholders via dividends and share repurchases.
Assuming WDC RemainCo should trade inline with STX, it’s worth $68, representing 40% upside.
CompoSecure (CMPO) spun off Resolute Holdings (RHLD) on February 28, 2025.
Resolute Holdings will provide CompoSecure with services including oversight of capital allocation strategy, operational practices, and mergers and acquisitions (M&A) sourcing and execution.
Essentially, CompoSecure is spinning out a consulting team whose only customer is CompoSecure. The spin-off will be funded by a quarterly management fee funded by CompoSecure Holdings. The management fee is calculated as 2.5% of the trailing twelve month Adjusted EBITDA each quarter.
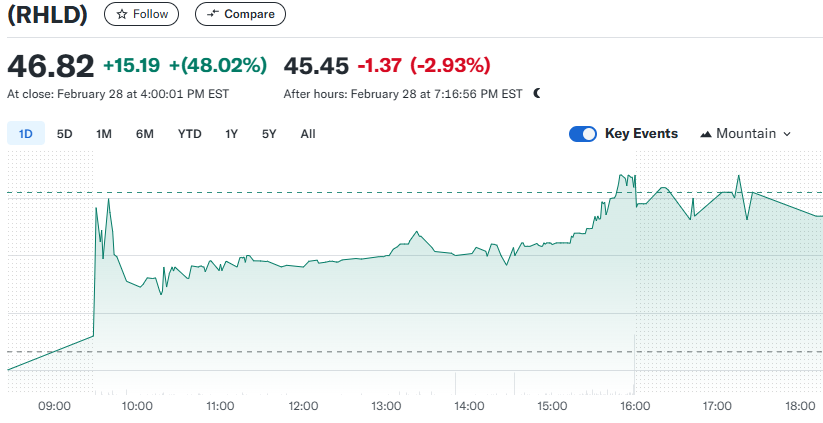
Resolute Holdings has been very volatile in when issued and regular way trading.
In its first day or regular way trading, it gained 50%.
Resolute Holdings is currently trading at a market cap of $397MM.
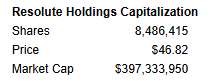
At this valuation, I’m not interested in buying the stock.
What’s the bull case?
David Cote has grand M&A ambitions for CMPO and Resolute Holdings will benefit directly from each acquisition. Resolute Holdings views itself more as an alternative asset manager. The alternative asset management industry trades as high as 30x earnings (BX), a significant premium to CMPO.
In talking to investor relations, I learned that CMPO has very significant M&A aspirations. The scope is “specialty manufacturing” which is quite broad. Looking out 5 years, I could see CMPO generating a billion in EBITDA in which case, Resolute Holdings would be generating ~$100MM in revenue and $88MM to $85MM in EBITDA (assuming expenses stay flat at $12MM to $15MM.
So assuming a 25x EBITDA multiple (because it’s basically an alternative asset manager), I could see a $2BN EV. So significant upside potential. But I don’t know if I would want to pay a $400MM market cap/EV today for it.
Imminent Spin-offs
On February 24, 2025, Lions Gate Entertainment (LGFA/LGFB) filed its latest proxy related to the spin-off its 87.5% stake in Lionsgate Studios (LION) in early Q2. You can read it here.
The spin-off is expected to take place by the end of April according to the last earnings call in February:
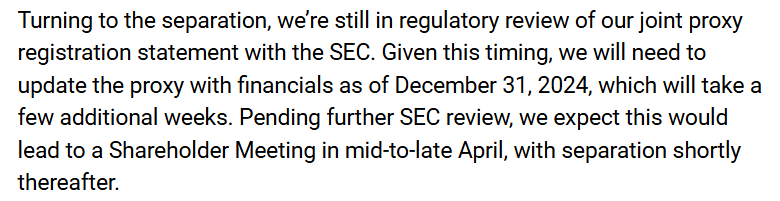
After the spin-off, LGF RemainCo will own Starz. LGF has a market cap of $2.2BN. Its 87% stake in LION is worth $2.1BN. Counting LION’s film obligation loans as debt, it is trading at 15.2x 2026 EBITDA. Historically, studio acquisitions have taken place at 16x (or higher) EBITDA. At 16x EBITDA, LION is worth $10.
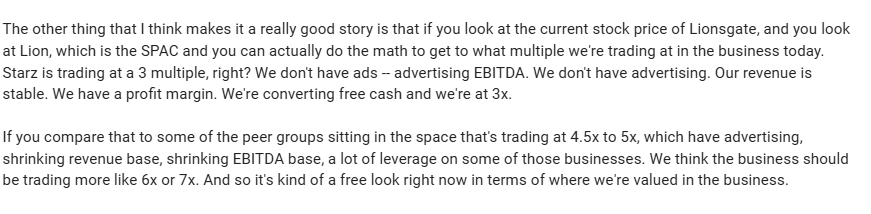
The bull case for buying LGFA is you could buy the stock today for $9.97. By the end of April, you will receive 1.12 shares of LION (per share of LFG) which at 16x EBITDA are worth $10. You will also own the RemainCo (Starz). Assuming Starz is worth 5x EBITDA, RemainCo is worth ~$1.56 per share. So you pay $9.97 today and receive $12.06 in value ($10.50 in LION value [$10 * 1.05] and $1.56 in LFG RemainCo [Starz] value).
Here’s some good commentary on where Starz management thinks the business should trade:
Spin-off Links
AI for Research: A Practical Guide for Analysts
– Good overview of AI tools that can help with investment research
Podcast: Paul Singer: Activist Investing, Market Risks and Avoiding Losses
– Looking forward to listening to this
Podcast: Bill Ackman on Investing, Politics, and Howard Hughes
– Need to listen to this
Recommendations Updates
(1) SNRE. Sunrise Communications AG recently reported its financial results for the fiscal year ending December 31, 2024. The company achieved a revenue of CHF 3,018 million and an Adjusted EBITDAaL (Earnings Before Interest, Taxes, Depreciation, Amortization, and after Leases) of CHF 1,022.1 million. These figures represent a slight year-over-year revenue decrease of 0.6% and an Adjusted EBITDAaL increase of 0.7%.
Guidance was:
- Revenue: Broadly stable compared to the previous year.
- Adjusted EBITDAaL: Stable to low single-digit percentage growth.
- Capital Expenditures (CAPEX): Expected to be 15% to 16% of total revenue.
- Adjusted Free Cash Flow (FCF): Projected between CHF 370 million and CHF 390 million.
Most importantly for me, the company announced a CHF 3.33 per share class A dividend which will be approved at the shareholder meeting in May. This dividend represents a 7.2% dividend yield which looks very attractive vs. Swisscom’s 4.3% dividend.
(2) HHH. Howard Hughes reported a strong 4th quarter.
- Net Income: The company reported net income from continuing operations of $162.3 million, or $3.25 per diluted share, up from $52.8 million, or $1.06 per diluted share, in the same period the previous year.
- MPC Performance: MPC EBT was $56.9 million, driven by the sale of 60 residential acres at an average price of $909,000 per acre, including six custom lots in Summerlin at an average price of $6.0 million per acre.
- Operating Assets: Total Operating Assets NOI was $61.2 million, a 9% year-over-year increase, with growth observed in retail, multifamily, and office sectors.
- Property Sales: The company sold Lakeland Village Center at Bridgeland for $28 million, resulting in an $11 million gain on sale.
- Financing Activities: Howard Hughes closed on $312 million of financings, including a $260 million construction loan for The Ritz-Carlton Residences in The Woodlands.
Management did not comment on the Pershing Share proposal but noted that its special committee will respond in due course. It also noted that it evaluates buying back stock vs. other uses of cash at every board meeting
Spin-off Calendar
Upcoming Spin-off Calendar | Completed Spin-off Calendar
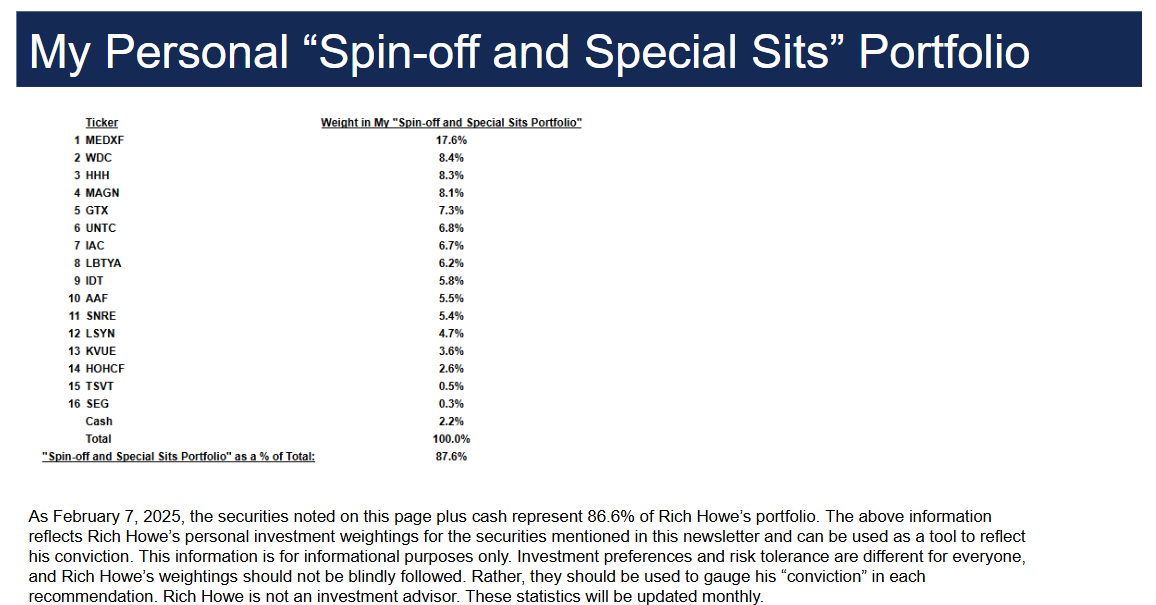
Current Positioning
(updated once a month)
Hope you had a great week!
Rich
Disclaimer:
Rich Howe, owner of Stock Spin-off Investing (“SSOI”), currently is long LSYN, IDT, MEDXF, GTX, AAF, IAC, UNTC, TSVT, KVUE, HGHAF, HHH, SEG, WDC, and MAGN. All expressions of opinion are subject to change without notice. This email is provided for informational purposes. Please do your own due diligence and consult with an investment adviser before buying any stock mentioned on www.stockspinoffinvesting.com.’
Leave A Comment