

Weekly Update (MRP, WDC, SNDK, IAC)
February 15, 2025
Before getting into this week’s update, I want to share a good chart that I found.
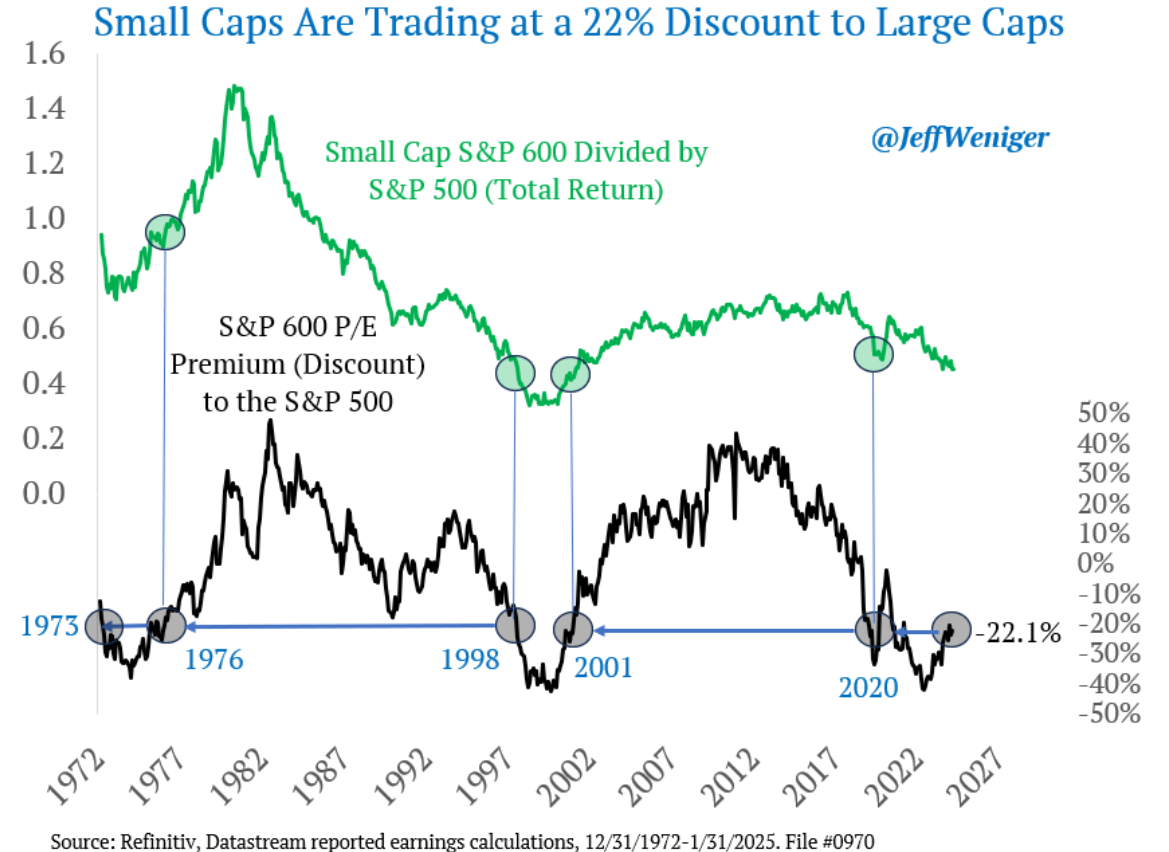
Small caps generally trade between a 50% discount to the S&P 500 and a 50% premium. The current discount is 22%. Another interesting takeaway from this chart is how long the cycles last. Relative periods of outperformance tend to last for waves of at least 13 years. The current dominance of large caps over small caps has lasted ~13 years. This suggests the cycle could be due to change.
Of course, it could go on for much longer.
The longest period of sustained large cap dominance was from 1982 to 2000, 18 years!
Top Ideas For 2025
Last call to get your top idea in!
I’m in the process of compelling top ideas from my subscribers as well as my top idea for 2025 into a PDF. I plan to share the report with you when it’s finalized.
Some guidelines:
- Just email me (rich@stockspinoffinvesting.com) a write up (target 250-1000 words) of your best idea in a word or google docs document.
- The idea doesn’t have to be related to a special situation or spin-off.
- You can submit an idea with your contact information or anonymously.
Let’s move on to the rest of my weekly update.
Weekly Update
If you haven’t already, consider joining our discord channel (included with your paid subscription):
Join Discord Channel (you must create a free discord account to join)
It’s basically a chat room where we discuss what’s going on in the special situation market:
Here are a few things we discussed this week:
1. A Swiss resident shares his perspective on Sunrise vs. Swisscom.
2. A subscriber shares his thoughts on HAVAS
New Spin-off Announcements
There were no new spin-off announcements this week.
On February 6, 2025, Honeywell International (HON) announced its plans to separate into three independent public entities:
- Automation (49% of revenue): This segment will concentrate on developing advanced automation technologies.
- Aerospace (41% of revenue): Dedicated to aerospace technologies, this division will handle Honeywell’s existing aerospace operations.
- Advanced Materials (10% of revenue): This unit will specialize in advanced materials, continuing the company’s work in this area.
The spin-off of the Advanced Materials business is expected to be completed by late 2025 or early 2026, while the separations of the Automation and Aerospace businesses are projected for the second half of 2026.
The announcement follows pressure from Elliott Management. Here is the letter that Elliott published in November 2024.
Elliott Management believes HON is worth $330 to $383 per share.
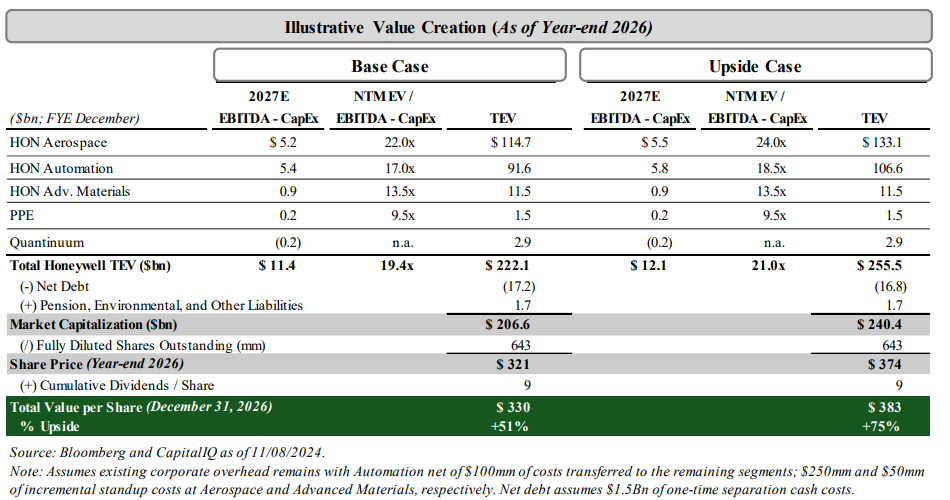
Barclays analysts have estimated a SOTP valuation of approximately $270 per share. Tony Bancroft, a portfolio manager at Gabelli Funds, suggested that the aerospace and automation businesses could be valued at $104 billion and $94 billion, respectively. However, he cautioned that it might take time for the market to recognize this value.
I think a breakup makes sense and will unlock value. However, this will take almost two years to play out and a lot could change during that time frame. The Advanced Materials spin-off will happen in 2025 but represents a relatively small portion of the value creation unlock.
Recent Spin-offs
Lennar Corporation (LEN) spun off 80% of its subsidiary, Millrose Properties, Inc (MRP), on February 7, 2025. Lennar shareholders received one share of Millrose Class A or Class B common stock for every two shares of Lennar Class A or Class B common stock
Lennar contributed ~$5.5 billion in undeveloped, partially developed, and some fully developed land assets, along with up to $1 billion in cash, to Millrose. Millrose will operate as an independent entity, acquiring and developing land to deliver finished homesites under land option contracts. Initially, it will serve Lennar but plans to engage with other homebuilders as well.
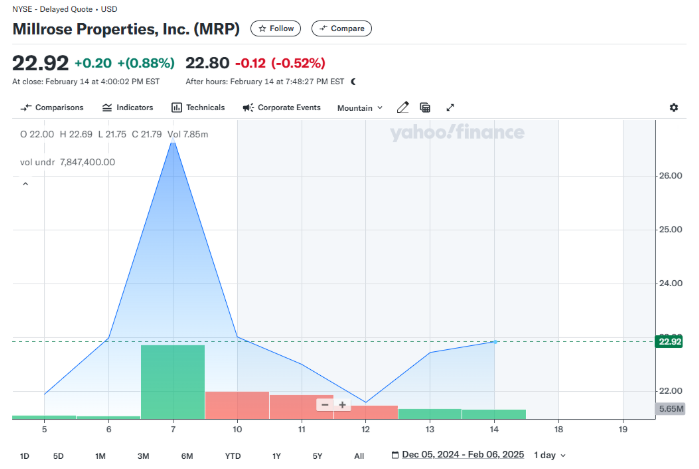
Millrose jumped right before it was added to the S&P 600 but has since sold off.
Lennar will pay Millrose option fees for the right to buy land on Millrose’s balance sheet.
This strategic move is part of Lennar’s ongoing shift toward an asset-light operating model, aiming to reduce financial risk and enhance returns by minimizing direct land ownership.
Millrose has a book value of $5.9BN and 135MM shares outstanding. It is trading at a dividend yield of 10.3% based on my estimates.
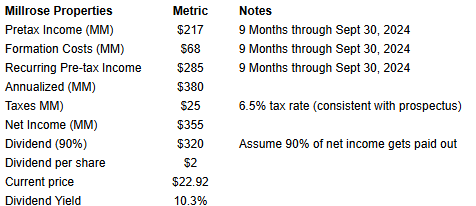
I think Millrose is appropriately valued. If it were to trade off into the mid-teens, I think it would be an attractive buy based on its dividend yield.
Imminent Spin-offs
CompoSecure (CMPO) announced that it will spin off Resolute Holdings (RHLD) within a few weeks. The first day of trading will be February 28, 2025.
Resolute Holdings will provide CompoSecure with services including oversight of capital allocation strategy, operational practices, and mergers and acquisitions (M&A) sourcing and execution.
Essentially, CompoSecure is spinning out a consulting team whose only customer is CompoSecure.
How does this make any sense?
It makes sense because the executive Chairman of the company will be David Cote.
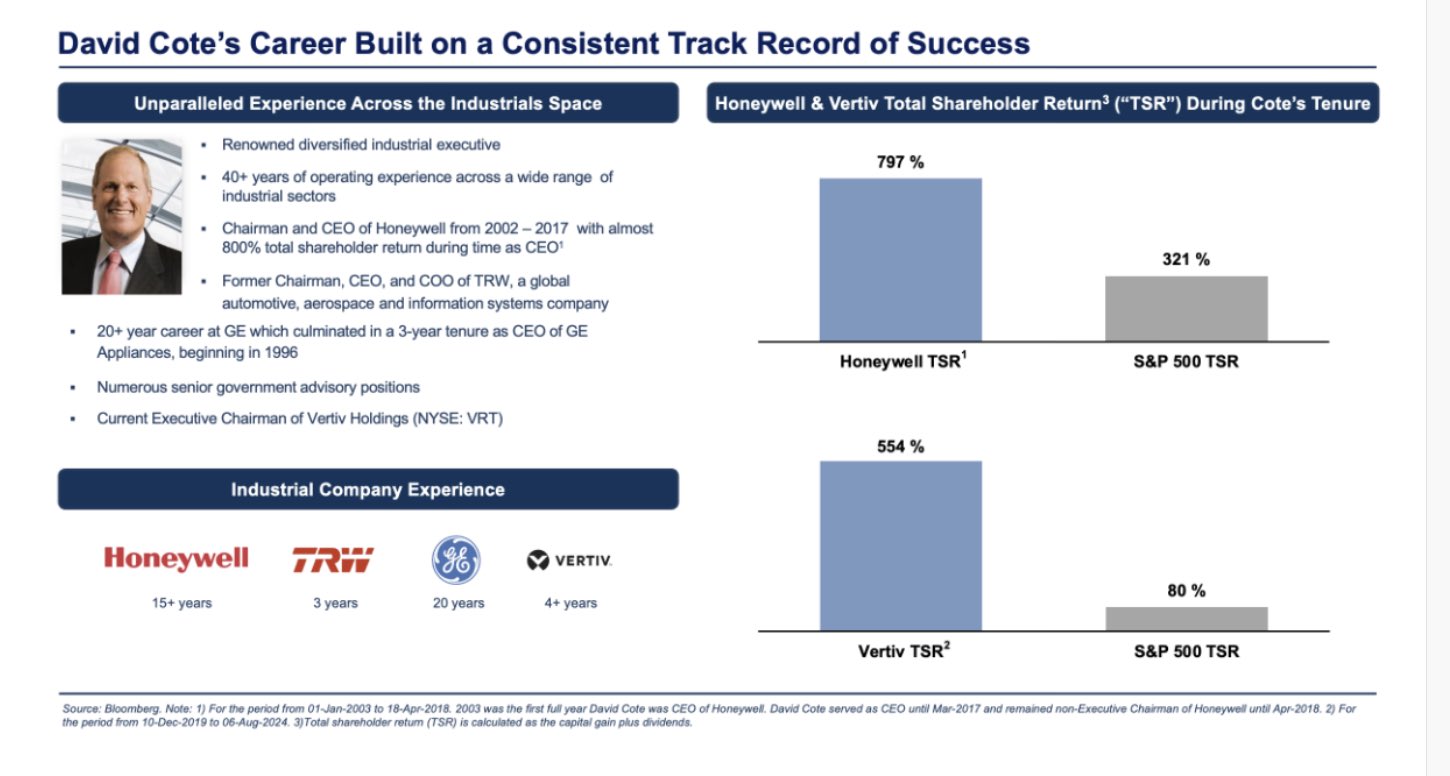
I think the idea behind the spin-off – as best as I can tell – is to monetize David Cote’s reputation.
The spin-off will be funded by a quarterly management fee funded by CompoSecure Holdings. The management fee is calculated as 2.5% of the trailing twelve month Adjusted EBITDA each quarter.
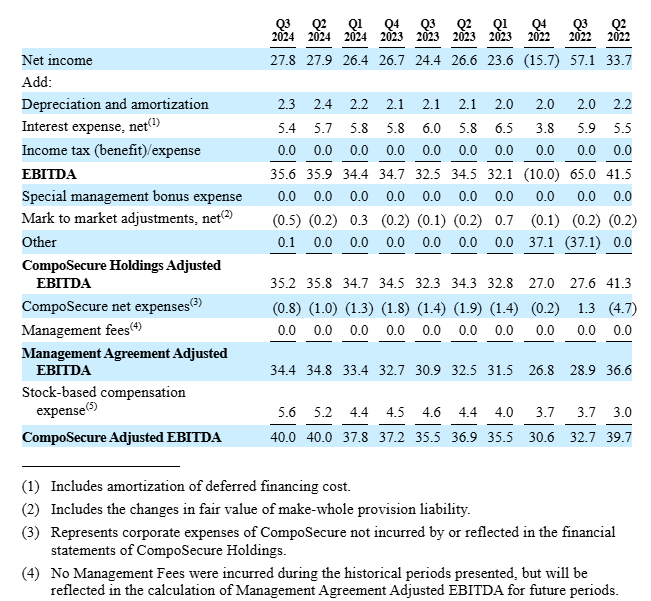
Here is the information statement for Resolute Holdings.
My thought is there is no downside to this spin-off and perhaps, significant upside, if the market gets excited.
CMPO currently trades at 11.8x EBITDA. CMPO will have to fund Resolute Holdings with ~$3.9MM every quarter (~$16MM per year). CMPO should lose $190MM of enterprise value (11.8x * $16MM) once the spin-off takes place (current enterprise value is $1.8BN).
Will Resolute Holdings have an enterprise value of greater than $190MM?
I don’t think it will initially. But over time, it should.
David Cote has grand M&A ambitions for CMPO and Resolute Holdings will benefit directly from each acquisition. Resolute Holdings views itself more as an alternative asset manager. The alternative asset management industry trades as high as 30x earnings (BX), a significant premium to CMPO.
Initially, I think Resolute Holdings has the potential to be sold indiscriminately given:
- Spin-off ratio. Shareholders will receive 1 share of RHLD for every 12 shares of CMPO
- Taxable transaction. This is a taxable transaction so shareholders are likely to sell their shares in order to pay the tax bill.
- Resolute Holdings will have “limited profitability in FY 2025”
Western Digital (WDC) will spin-off is flash (NAND) business, Sandisk (SNDK) on February 24, 2024.
Sandisk is trading in the when issued market at ~$37/share. It looks cheap trading at 0.8x annualized revenue.
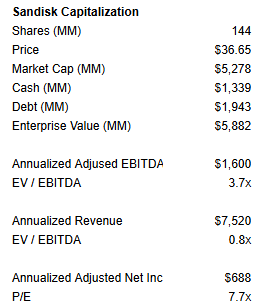
The flash industry is going through a midcycle slowdown, and so it makes sense that Sandisk isn’t valued highly. However, this looks too cheap.
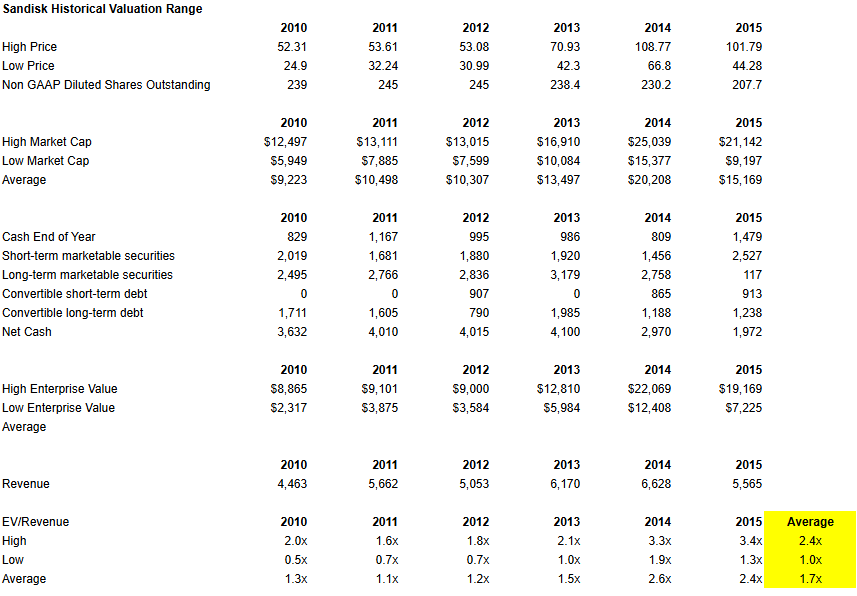
Last time SanDisk was publicly traded, it typically traded at ~1.7x revenue.
Western Digital RemainCo looks like a compelling story. It’s benefiting from secular tailwinds of increased data storage needs driven by AI.
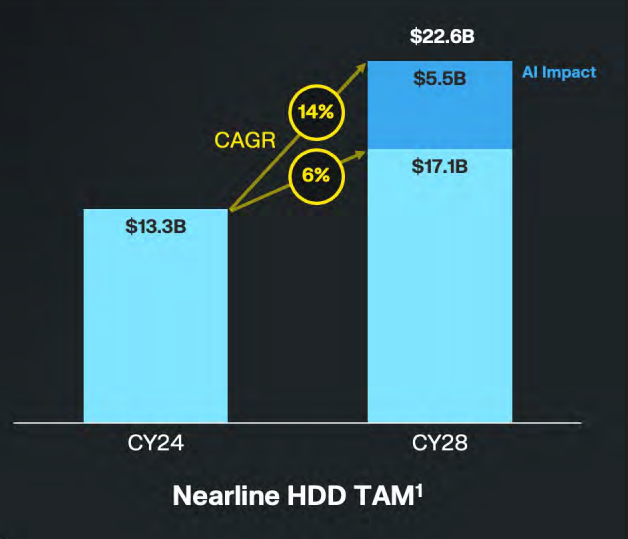
Yet competition is more muted given it operates in an oligopoly hard drive memory market with Seagate Technologies (STX).
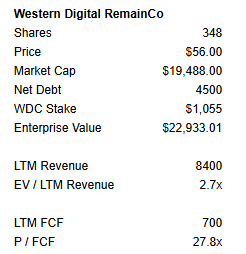
Seagate trades at 3.2x LTM revenue so Western Digital RemainCo has room for multiple expansion. The company is planning to return 100% of excess FCF to shareholders via dividends and share repurchases.
I think the transaction will unlock value.
Spin-off Links
Seeking Alpha: Magnera: An Unknown Company With Significant Upside Potential
- Articulates the investment thesis for Magnera well
Barrons: Spinoffs Are Often Market Winners. A Deal From Homebuilder Lennar Will Be a Test.
- Good Overview of Lennar spin-off
Recommendations Updates
(1) MAGN. When I originally recommended Magnera (MAGN) in November 2025, my investment thesis could be summarized as follows: “trough valuation on trough earnings.” And after the company reported earnings this week, that thesis remains intact. In its most recent quarter Magnera reported y/y sales and EBITDA growth, suggesting that results have troughed. On the valuation front, Magnera looks cheap. The cheapest Glatfelter (predecessor company Magnera) ever traded was 6.2x EBITDA (average: 10x). Magnera is currently trading at 6.5x FY 2025 EBITDA and 9.6x FY 2025 free cash flow, a cheap valuation given recent results are depressed. Finally, the CEO recently purchased ~$500k of stock which bodes well for future stock performance.
(2) IAC. IAC Inc. reported its fourth-quarter earnings for 2024 on February 11, 2025. IAC’s revenue for the quarter was $989.3 million, surpassing the anticipated $936.4 million. Barry Diller, who has returned to lead IAC, expressed optimism about the company’s future, particularly regarding Dotdash Meredith’s recovery. He also highlighted the planned spin-off of Angi, the home-services company, by the end of March 2025. This strategic move is expected to allow former CEO Joey Levin to serve as executive chairman at Angi, while Diller takes the lead at IAC. IAC was further buoyed when MGM reported a strong quarter and surged ~20%. IAC continues to look very cheap on a SOTP basis and the ANGI spin-off in March will unlock value.
Spin-off Calendar
Upcoming Spin-off Calendar | Completed Spin-off Calendar
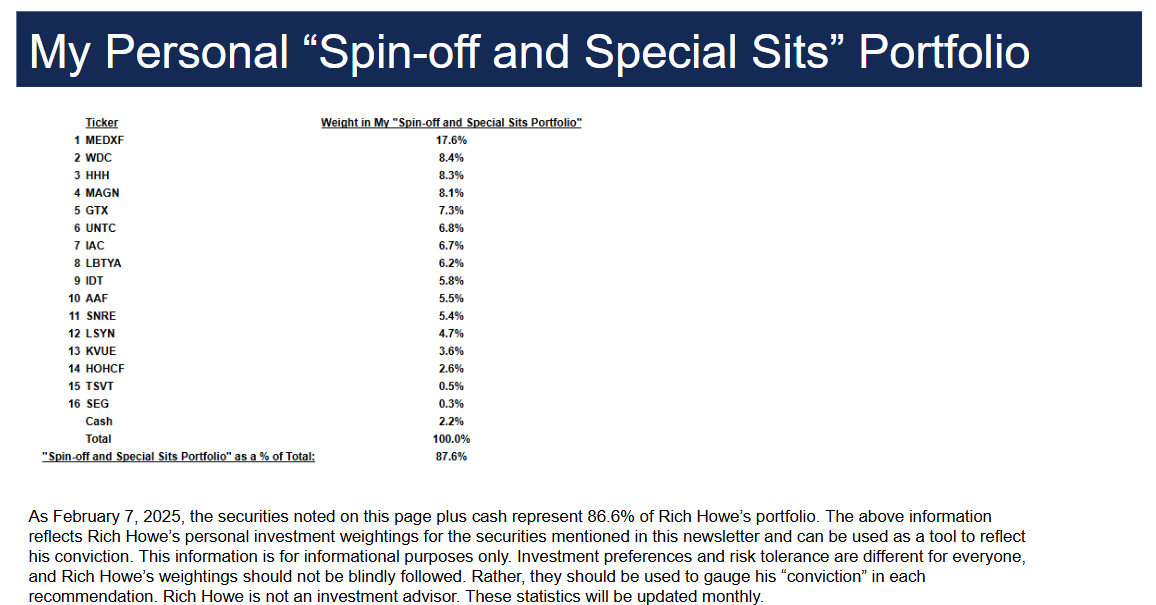
Current Positioning
(updated once a month)
Hope you had a great week!
Rich
Disclaimer:
Rich Howe, owner of Stock Spin-off Investing (“SSOI”), currently is long LSYN, IDT, MEDXF, GTX, AAF, IAC, UNTC, TSVT, KVUE, HGHAF, HHH, SEG, WDC, and MAGN. All expressions of opinion are subject to change without notice. This email is provided for informational purposes. Please do your own due diligence and consult with an investment adviser before buying any stock mentioned on www.stockspinoffinvesting.com.’
Leave A Comment