

Weekly Update (STRZ, LGFA, GTX, LBTYA, WDC)
May 3, 2025
Good morning,
Hello from Omaha!
This morning, I am attending the Berkshire Hathaway annual meeting. If you are in Omaha, and want to meet up, please let me know.
This week, we had three companies report earnings: Garrett Motion (good), Western Digital (good) and Liberty Global (bad). More details below…
I also recommended a new idea:
Buy Lionsgate Entertainment LGBA/LGFB).
Next Thursday, May 8th at 1pm ET, I will host my monthly zoom call.
You can use this link to join:
https://us06web.zoom.us/j/85794312105
Agenda:
- Review Lionsgate Entertainment (LGFA) Investment thesis
- Review initial trading for LION spin-off and STRZ RemainCo (spin-off will take place on May 6th)
- Initial thoughts on upcoming Holcim (HOLN) spin-off.
- Review current recommendations
- Answer subscriber questions (feel free to email me ahead of time)
Weekly Update
If you haven’t already, consider joining our discord channel (included with your paid subscription):
Join Discord Channel (you must create a free discord account to join)
It’s basically a chat room where we discuss what’s going on in the special situation market:
Here are a few things we discussed this week:
1. Q&A on Lionsgate Entertainment (LGFA)
2) Discussion of WDC’s recent results.
Recently Announced Spin-off
S&P Global (SPGI) announced on April 29, 2025, its intention to spin off its Mobility division into a standalone publicly traded company. This strategic move aims to streamline operations and allow S&P Global to concentrate on its core businesses: Market Intelligence, Ratings, Commodity Insights, and Dow Jones Indices.
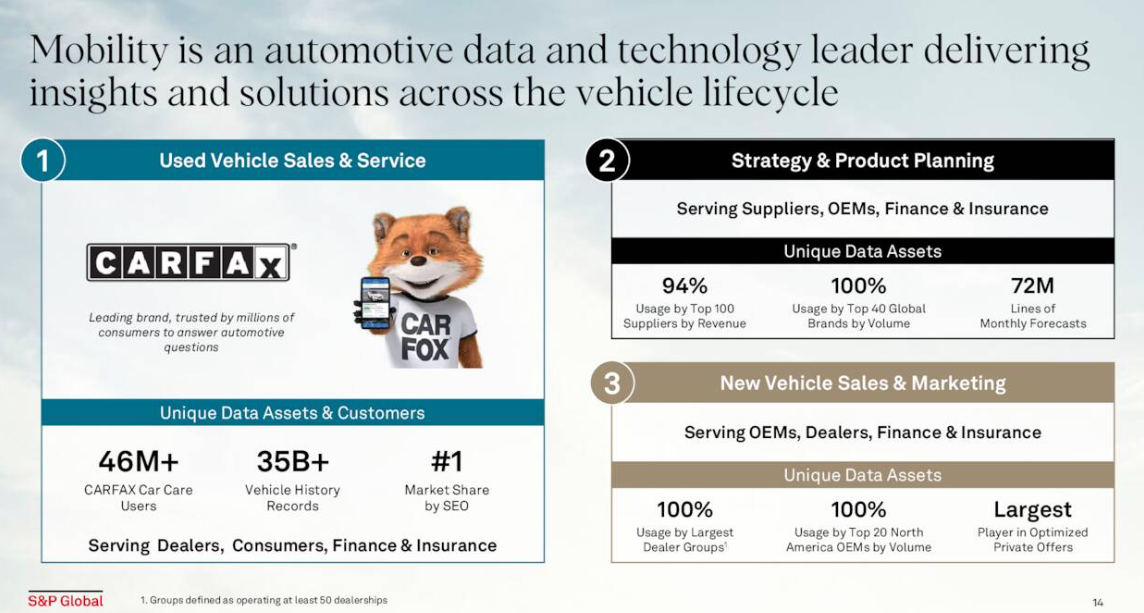
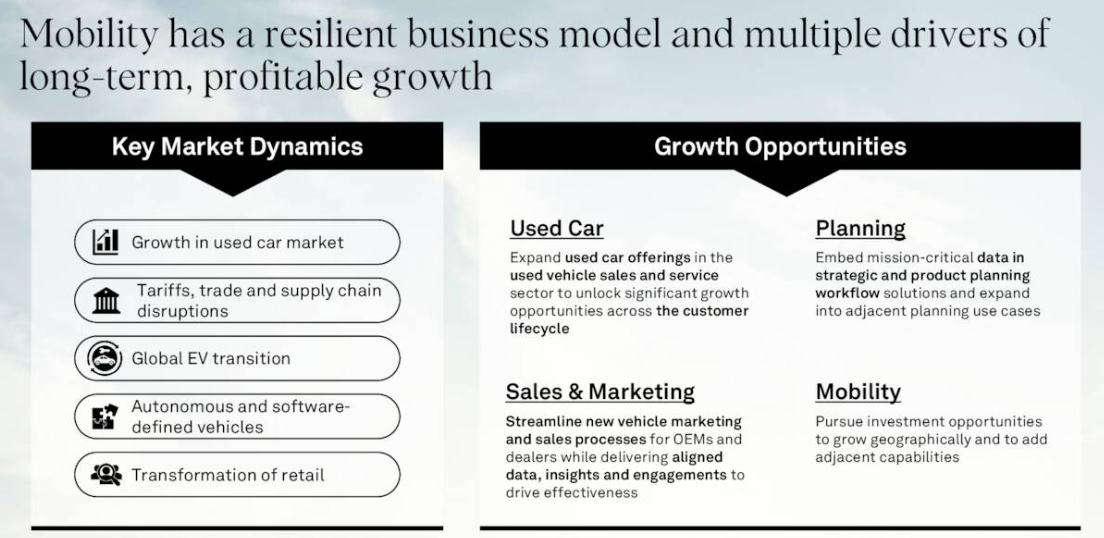
The Mobility division, which provides data and analytics to the automotive industry, generated $1.6 billion in revenue in fiscal year 2024, marking an 8% year-over-year increase.
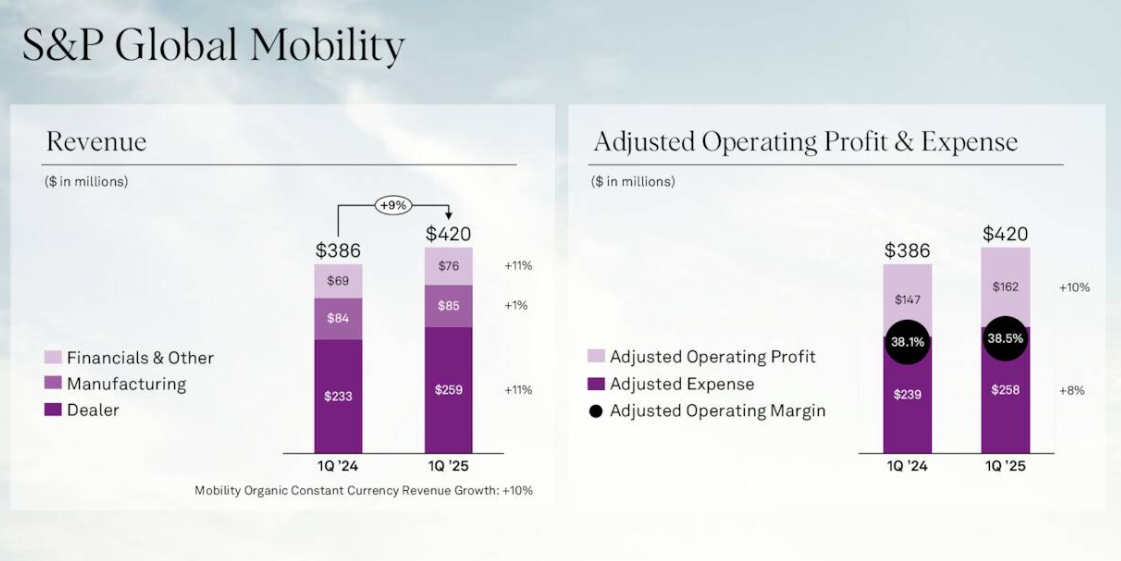
The separation is expected to be completed within 12 to 18 months, pending customary legal and regulatory approvals. The transaction is intended to qualify as tax-free for U.S. federal income tax purposes for S&P Global shareholder.
The Mobility business will be a high-quality spin-off with a favorable secular outlook. While it serves a different end market than S&P’s other business lines, the margin profile and growth outlook is similar to RemainCo’s. As such, I don’t know if it deserves to trade at a higher multiple than SPFI (11.2x revenue, 23.3x EBITDA).
Imminent Spin-offs
Next, week, Lions Gate Entertainment (LGF.A/LFG.B) is expected to spin off Lions Gate Entertainment (LION).
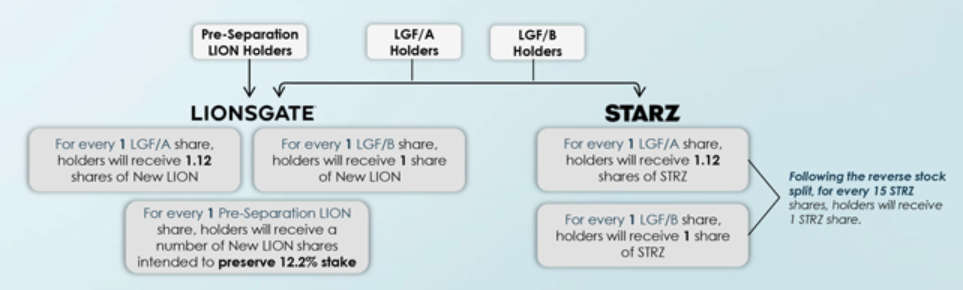
Management anticipates closing the transaction after the market closes on May 5th, 2025. The first day of trading will be May 6th. Lionsgate Studios will continue to trade under the ticker symbol LION while the RemainCo will be rename Starz and will trade under the ticker STRZ.
I think the transaction will unlock value.
LION will have 286MM shares outstanding while STRZ after the 1-15 reverse split, will have 17MM shares outstanding.
Lionsgate Studio has carved out a niche as a lean, franchise-focused independent studio that thrives in the mid-budget, IP-driven segment of the entertainment industry. It punches above its weight by targeting profitable genre films, franchise extensions, and strategic licensing — while avoiding the financial risk of mega-budget blockbusters.
Lionsgate appears to be trading at a discount to both Skydance (current valuation in Paramount deal) and other precedent transactions. Assuming LION deserves to trade inline with Skydance, it’s worth at least $11 per share. Independent studios are highly attractive acquisition targets for both larger cap tech (Amazon, Apple, Netflix) as well as private equity (Apollo, Blackstone, and KKR are active in the industry).
After its spin-off from Lions Gate Entertainment, I see 2 potential catalysts for the stock:
- Acquisition rumors.
- There are many potential buyers, and I think the company would sell for the right price. Two activists will own significant stakes in LION and ensure that shareholder value is maximized.
- Index inclusion
- Lionsgate Studios is not currently in the S&P 600 or any Russell indices given its limited float. However, the float issue will be resolved after the spin-off.
- LION currently has a $2BN market cap (median market cap of S&P 600 and Russell 20000 companies is $1.7BN and $1.0BN, respectively) and would be a good candidate for inclusion.
Starz (RemainCo) looks attractive as well, especially at the current valuation. The Starz business has successfully navigate linear TV headwinds. Over the past 7 years, revenue has stayed roughly flat while linear revenue has declined from $1,294 to $487MM.
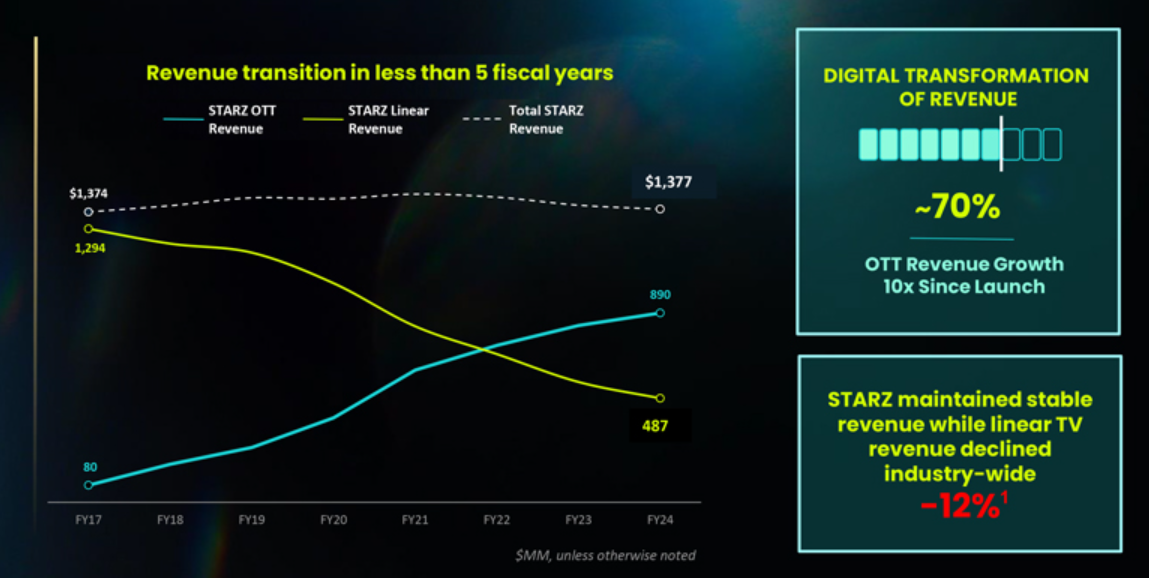
Currently, 70% of revenue comes from OTT subscribers.
In terms of its valuation, Starz looks cheap.
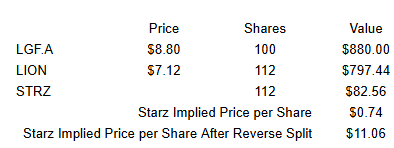
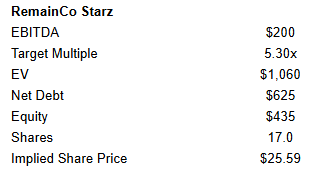
Starz is currently valued at $0.74 which works out to a market cap of $188MM and enterprise value of $788MM. As such, the stub is currently trading at 3.9x EBITDA and 2.2x FCF.
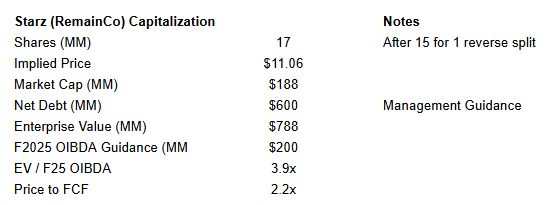
I think Starz is conservatively worth 5.2x which would correspond to a ~$26 share price.
Spin-off Links
- Electronics division spin-off is expected by November 1, 2025
Holcim Spin-off, Amrize, Files is Form 10
- The spin-off is expected to take place in June 2025
WSJ: Activist Bumps Aren’t Long Lived
- Interesting article on how activist involvement impacts stock price performance. Typically, there is an initial bump but it is followed by fading relative performance.
Sony Weighs Chip Spinoff That Dan Loeb Called for Years Ago
- Nothing concrete has been announced.
Recommendations Updates
(1 ) Western Digital (WDC).
Reported earnings on April 30th and the stock reacted well. Revenue increased 31% y/y to $2.29BN but misses consensus expectations of $2.48BN. Adjusted EBITDA of $670MM beat consensus expectations of $640MM while adjusted EPS of $1.36 beat consensus of $1.11.
Most importantly, WDC issued strong guidance. FQ4 revenue is expected to be $2.45 billion (midpoint), above consensus at 2.35 billion. EPS is expected to be$1.45 (midpoint) well ahead of consensus $1.14
Notably, the company reinstated a quarterly cash dividend of $0.10 per share (payable in June), the first payout since its flash business split.
Once net leverage hits 1.0–1.5x (net leverage is already 1.5x), the company plans to return 100% of excess cash via dividends and share buybacks. WDC is currently trading at 9x annualized free cash flow.
It is trading at 6.5x NTM EBITDA vs. 8.2x for STX. I see significant upside for WDC.
(2) Garrett Motion
Garrett Motion Inc. reported its first quarter 2025 results amid a challenging automotive environment, highlighting proactive measures on tariffs, a new shareholder returns program, and reaffirmed full-year guidance.
Tariffs and Cost Pass-Through
Garrett’s management has been vigilant about both existing and upcoming import tariffs. In Q1 2025, the company incurred approximately $4 million of costs from newly enacted import tariffs, but successfully passed 100% of these costs on to customers. CFO Sean Deason noted that this practice of full tariff cost pass-through is expected to continue throughout 2025, ensuring no negative impact on gross profit margins.
Garrett’s 2025 outlook remains unchanged.
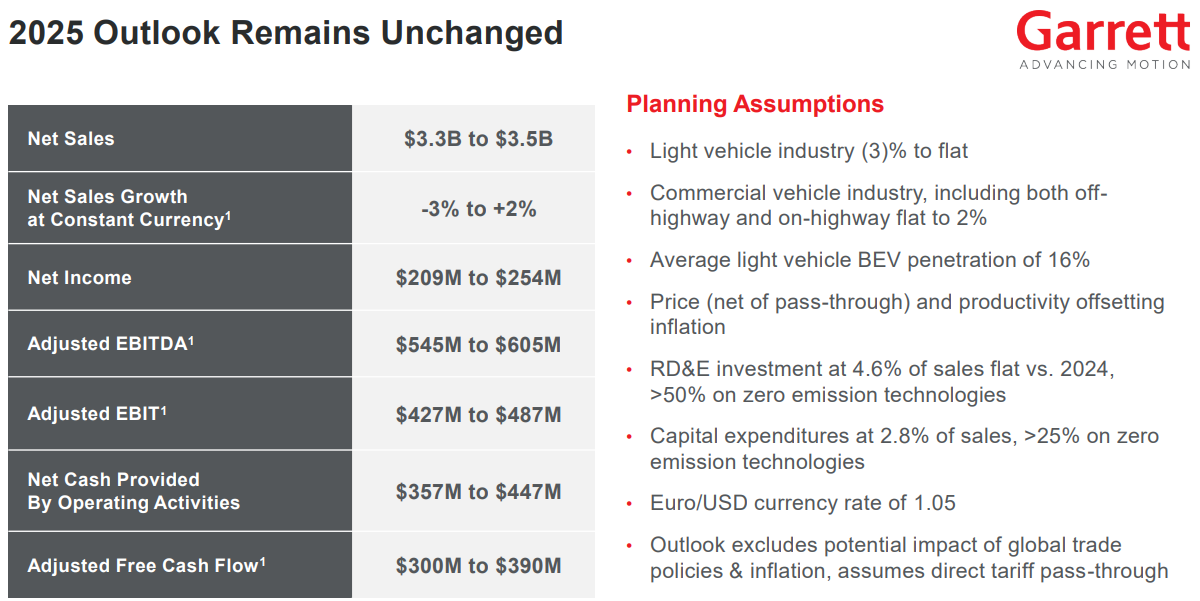
Garrett continues to look attractive at 6.2x EBITDA and 6.4x FCF. Net debt is 2.3x.
During the quarter, Garrett bought back $30MM of stock and returned $12MM to shareholders via the dividend. The company continues to aim to return 75% of free cash flow to shareholders.
One potential positive to watch is the USD/EUR exchange rate. The company assumes an of 1.05, but the current exchange rate is 1.13. If the exchange rate stays at current levels, we would see upside to the Company’s revenue and earnings guidance.
(3) Liberty Global
Liberty Global’s Q1 2025 results were mixed—stronger-than-expected operating performance was overshadowed by negative forward-looking developments, prompting a sharp selloff in the stock. The company reported revenue of $1.17 billion (up 7.3% Y/Y) and adjusted EBITDA of $324.6 million (up 14.7% Y/Y), both exceeding consensus expectations. These beats were driven by solid cost control, ARPU growth, and better-than-expected performance at VMO2 (UK) and Telenet (Belgium). Free cash flow was a seasonal outflow of $141 million, in line with expectations.
However, investor sentiment turned negative due to a significant guidance downgrade at VodafoneZiggo (Netherlands). Liberty now expects a mid- to high-single-digit decline in VodafoneZiggo’s 2025 EBITDA, versus prior expectations of flat to modest growth. The revision reflects aggressive competitive pressure, increased customer churn, and higher programming and labor costs. Analysts were surprised by the severity of the downgrade, which also reduces expected JV cash distributions to Liberty.
Additionally, Liberty paused its planned monetization of VMO2’s NetCo infrastructure, removing a potential near-term cash infusion. Combined with persistent competitive intensity across all markets and continued negative free cash flow at Telenet, investors grew concerned about the reliability of Liberty’s long-term value creation strategy and its ability to sustain buybacks.
Although management reaffirmed guidance for most of its operations and emphasized its $2.1 billion cash position and strategic flexibility, the market focused on deteriorating fundamentals in the Netherlands and a more cautious tone overall. The stock fell ~12% following the report, reflecting investor doubts about near-term earnings and capital return visibility.
I think the stock overreacted. Currently, the stock trades at $9.64 and has $6/share of cash, $1.60/share of listed investments (including Lionsgate), and $7/share of unlisted investments that it has been able to monetize successfully.
I think the stock looks compelling.
Spin-off Calendar
Upcoming Spin-off Calendar | Completed Spin-off Calendar
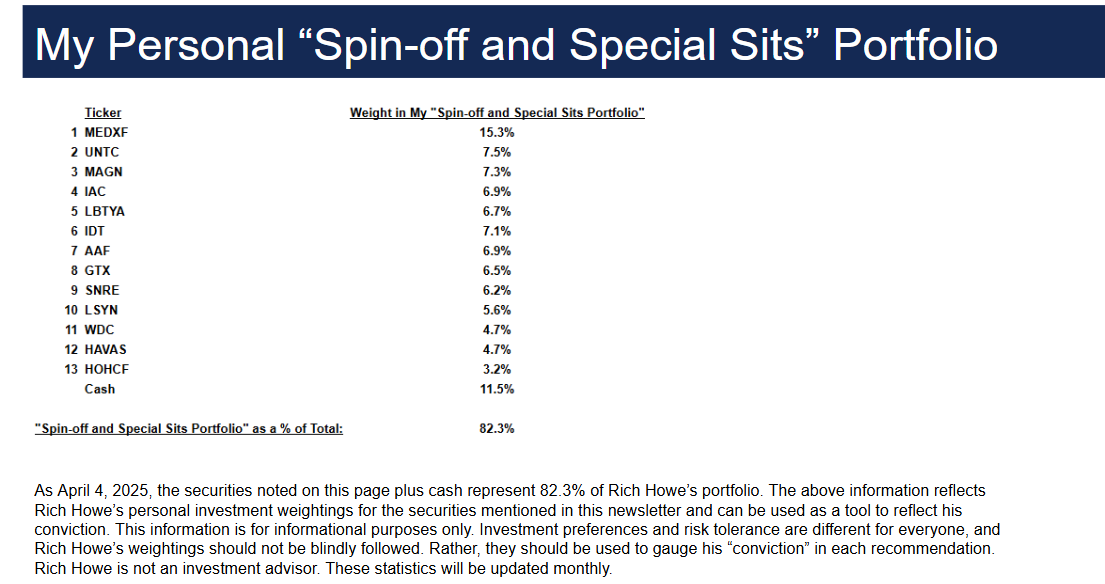
Current Positioning
(updated once a month)
Hope you had a great week!
Rich
Disclaimer:
Rich Howe, owner of Stock Spin-off Investing (“SSOI”), currently is long IDT, MEDXF, GTX, AAF, IAC, UNTC, HGHAF, WDC, MAGN, HAVAS. All expressions of opinion are subject to change without notice. This email is provided for informational purposes. Please do your own due diligence and consult with an investment adviser before buying any stock mentioned on www.stockspinoffinvesting.com.’
Leave A Comment