

Spin-off Links – May 2024
By my count, there have been 7 new US spin-off announcements in 2024. Meanwhile 4 new spin-offs have started trading in the US YTD.
Performance as measured by the S&P Spin-off ETF (CSD) has been quite strong with a YTD total return of 12.7% comparing favorably to the SPY.
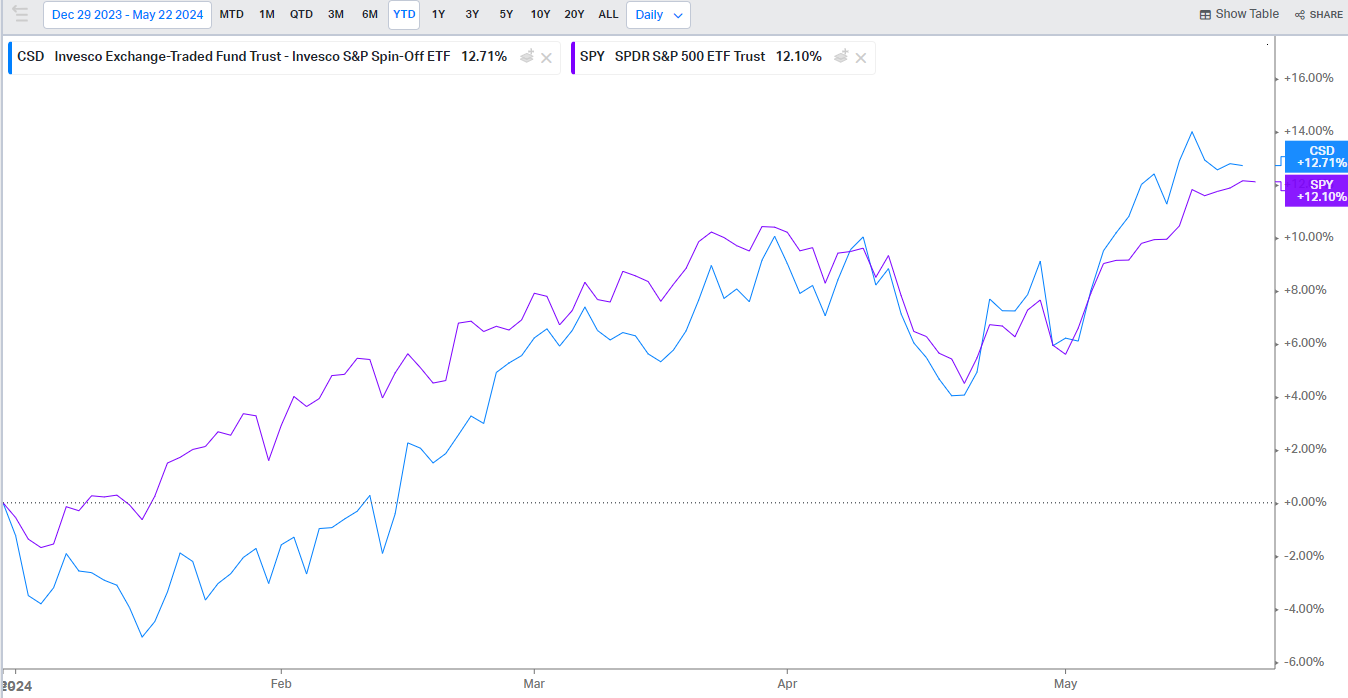
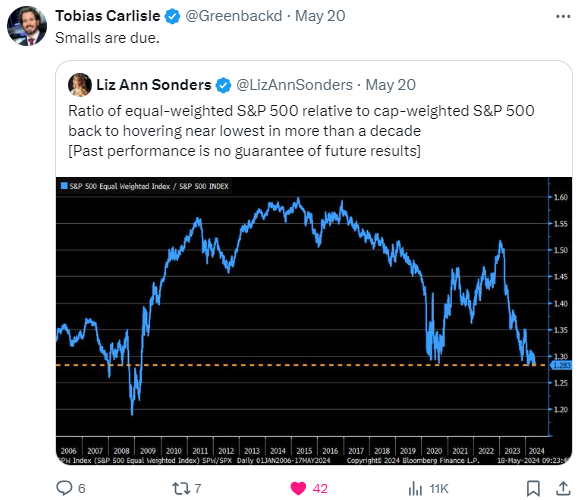
This is somewhat surprising because spin-offs tend to be rather small in market cap and small and mid sized companies have had a rough go of it.
Without further ado, let’s move on to the latest spin-off news….
Recently Announced Spin-offs
On May 9, 2024, gene sequencing company Illumina (ILMN) announced that it will spin off blood cancer test maker Grail.
In December 2023, Illumina had announced that it would divest itself of Grail (but didn’t specify whether the divestiture would happen through spin-off, capital markets transaction or asset sale) following a legal battle against U.S. antitrust regulators.
Why is Illumina divesting Grail? Didn’t it just by the company recently?
Yes! Illumina agreed to buy part of Grail for $7.1BN in 2020. But at the time, neither the U.S. Federal Trade Commission nor its European counterpart approved the deal.
Illumina ignored the regulators and closed the acquisition In July 2023, Illumina was fined a record 432 million euros ($471 million) by the European Union for closing its takeover of Grail before securing EU antitrust approval. Both agencies have ruled that Illumina must unwind its deal and appeals have gone against Illumina.
As such, Illumina has made the decision to halt further appeals and proceed with a divestiture. European regulators have determined that Grail must capitalize Grail with 2.5 years of funding and that Grail must be as competitive after the divestiture as it was before the acquisition.
Illumina is a leading provider of gene sequencing machines and the related products that are needed to run them. Grail uses machines to conduct blood tests that can detect multiple types of cancer quicker than conventional testing (sometimes referred to as liquid biopsy). Analysts believe the cancer blood test market could eventually be a $50BN market. What is interesting is that Illumina previously founded Grail and spun the business off in 2016 (while retaining a small stake). But in 2020, it decided that it wanted to buy back the business, and this triggered the antitrust concerns.
Illumina’s currently has a market cap of $17.4BN and enterprise value of $18.5BN. Analysts expected Illumina to generate revenue of $4.9BN in 2024 and $5.4BN in 2025. According to its Form 10, Grail generated 2023 revenue of $93MM and negative $523MM adjusted EBITDA.
I think this situation looks pretty interesting. I don’t know what Grail is worth, but Illumina acquired it at an implied valuation of $7BN. Consensus expectations are for Illumina to generate $3.90 in 2026. As such, it’s trading at 28x 2026 earnings. This doesn’t seem like an unreasonable multiple to pay for the market leader in the gene sequencing industry. And then on top of that, you are getting a potentially valuable spin-off.
Recent Spin-offs
On April 1, 2024, 3M (MMM) spun off 80.1% of its healthcare business in a tax free transaction. The remaining 19.9% will be monetized over the next 5 years. The new business will be named Solventum (SOLV). Importantly, 3M will retain responsibility for non-Health Care related litigation, including those related to Combat Arms Earplugs and PFAS.
Solventum generated $8.3BN of revenue in 2023 25% adjusted operating margins. It generated over $1.4BN of free cash flow in each of the past three years. 56% of revenue comes from the US while 44% is international. Revenue is generated by 4 different divisions: MedSurg (56% of revenue), Dental Solutions (16% of revenue), Health Information Systems (16% of revenue) and Purification & Filtration (12% of revenue).
Its peers (DHR, HSIC, JNJ, STE, TMO, and XRAY) trade at 14x forward EBITDA. Most sell side analysts think SOLV deserves to trade at a discount to peers given its organic revenue growth outlook for 2024 (0% to -2%) and high leverage profile (3.7x net debt). Assuming SOLV deserves to trade at 12x 2024 EBITDA, it would be worth a fair enterprise value, market cap, and share price of $28BN, $20BN, and $114. SOLV is currently trading at $62 and looks attractive from a valuation perspective. The only problem is it’s a bit of a messy story given revenue is expected to shrink this year. I’m going back and forth with investor relations on some questions, but I think the stock looks relatively attractive. I published a deep dive here.
AP Moeller (CPSE: MAERSKB) spun off its towage and marine services business Svitzer (CPH: SVITZR) on April 30.
Svitzer is the world’s largest towage business. It owns 456 vessels and operates in all geographic regions. The market for towing is much more stable and predictable than the broader shipping market. For example, revenue only declined by ~5% during 2020 (Covid). However, the business is very capital intensive. Svitzer has 29% EBITDA margins but spends 25% of revenue on capex. A significant portion of the capital spending is for growth, but maintenance capex is still significant.
SVITZR is currently trading at 251DKK. At that price, it has a market cap of 7.9BN DKK ($1.1BN USD). The company has two turns of debt and has an enterprise value of 11.2BN DKK. It’s trading at an EV/EBITDA multiple of 6.4x. On a price to free cash flow basis, the stock is trading at 36x. If you exclude the spending that Svitzer categorizes as “growth capex,” the stock is trading at 9x this adjusted free cash flow number.
I don’t have a strong view as to the appropriate valuation for Svitzer, but its current valuation seems reasonable. This Bloomberg article states that sell side analysts believe Svitzer is worth an enterprise value of $1.2BN to $2.3BN. Its current enterprise value is $1.6BN.
Imminent Spin-offs
On January 22, 2024, Sanofi (SNY) announced that it had agreed to buy U.S. biotech company, Inhibrx (INBX) in a deal valued up to $2.2BN.
The deal is structured such that SNY will acquire Inhibrix’s INBRX-101 which is currently in the second of three phase three trials, while the remaining drugs will be spun off into a separate public company (Sanofi will retain an 8% stake). It will be funded with $200MM of net cash.
INBRX-101 is designed to treat Alpha-1 Antitrypsin Deficiency (AATD), an inherited rare disease that causes progressive deterioration of the lung tissue.
Under the terms of the deal, INBX shareholders will receive $30 per share in cash, a spin-off in a new company, and a CVR that is worth up to $5. INBX currently trades at $34.29. I assume the new company will trade at 50% of its net cash. This works out to a fair value of $2.11. That implies that the market is valuing the $5 CVR at ~$2.18. The $5 CVR will pay out if INBRX-101 gets approved for AATD by June 30, 2027.Given that SNY is paying $1.6BN to acquire INBRX-101, I think odds are pretty high that the drug will get approved. Clark Street Value did a nice job of writing up INBX.
Regular way trading will begin on May 30th.
Spin-off Links
Howard Hughes Holdings: Follow The Insider Buying
- Good write-up.
Inhibrx Inc: Cash Buyout + SpinCo (Inhibrx Biosciences) and CVR
- Interesting write up. I think the risk/reward looks positive.
Seeking Alpha: Baxter International: Shares Too Cheap, EPS Growth Ahead With A Possible Spinoff
– Good write up on Baxter
Kyndryl Stock Is on Track for Record Day. IBM Spinoff Is Getting Closer to Growth.
– Kyndryl has had an impressive turnaround.
– Interesting special situation

Leave A Comment